
AI is driving demand for electricity, putting Constellation Energy (CEG) and Vistra (VST) in an unusual position as two major nuclear-powered bets on the AI boom. As hyperscalers build more AI data centers, reliable power is becoming a critical part of the infrastructure stack, and nuclear providers are high on their shopping lists.
Constellation is the larger company, with a bigger nuclear fleet and major long-term contracts with companies like Microsoft (MSFT) and Meta Platforms (META). Vistra, meanwhile, is smaller but has more contracted hyperscaler power and a broader mix of generation assets.
Both companies have a strong case for ownership. But the better stock depends on how much growth investors are paying for today. So let's look at their numbers and see which one comes out ahead, starting with the company that owns the bigger nuclear fleet.
Constellation Has the Bigger Nuclear Fleet and Big Tech Contracts
Constellation has a large nuclear business and long-term deals with major technology companies. For example, its 20-year Microsoft deal covers 835 MW from the Crane Clean Energy Center in Pennsylvania, which is expected to restart in 2027.
Meanwhile, Meta also signed a 20-year power deal, covering 1.12 GW of clean nuclear energy from Constellation's Clinton, Illinois, facility and is expected to begin in June 2027.
On top of that, the company added 920 MW of long-term nuclear power purchase agreements (PPAs) during the second quarter of 2026, with terms ranging from 15 to 20 years. These contracts turn Constellation's nuclear fleet, which has more than 22 GW of capacity, into a more predictable AI infrastructure asset.
Then, after acquiring Calpine Corporation in January 2026, Constellation's total generation portfolio reached about 55 GW across nuclear, natural gas, geothermal, hydro, wind, and solar. For perspective, that capacity can power 45 million U.S. homes for a year.
Management also raised adjusted operating earnings guidance for 2026 to $11.50 to $12.50 per share, and projected about $8.4 billion in free cash flow before growth investments in 2026 and 2027. That gives Constellation plenty of runway to invest in its fleet and lock in more contracts.
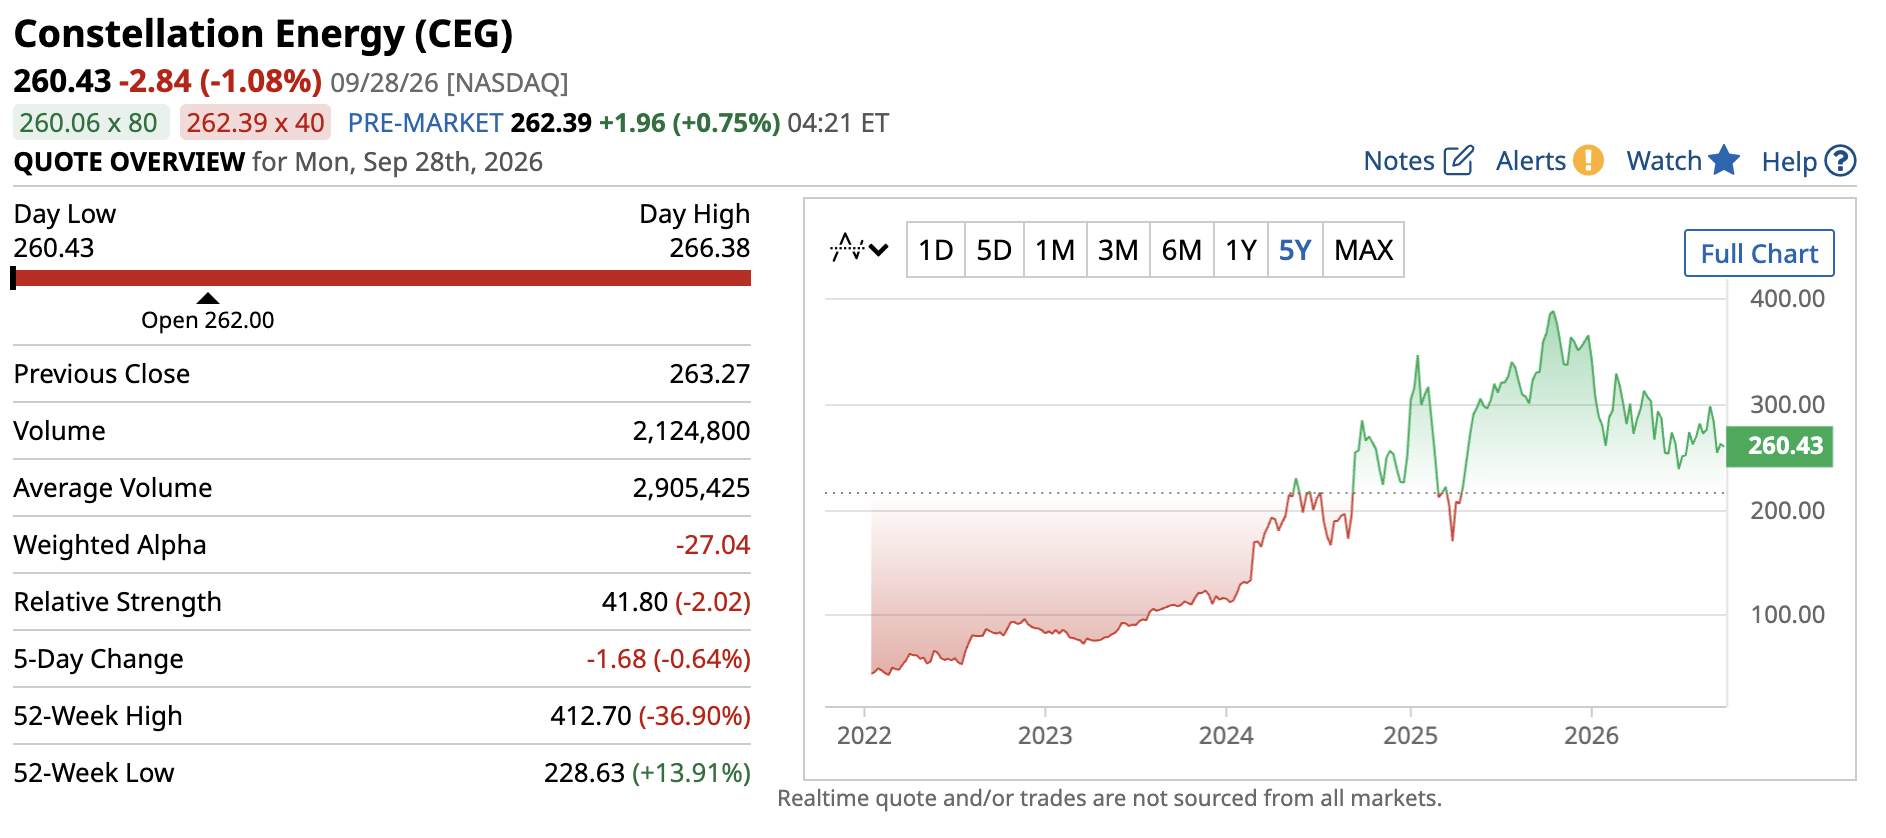
But the tradeoff here is price. At 21x forward earnings versus the Energy sector's 17x, Constellation shares aren't cheap, so the company needs sustained earnings growth to justify the price tag.
Still, nuclear plants can't be built overnight, and existing reactors can provide steady power for decades. That kind of scarcity becomes valuable as utilities and data centers compete for reliable electricity.
Plus, owning the stock pays $1.71 per share per year in dividends, which works out to a 0.65% forward yield. It's not the highest utility yield out there, but it helps a little for investors who plan to hold shares long term.
Vistra's nuclear fleet is smaller, but its contract book tells a different story.
Vistra Has More Nuclear Power Under Contract With Hyperscalers
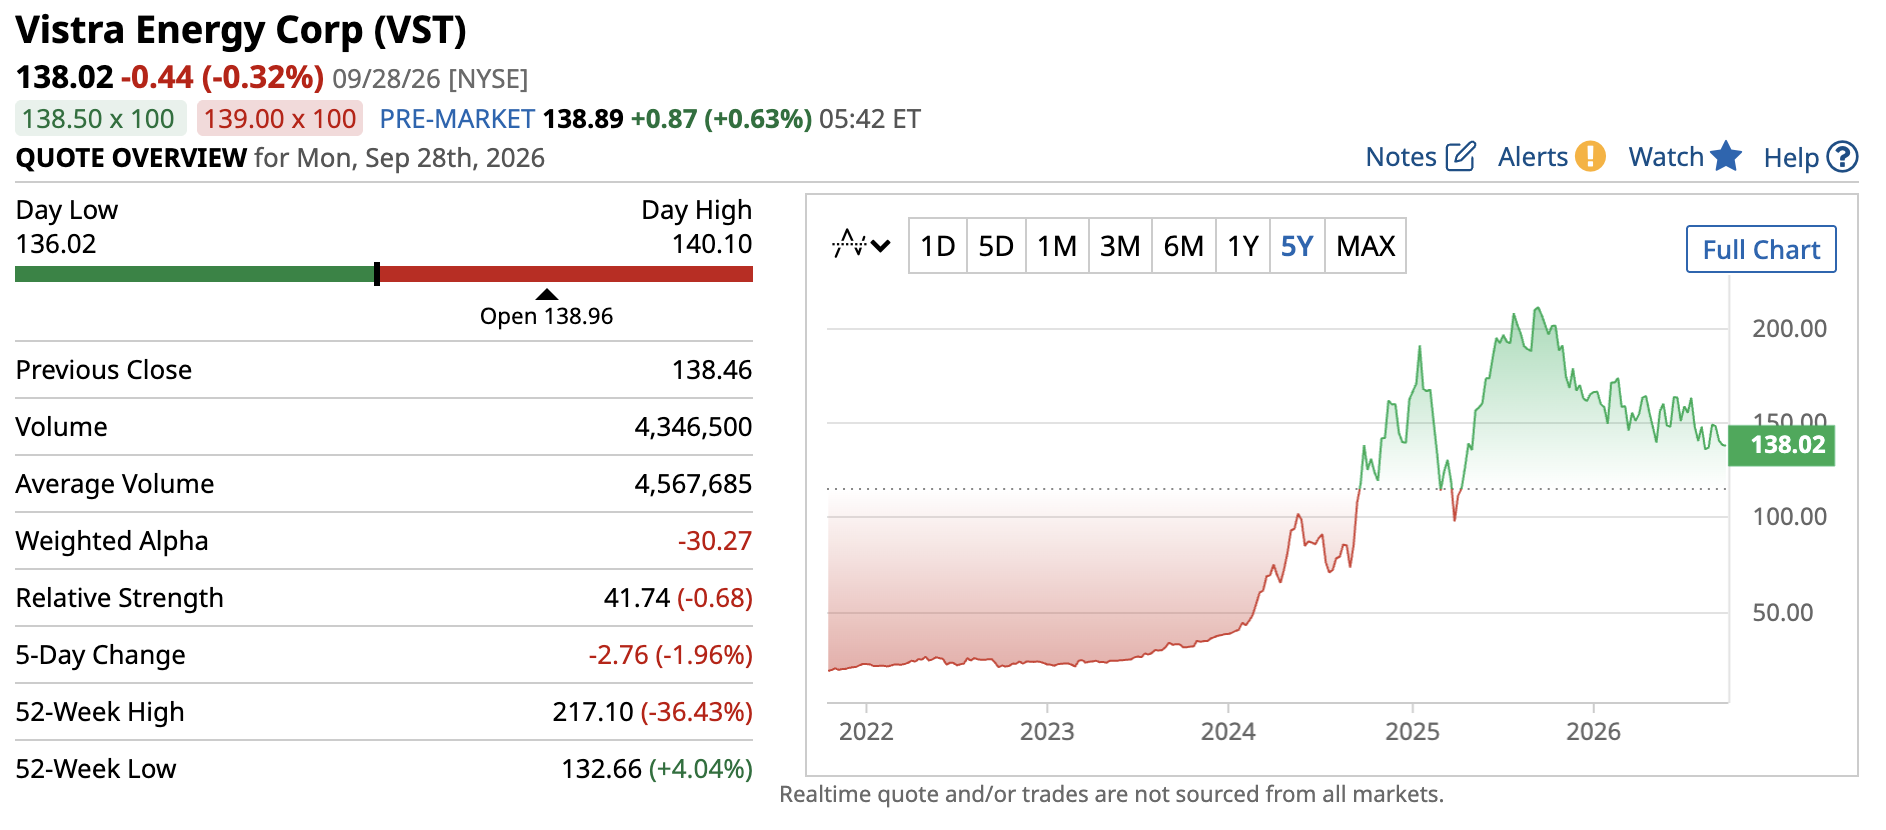
Unlike Constellation, Vistra's nuclear fleet is much smaller at about 6.4 GW. However, its disclosed hyperscaler contracts cover more nuclear capacity than Constellation's Microsoft and Meta deals.
For example, its 20-year deal with Amazon (AMZN) Web Services (AWS) covers up to 1.2 GW at Comanche Peak, while its Meta agreements cover 2.6 GW across the Perry and Davis-Besse plants in Ohio and Beaver Valley in Pennsylvania. That gives Vistra roughly 3.8 GW of nuclear capacity contracted to AWS and Meta, well ahead of Constellation's approximately 1.95 GW across its Microsoft and Meta agreements.
Vistra also has more ways to benefit from rising electricity demand. Beyond nuclear, its portfolio spans natural gas, solar, retail electricity, and battery storage. On top of that, in June 2026, Vistra partnered with the Kuwait Investment Authority and Nvidia (NVDA) to launch Helix Digital Infrastructure, giving it another avenue into AI data center demand.
Financially, management expects strong growth in 2026, with adjusted EBITDA of $6.8 billion to $7.6 billion and free cash flow before growth of $3.9 billion to $4.7 billion. Its 2027 EBITDA outlook of $7.6 billion to $7.8 billion doesn't yet factor in the pending Cogentrix acquisition or its power purchase agreements with Meta.
But Vistra carries around $19 billion in debt and plans about $3 billion in capital spending for 2026. Even so, at 15x forward earnings, it trades at a notably lower valuation than Constellation.
Dividend investors may be interested to know that Vistra pays 92 cents per share, which translates to a 0.67% forward yield, nearly the same as Constellation's.
So with the numbers side by side, which one deserves the edge?
Why Vistra Looks Like the Better Pick Over Constellation
The valuation gap likely reflects the market's view that Constellation owns some of the highest-quality nuclear assets in America, which is why its shares trade at a premium. The question is whether that premium leaves enough upside for investors.
For my money, Vistra's lower valuation means investors pay less for each dollar of future earnings, creating a more favorable risk-reward profile if AI-driven electricity demand continues. Even better, a consensus among 17 analysts rates Vistra a “Strong Buy,” with an average score of 4.88 out of 5. To be fair, though, Constellation also has a "Strong Buy" rating, with an average score of 4.45.
That said, the right choice depends on the investor. Constellation is the safer play, best for investors who want premium nuclear assets and long-term contracts and are willing to pay up for that quality. Vistra is the higher-reward play, better for investors who want AI power exposure at a lower valuation and can live with roughly $19 billion in debt. So if I have to choose just one, it's Vistra.