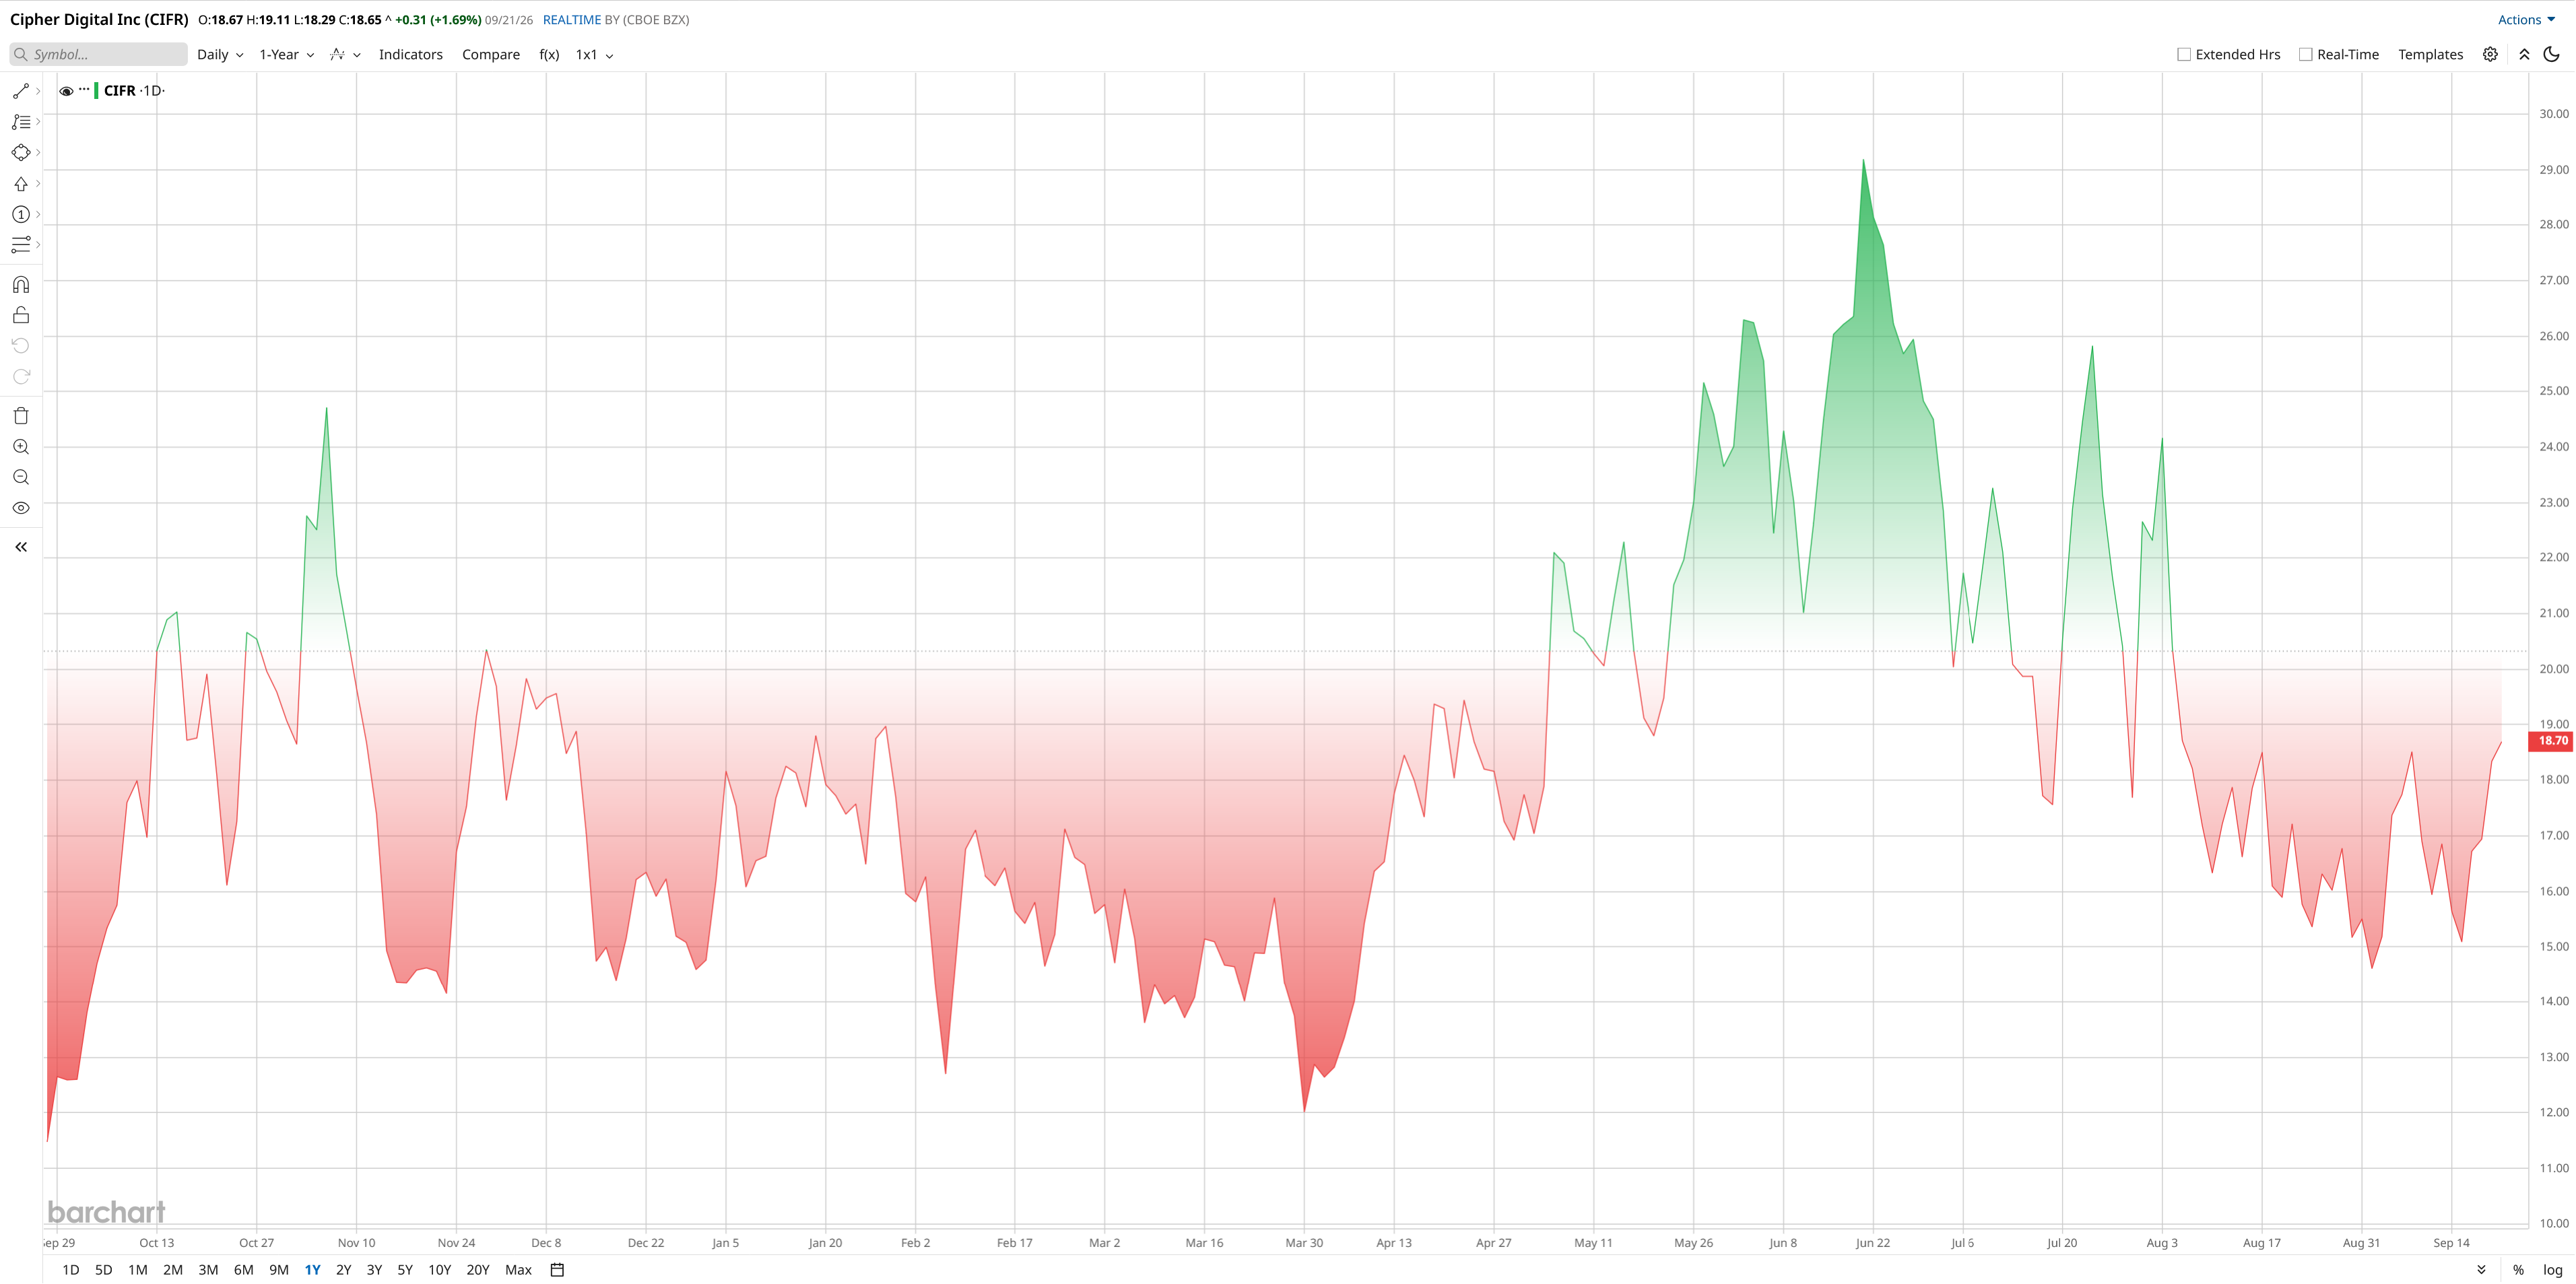
Cipher Digital (CIFR) just gave investors another reason to watch the company as the AI infrastructure trade shifts toward power and data center capacity. Shares jumped more than 14% on Wednesday after ERCOT conditionally classified 3.2 gigawatts of the company’s Texas data center projects. Even after that rally, the stock remained about 44.5% below its 52-week high of $30.
The rally came despite a weak latest quarter. Cipher’s second-quarter revenue was $24.84 million, down from $43.57 million a year earlier and below the roughly $32.52 million consensus estimate. Its loss per share was $0.65, also worse than the expected $0.23 loss.
Revenue still came almost entirely from Bitcoin (BTCUSD) mining, while the HPC business was only starting to contribute. In other words, Wednesday’s move was driven by what Cipher could build next, not what it earned in the latest quarter.
The AI Infrastructure Shift Is Changing the Story
Cipher has spent 2026 moving beyond its Bitcoin-mining roots and toward high-performance computing. The company now has 907 megawatts of operating and contracted capacity, while its broader pipeline has grown to about 4.4 gigawatts. Its contracted revenue stands at roughly $11.4 billion, according to its latest investor presentation.
That makes power access a major part of the investment story. ERCOT’s latest conditional classifications cover 1.1 gigawatts of base-load capacity at Stingray and Colchis, plus another 2.1 gigawatts under study across Mikeska, Apollo, Stingray Phase II, and McLennan. The designations are still conditional, with final classifications expected after a state-ordered audit. Still, the update gives investors more visibility into how much capacity Cipher may eventually bring online.
The Valuation Leaves Little Room for Mistakes
CIFR is not a cheap stock on today’s financial results. It trades at about 36 times trailing sales, compared with roughly 9 times for a peer group. The company also trades at about 35.6 times forward earnings.
Those figures are high because the market is valuing Cipher on future HPC cash flows rather than current mining revenue. Its latest presentation shows net operating income rising from about $97 million in 2026 to $686 million in 2027. That is a major jump, but it also shows why execution matters. If projects are delayed, costs rise, or tenants do not scale as expected, the premium valuation could become a problem.
Cipher Is Building More Than One AI Site
The company has several projects that can push the story forward. At Black Pearl, Cipher delivered its first data center capacity in August, two months ahead of schedule, and rent has started. Black Pearl is tied to a 15-year Amazon (AMZN) Web Services lease for about 300 megawatts.
Barber Lake is also progressing, with the tenant already using part of the facility. Cipher has fully funded Stingray through a project-level bond offering and secured an option for Apollo, a potential 900-megawatt site near San Antonio. These projects show the company is building a pipeline of contracted and potential capacity rather than relying on a single AI campus.
What Does Wall Street Think of CIFR Stock?
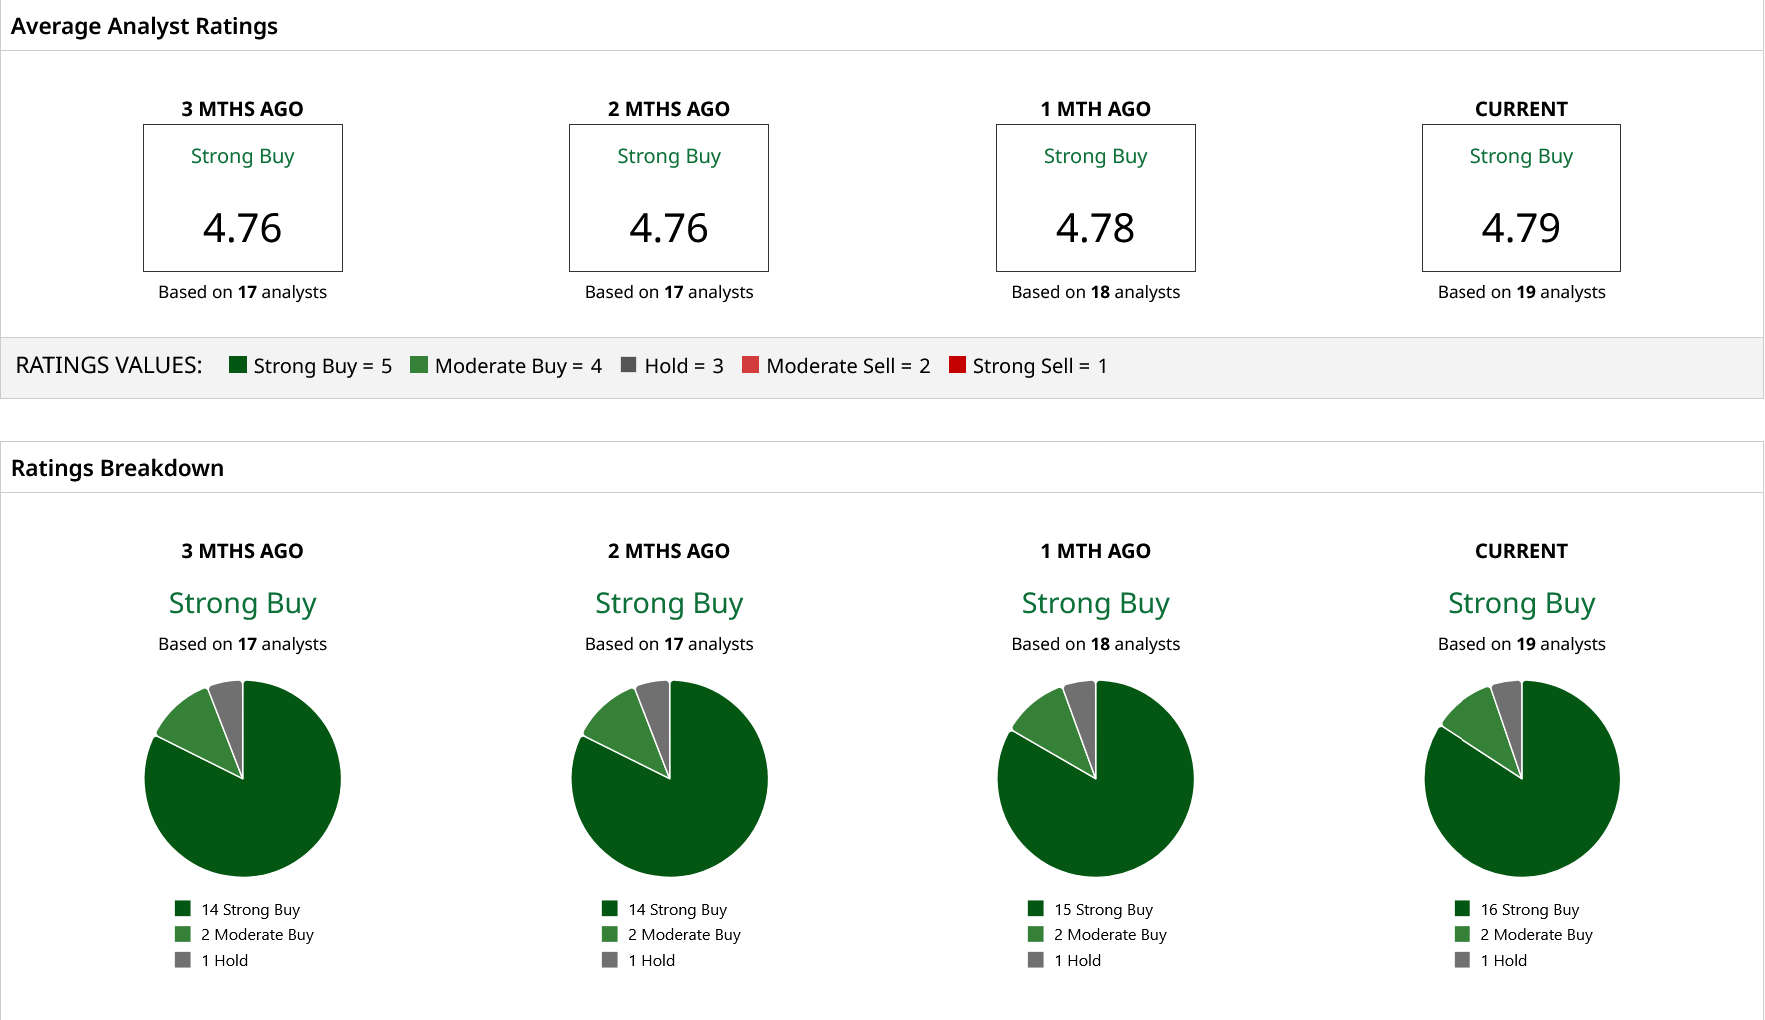
Analyst views remain positive, but price targets vary widely. As of the latest available updates, Rosenblatt has a $30 target, Needham has $25, J.P. Morgan has $22, and Morgan Stanley has $43.50. Jefferies previously initiated coverage at $32. The consensus rating is “Strong Buy,” and the mean price target is $29.08, implying 55% upside potential.
The gap between the current share price and those targets shows both the opportunity and the risk. Cipher’s AI pipeline is expanding, but the company still has significant construction, financing, and execution work ahead.
For CIFR stock, the key question is becoming less about Bitcoin mining and more about whether Cipher can convert power access into profitable AI infrastructure.