Investors seeking hidden margin expansion often overlook traditional retail operations. However, value-focused investors might consider Best Buy Co., Inc. (NYSE: BBY), as it is actively shifting its operating model from a low-margin hardware distributor to a high-margin digital advertising platform.
An expanded programmatic television agreement with Amazon.com, Inc. (NASDAQ: AMZN) serves as the primary catalyst for this structural evolution. With Best Buy's in-house media network approaching an estimated $1 billion annual revenue run rate and an upcoming leadership change designed to accelerate this hybrid strategy, the market may be mispricing the underlying profitability potential.
Understanding how connected television advertisements alter the fundamental math for a physical retailer reveals a compelling case for multiple expansion. Integrating digital advertising into physical retail changes the valuation framework for this specialty retailer, paving the way for a redefined fundamental outlook.
Best Buy Broadcasts a New Business Model
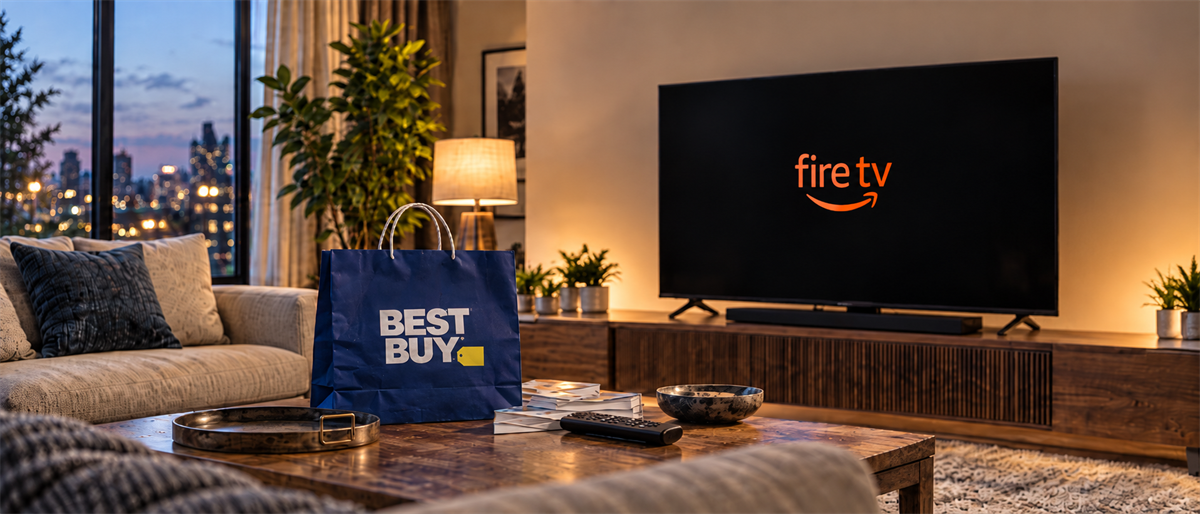
The traditional model of buying electronics wholesale and selling them at retail leaves little margin for error. Best Buy is changing that equation through its expanded multi-year Fire TV partnership with Amazon. This agreement integrates Best Buy Ads and Amazon’s programmatic advertising technology directly across Insignia television hardware. Starting around February 2027, the retailer will capture captive, connected television advertising revenue long after the customer leaves the physical store.
This setup turns a one-time hardware transaction into a recurring revenue stream. In a digital advertising landscape where third-party cookies are depreciating, the first-party shopper data Best Buy collects daily is highly valuable to consumer brands.
Advertisers will pay a premium to target consumers based on verified purchase history rather than inferred browsing habits, putting Best Buy in a strong position to monetize its customer base without adding inventory risk. By transforming the physical living room into an extension of the retail floor, the retailer creates a closed-loop ecosystem that benefits both the consumer and the advertiser.
Upgrading the Financial Picture
To appreciate the impact of this media deal, investors need to look at the underlying margin structure. Consumer electronics retail is structurally tight. Best Buy operates with a net margin hovering around 3.01%, which is standard for the industry, given the high costs of inventory management, logistics, and physical store operations. Retail media networks function more like software businesses, generally carrying profit margins between approximately 70% and 90%.
Best Buy Ads has already generated about $900 million in fiscal year 2026. Management projects 10% growth in fiscal 2027, pushing the ad network close to a $1 billion revenue run rate. Layering nearly a billion dollars of high-margin revenue on top of a commoditized retail base shifts the bottom line. Because digital advertising inventory carries minimal variable costs, the revenue generated from the Amazon Fire TV integration will flow directly to net income.
This media overlay requires a stable retail foundation to function, and recent financials indicate the core business is holding its ground. In the second quarter of fiscal year 2027, Best Buy reported earnings per share of about $1.47, beating consensus estimates by roughly 8 cents. Enterprise comparable sales grew about 4.1%, surpassing the Street's 1% expectation. This top-line stabilization gave management the confidence to raise full-year fiscal 2027 guidance, ensuring the physical footprint remains viable while the digital ad business scales.
A New CEO Navigates Hardware Pressures
Strategic transitions require aligned leadership. As of Nov. 1, 2026, Jason Bonfig will step in as CEO, replacing Corie Barry. Bonfig played a central role in building out both the retail media network and newer small-store formats. His appointment signals a clear board mandate to prioritize data monetization and physical footprint efficiency over sheer square footage.
This strategic pivot comes out of necessity amid ongoing macroeconomic pressure in the hardware sector. The core computing category faces challenges from rising memory chip costs. These higher component costs are pushing average selling prices up, which in turn suppresses overall computing unit volumes.
When fewer laptops and desktops move across the checkout counter, finding alternative profit centers becomes essential. The zero-inventory ad revenue generated by the media network provides a necessary financial hedge against these cyclical hardware headwinds. Navigating these economic conditions requires a leadership team that understands the interplay between physical merchandise and digital monetization.
Static on the Screen: Decoding the Valuation Disconnect
Despite improving fundamentals and the media network catalyst, Wall Street remains hesitant. The current analyst consensus maintains a Hold rating, with an average price target sitting near $85.40. This implies downside from recent trading levels, suggesting the market has not fully priced in the margin-expansion potential of the Amazon partnership.
Internal conviction also paints a cautious picture. Chairman Richard Schulze sold about 300,000 shares in mid-September, bringing his total sales to 800,000 shares sold since June. This heavy insider sales volume has pushed aggregate insider trading sentiment firmly into bearish territory. Heavy insider selling near a 52-week high often signals that management sees limited near-term upside, directly challenging the bullish thesis.
The underlying valuation offers a noticeable margin of safety for patient capital. Best Buy trades at a forward price-to-earnings ratio of roughly 13.31, offering a value-oriented entry point for a retailer generating an efficient 48.14% return on equity. Investors are also compensated while they wait for the media network thesis to play out, supported by a reliable 4.21% dividend yield with a 22-year track record of increases.
Why Value Investors Should Keep Watching
The transition from a pure electronics retailer to a hybrid media platform requires careful execution. The integration of Amazon’s Fire TV ecosystem provides a clear path for Best Buy to extract software-like margins from physical hardware sales.
While insider selling and cautious analyst targets present valid near-term risks, the core business is stabilizing, and the ad revenue is approaching a significant milestone. Value-focused investors might monitor the stock as the November leadership transition approaches, watching whether growing digital ad cash flows begin to force upward revisions in earnings models.
The article "Best Buy Is Turning Amazon Fire TV Into a New Advertising Opportunity" first appeared on MarketBeat.