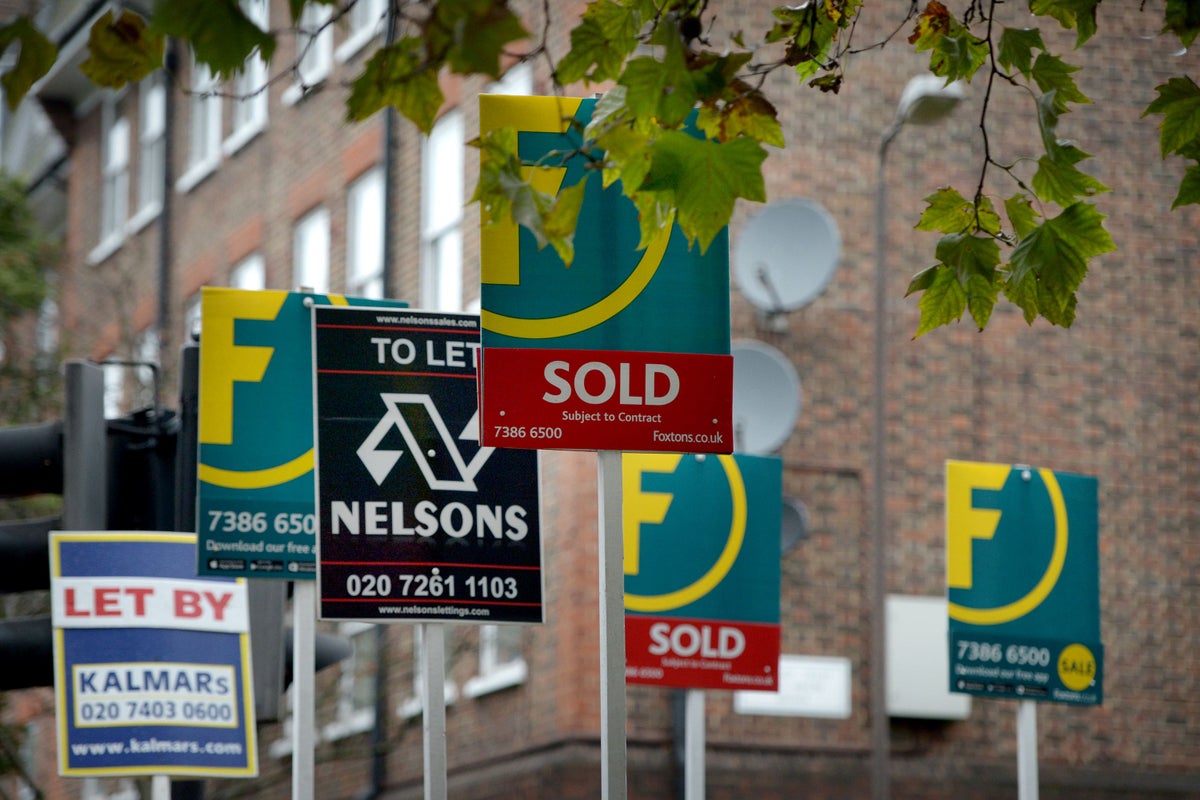
The annual rate of growth in UK house prices halved to 0.8% in September, from 1.6% in August, according to an index.
The average property value fell by 0.2% month on month in September, following a 0.2% increase in August, Nationwide Building Society said.
Across the UK, the average house price in September was £274,251.
Robert Gardner, Nationwide’s chief economist, said: “September saw UK annual house price growth halve to 0.8%, the weakest rate of growth since December 2025.”
He added: “Market activity and house prices have remained subdued in recent months, in part reflecting the uncertain economic backdrop.
“Geopolitical tensions remain high, with the conflict in the Middle East exerting upward pressure on energy prices, fanning inflation concerns.
“This in turn has led to mounting financial market expectations of (Bank of England base rate) increases, which has maintained upward pressure on the market interest rates which underpin mortgage pricing.”
Mr Gardner said that underlying housing affordability is improving, “as house price growth has been well below earnings growth for some time”.
He said: “These gains have been only partially offset by higher mortgage rates.
“This suggests that activity should regain momentum in the quarters ahead providing the energy shock fades and confidence returns – especially if market interest rates fall back to pre-conflict levels.”
The news comes as overall growth in UK bank lending to households and businesses is set to slow to a three-year low in 2027, as greater caution and economic pressures weaken borrowing demand, according to a forecast.
The EY UK Bank Lending Outlook predicts a marked slowdown in growth in total bank lending, from 3.6% in 2025 to 2.9% this year, and then reaching a three-year low of 2.2% in 2027, before edging up to 2.4% in 2028.
The outlook highlighted tensions in the Middle East, with higher energy costs and weaker economic activity weighing on borrowing demand.
Mortgage lending remains comparatively resilient, according to EY, with growth expected to rise marginally from 3.0% in 2025 to 3.3% in 2026.
But rising unemployment, slower income growth and interest rates remaining higher for longer are then forecast to reduce growth to 2.2% in both 2027 and 2028.
Dan Cooper, EY UK and Ireland head of banking and capital markets, said: “Mortgage lending is expected to prove more resilient than other forms of borrowing this year – despite the challenging economic environment.
“Household incomes have risen faster than house prices in recent years, which has supported buyer affordability, and interest rate cuts in 2025 are still feeding through, leading to a short-term boost in growth.
“However, this is unlikely to continue for much longer. Rising unemployment and slower income growth are expected to weigh on housing demand over the coming years, resulting in slower, albeit still positive mortgage lending growth.”
He added: “Business investment, housing activity and consumer borrowing are all anticipated to remain subdued in the near term.
“Importantly though, write-off rates are expected to remain low and stable across all categories, suggesting slower demand rather than a deterioration in credit quality.
“The UK’s banks enter this period from a position of strength, having built robust capital positions, greater resilience, and disciplined risk management.
“This means they are well-placed to support customers while continuing to invest for the future, so they are ready to meet demand as the economy stabilises and borrowing appetite returns.”
Mortgage write-off rates have risen steadily since 2022 as households have moved from lower-rate fixed deals to higher monthly repayments, EY said.