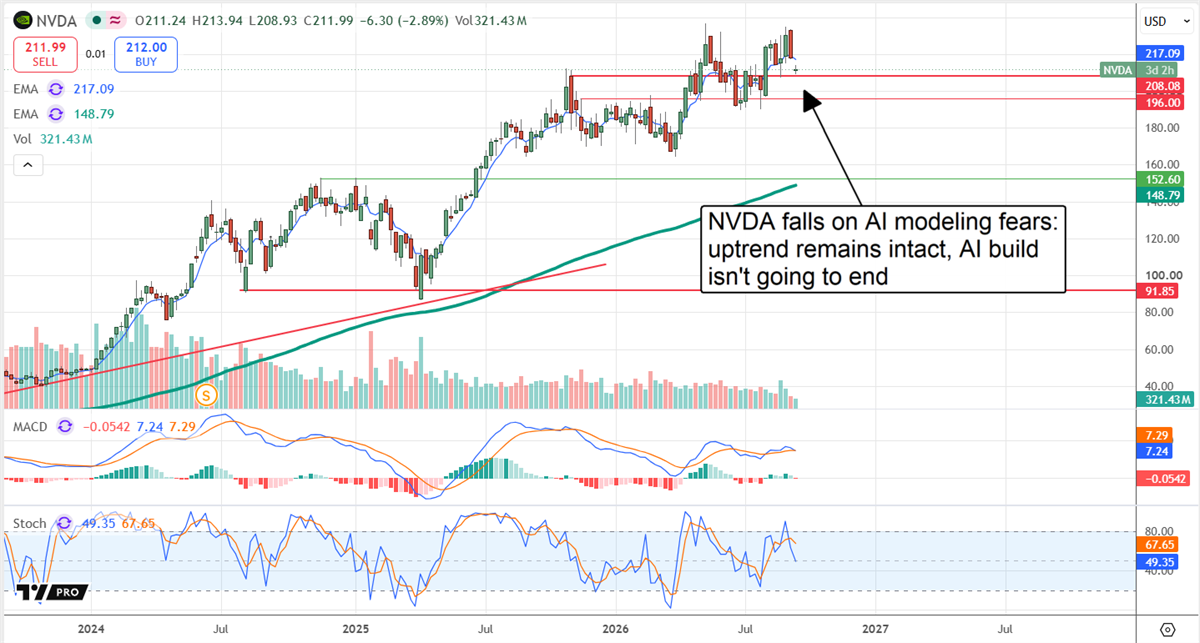
AI leaders shocked the world by calling for a slowdown in AI’s advancement and for regulation. The news triggered a sector-wide drawdown, raising the risk of a deeper correction, but short sellers shouldn’t get their hopes up.
As scary as it may seem to AI investors, the slowdown in AI’s advancement isn't likely to affect the infrastructure buildout. For the market, more advanced AI models don't matter, since labs such as OpenAI and Anthropic already have highly capable (and potentially dangerous) versions; what matters is the infrastructure to deploy utilitarian AI across the enterprise landscape.
The market gets this wrong: safety and capacity aren’t the same thing. AI demand is not collapsing. Q2 results from NVIDIA (NASDAQ: NVDA) to Salesforce (NYSE: CRM), and nearly every AI-capable company in between, point to accelerating infrastructure demand. In this scenario, September price weakness is a good time to buy these stocks, as catalysts for their price action lie ahead.
The AI Boom Hasn’t Really Boomed (Yet)
Key details for investors to watch include backlogs, utilization rates, persistent pricing power, and the potential for capital expenditure (CapEx) relief. Q2 backlogs expanded at a historic pace, increasing by triple digits at Alphabet (NASDAQ: GOOGL), Dell (NYSE: DELL), and Super Micro Computer (NASDAQ: SMCI).
Critical players like Oracle (NASDAQ: ORCL), now ubiquitous across cloud instances regardless of hyperscaler, saw backlogs grow to more than $650 billion, while neoclouds like Nebius (NASDAQ: NBIS) reported far larger increases, with Nebius's backlog up 4x. CapEx plans among the leading hyperscalers total over $700 billion, underscoring the spend.
Utilization rates matter because they run near 100%, even for older legacy technology. The takeaway is that technology transitions from model training and advanced computing to inference as it ages out, providing a long runway for cash flow and capitalization. This is the foundational factor in NVIDIA’s ability to securitize its GPUs, enabling institutional investors such as retirement funds to invest in the cash flow.
The trigger for stock price gains will be the monetization of existing assets, which, coincidentally, aligns with profitability. Hyperscalers dialing back ultra-expensive frontier modeling will suddenly free up cash flow, removing the primary hurdle for stock prices today. The upfront cost of AI infrastructure is debilitating, impairing cash flow and profitability for most AI-related companies.
AI CapEx Fears Haven’t Derailed the Infrastructure Trade
Q2 reporting was spectacular, with results outpacing consensus estimates across the board by a significant margin.
However, analysts were skeptical of CapEx plans and a rapidly differentiating market, causing stocks to move in different directions. As it stands, AI infrastructure names, including NVIDIA, remain the big winners, as they are the focus of current spending.
Wedbush pointed out that the buildout is moving slightly faster than adoption, which is a root cause of concern. The takeaway for investors is that slowing AI model spend not only improves profitability but also frees up cash to meet existing CapEx plans.
Wall Street Keeps Raising the Bar for NVIDIA
NVIDIA is the most important stock for AI today, providing the core infrastructure and software that enable it, and its analyst trends are as strong as they could be.
MarketBeat shows coverage increasing month over month and a firm Buy consensus rating with nearly 97% Buy-side bias. Currently, the company carries no Sell ratings, and the consensus price target implies more than 50% upside.
The price target trend is significant, as August and September revisions have pushed the consensus higher.
The high-end range pegs this stock at $515, more than 100% upside, and even that forecast is likely to be low.
Valuation metrics suggest NVIDIA is 50% undervalued today simply based on its price-to-earnings (P/E) multiple, trading in the low 20s versus the historical mid-30s.
Longer-term, this stock is trading at pennies on the dollar, approximately 5x the five-year outlook, suggesting it can rise by 400% to 600% over the coming years.
The Inference Boom Is About to Happen
Inference is accelerating today, heading toward a boom that Advanced Micro Devices (NASDAQ: AMD) will unleash.
Its Helios racks provide hyperscalers with numerous benefits, including inference speed, cost, and profitability. Investors need to remember that model training is the “upfront” cost of AI, while inference is the back-end monetization. With this in mind, we can expect the data center buildout to continue at full steam, if not accelerate, over the coming quarters as AI inference ramps to critical mass.
The biggest risks for AI are bottlenecks in GPU and memory supply, as well as in energy and water. These factors are slowing the build, but also provide opportunities. Companies such as Vertiv (NYSE: VRT), Bloom Energy (NASDAQ: BE), and AirJoule (NASDAQ: AIRJ) provide hurdle-jumping technologies that enable data centers to exist and operate with minimal impact on locals.
Among the risks are the upcoming elections, which are likely to be a referendum on AI. The outcome will have far-reaching ramifications but is unlikely to end the buildout. Potentially, established AI companies could benefit from increased regulatory oversight, as it could widen their competitive moats—making it harder for new AI labs to start, limiting the risk of disruption. If increased regulations don't come about, these companies will have free rein to continue building their city-sized supercomputers.
The article "AI Panic Hit Tech Stocks—But NVIDIA’s Growth Engine Is Intact" first appeared on MarketBeat.