
Meta’s (META) latest artificial intelligence (AI) experiment is moving the chatbot conversations into a very different territory. Launched recently, Muse is the company’s personal AI agent designed to work in the background and handle tasks for users, rather than simply answer questions. From browsing the web and shopping to booking travel, managing calendars, and handling payments, Muse is built around the idea of AI taking action on a user’s behalf. It is also available through Meta-owned WhatsApp, giving it another massive channel for adoption.
That shift has caught Wall Street’s attention. Morgan Stanley’s analyst Elizabeth Porter believes the growing popularity of consumer AI assistants could create a new wave of demand for the software and communications infrastructure behind them. In her view, Twilio (TWLO) could benefit as AI agents generate more calls, messages, and other interactions, while Wix.com (WIX) could gain as businesses increasingly use their online infrastructure to support transactions and AI-driven customer engagement.
That puts TWLO and WIX among the communication software names Morgan Stanley sees as best exposed to the potential growth around Muse. With both companies positioned to benefit in different ways as AI agents gain traction, investors could buy these two stocks following Porter’s bullish note.
Stock #1: Twilio (TWLO)
Incorporated in 2008 and headquartered in San Francisco, Twilio has grown from a cloud communications company into a broader customer engagement platform. Its APIs and software help businesses handle messaging, voice, email, authentication, and other digital interactions, while its data and AI capabilities are increasingly becoming part of the mix. Today, Twilio serves hundreds of thousands of businesses across more than 180 countries and has a market capitalization of about $44.6 billion.
That broader AI opportunity is also showing up in the stock. TWLO has gained about 176% over the past 52 weeks and 100% on a year-to-date (YTD) basis, climbing to a fresh 52-week high of $296.37 on Sept. 23. The latest rally has come as investors increasingly focus on Twilio’s role in AI-driven communications, with recent analyst price-target increases adding to the momentum. Expectations around Meta’s rollout of its AI assistant “Muse” have also helped fuel interest in the stock.
But after such a sharp run, the chart is flashing a different signal. Twilio’s 14-day RSI has moved into overbought territory, suggesting the stock could see some cooling after its recent surge. And today's almost 7% drop in morning trading seems to indicate that cooling may already be beginning.
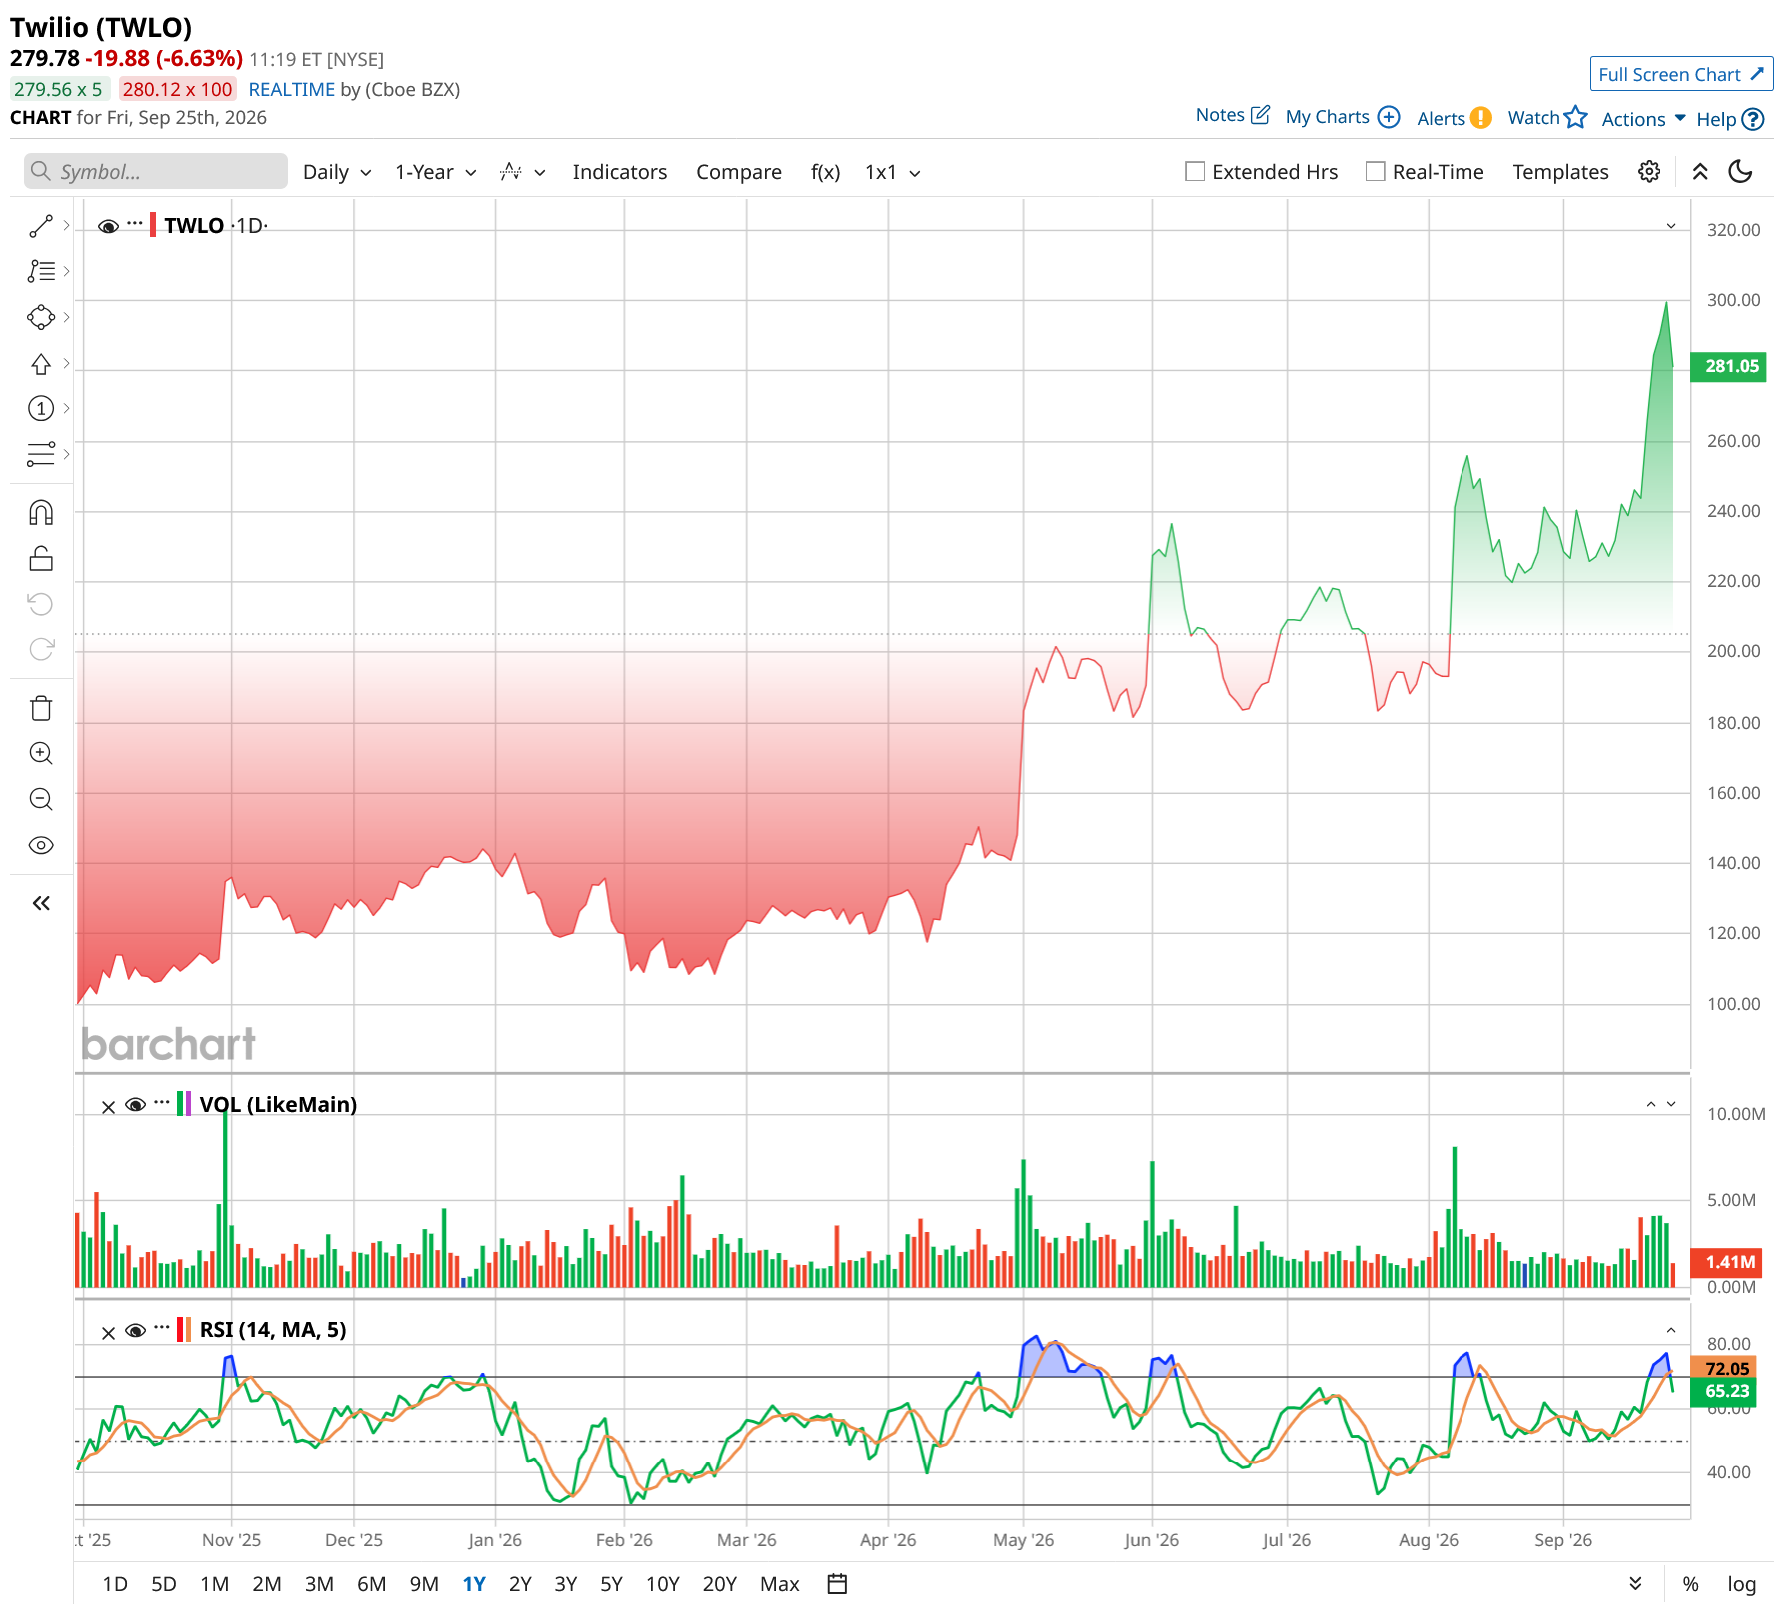
TWLO’s strong run has also pushed its valuation higher, with the stock trading at about 49 times forward earnings and 7.44 times sales, both at a premium to the sector averages.
Twilio’s second-quarter results showed a business gaining momentum on both the top and bottom lines. Revenue reached $1.5 billion, up 22% year-over-year (YoY), while organic growth rose to 17%, suggesting the improvement was not driven only by acquisitions or other factors. Profitability also moved higher, with non-GAAP operating income rising 29% YoY to $284.6 million. Non-GAAP EPS climbed 23.5% to $1.47, beating analysts’ expectations.
The company also saw customers deepen their relationship with the platform. Twilio’s Dollar-Based Net Expansion Rate rose to 116% from 108% a year earlier, meaning existing customers, on average, were spending more on its services.
Looking ahead, management expects third-quarter revenue between $1.505 billion and $1.515 billion, representing reported growth of 16% to 16.5% and organic growth of 11% to 12%. Non-GAAP operating income is expected to land between $285 million and $295 million, with EPS projected at $1.42 to $1.47.
The company also raised its full-year 2026 outlook. Reported revenue growth is now expected at 18% to 18.5%, while organic growth is projected at 13% to 13.5%, giving investors a stronger growth picture heading into the second half of the year.
The consensus EPS estimate for fiscal 2026 is $3.12, down 32% YoY, but it is anticipated to rise 27.2% to $3.97 in the next fiscal year.
Analysts see AI opening a new door for Twilio, but the opportunity may be less about AI assistants themselves and more about what those assistants need to do. Morgan Stanley analyst Elizabeth Porter says Twilio could benefit when an AI agent places a call, sends a message, or helps a business handle an incoming interaction. Its software tools, including Conversation Relay, could also help Twilio generate more revenue from each interaction.
That view is reflected in recent price-target moves. TD Cowen raised its target on Twilio to $300 from $260, while keeping a “Buy” rating, pointing to consumer AI assistants as a potential new source of demand. The brokerage firm expects AI agents to increase communication volumes across Twilio’s core SMS, voice, and WhatsApp services while also creating opportunities for identity and security products.
Rosenblatt also lifted its target, moving it to $290 from $275 while maintaining a “Buy” rating. The brokerage firm sees voice becoming increasingly software-driven and believes AI-generated communications could add to, rather than replace, existing demand. Rosenblatt also highlighted consumer AI agents as a potential new layer for communications and identity, while Twilio’s growing software offerings could help it earn more from customers beyond basic messaging and connectivity.
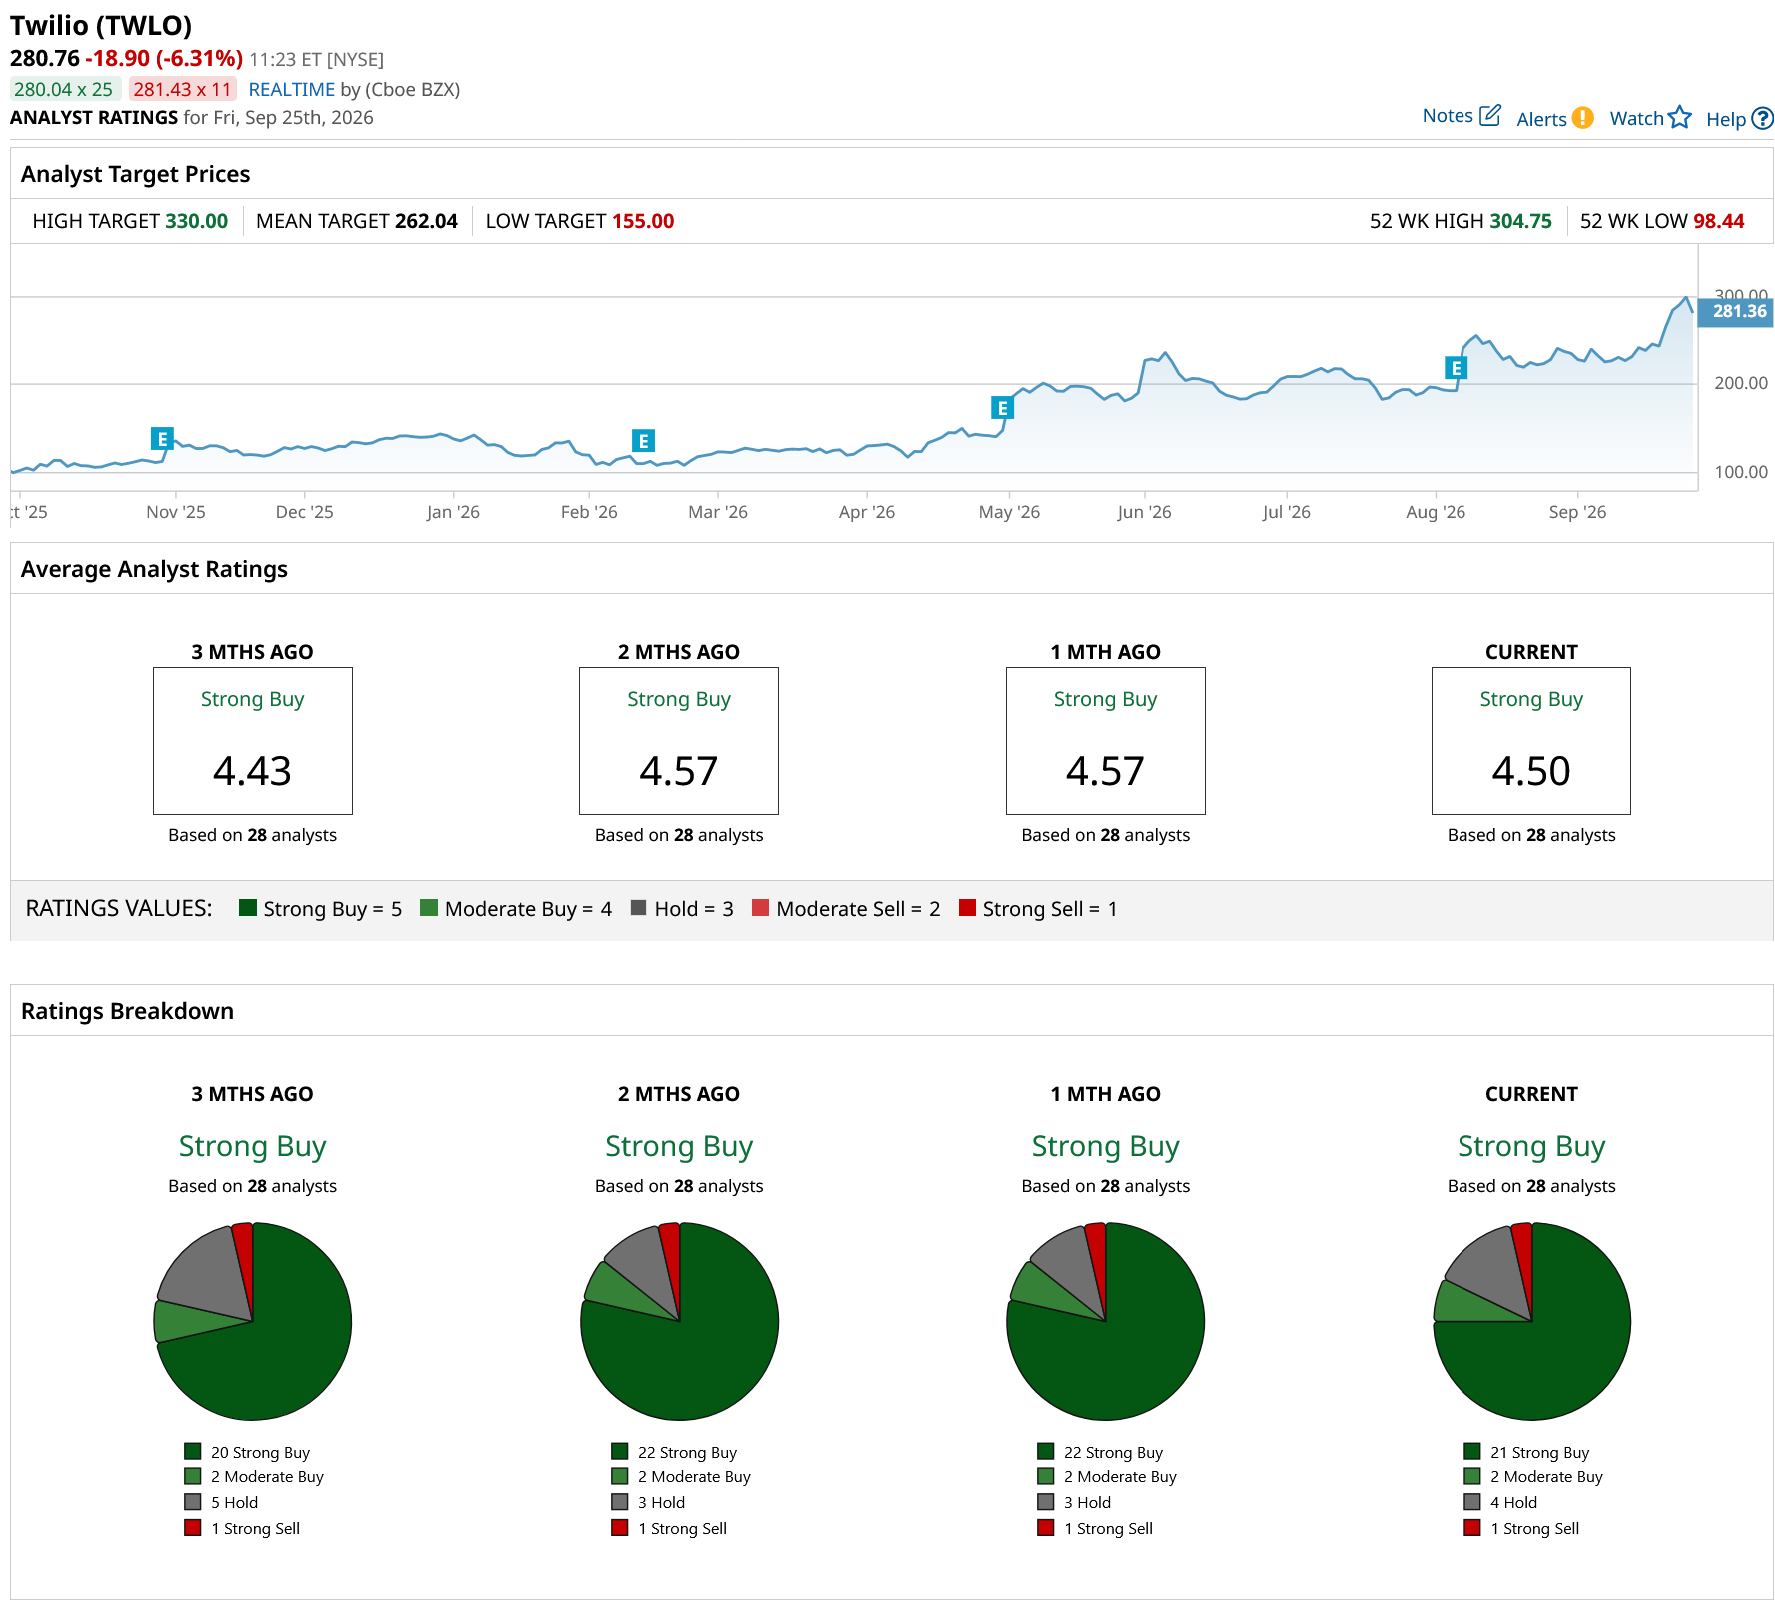
The stock has a consensus “Strong Buy” rating overall. Of 28 analysts covering the stock, 21 recommend a “Strong Buy,” two advise a “Moderate Buy,” four suggest a “Hold,” and one has a “Strong Sell” rating.
The stock currently trades above the mean price target of $262.04. The Street-high target of $330 suggests that TWLO stock could rise as much as 17% from here.
Stock #2: Wix.com (WIX)
Wix.com is a Software-as-a-Service (SaaS) company that helps people and businesses build, manage, and grow their presence online. Founded in 2006 and headquartered in Tel Aviv, Israel, Wix offers website creation and design tools, hosting, domain registration, SEO and marketing features, business solutions, and AI-powered website builders. Its platform serves everyone from individual creators and entrepreneurs to small businesses and larger enterprises.
Over time, Wix has grown from a simple website builder into a broader digital platform, combining commerce and business tools with enterprise-grade infrastructure, security, and performance. Today, more than 200 million users worldwide rely on Wix to create and manage their digital presence. Its market capitalization currently stands at $4.5 billion.
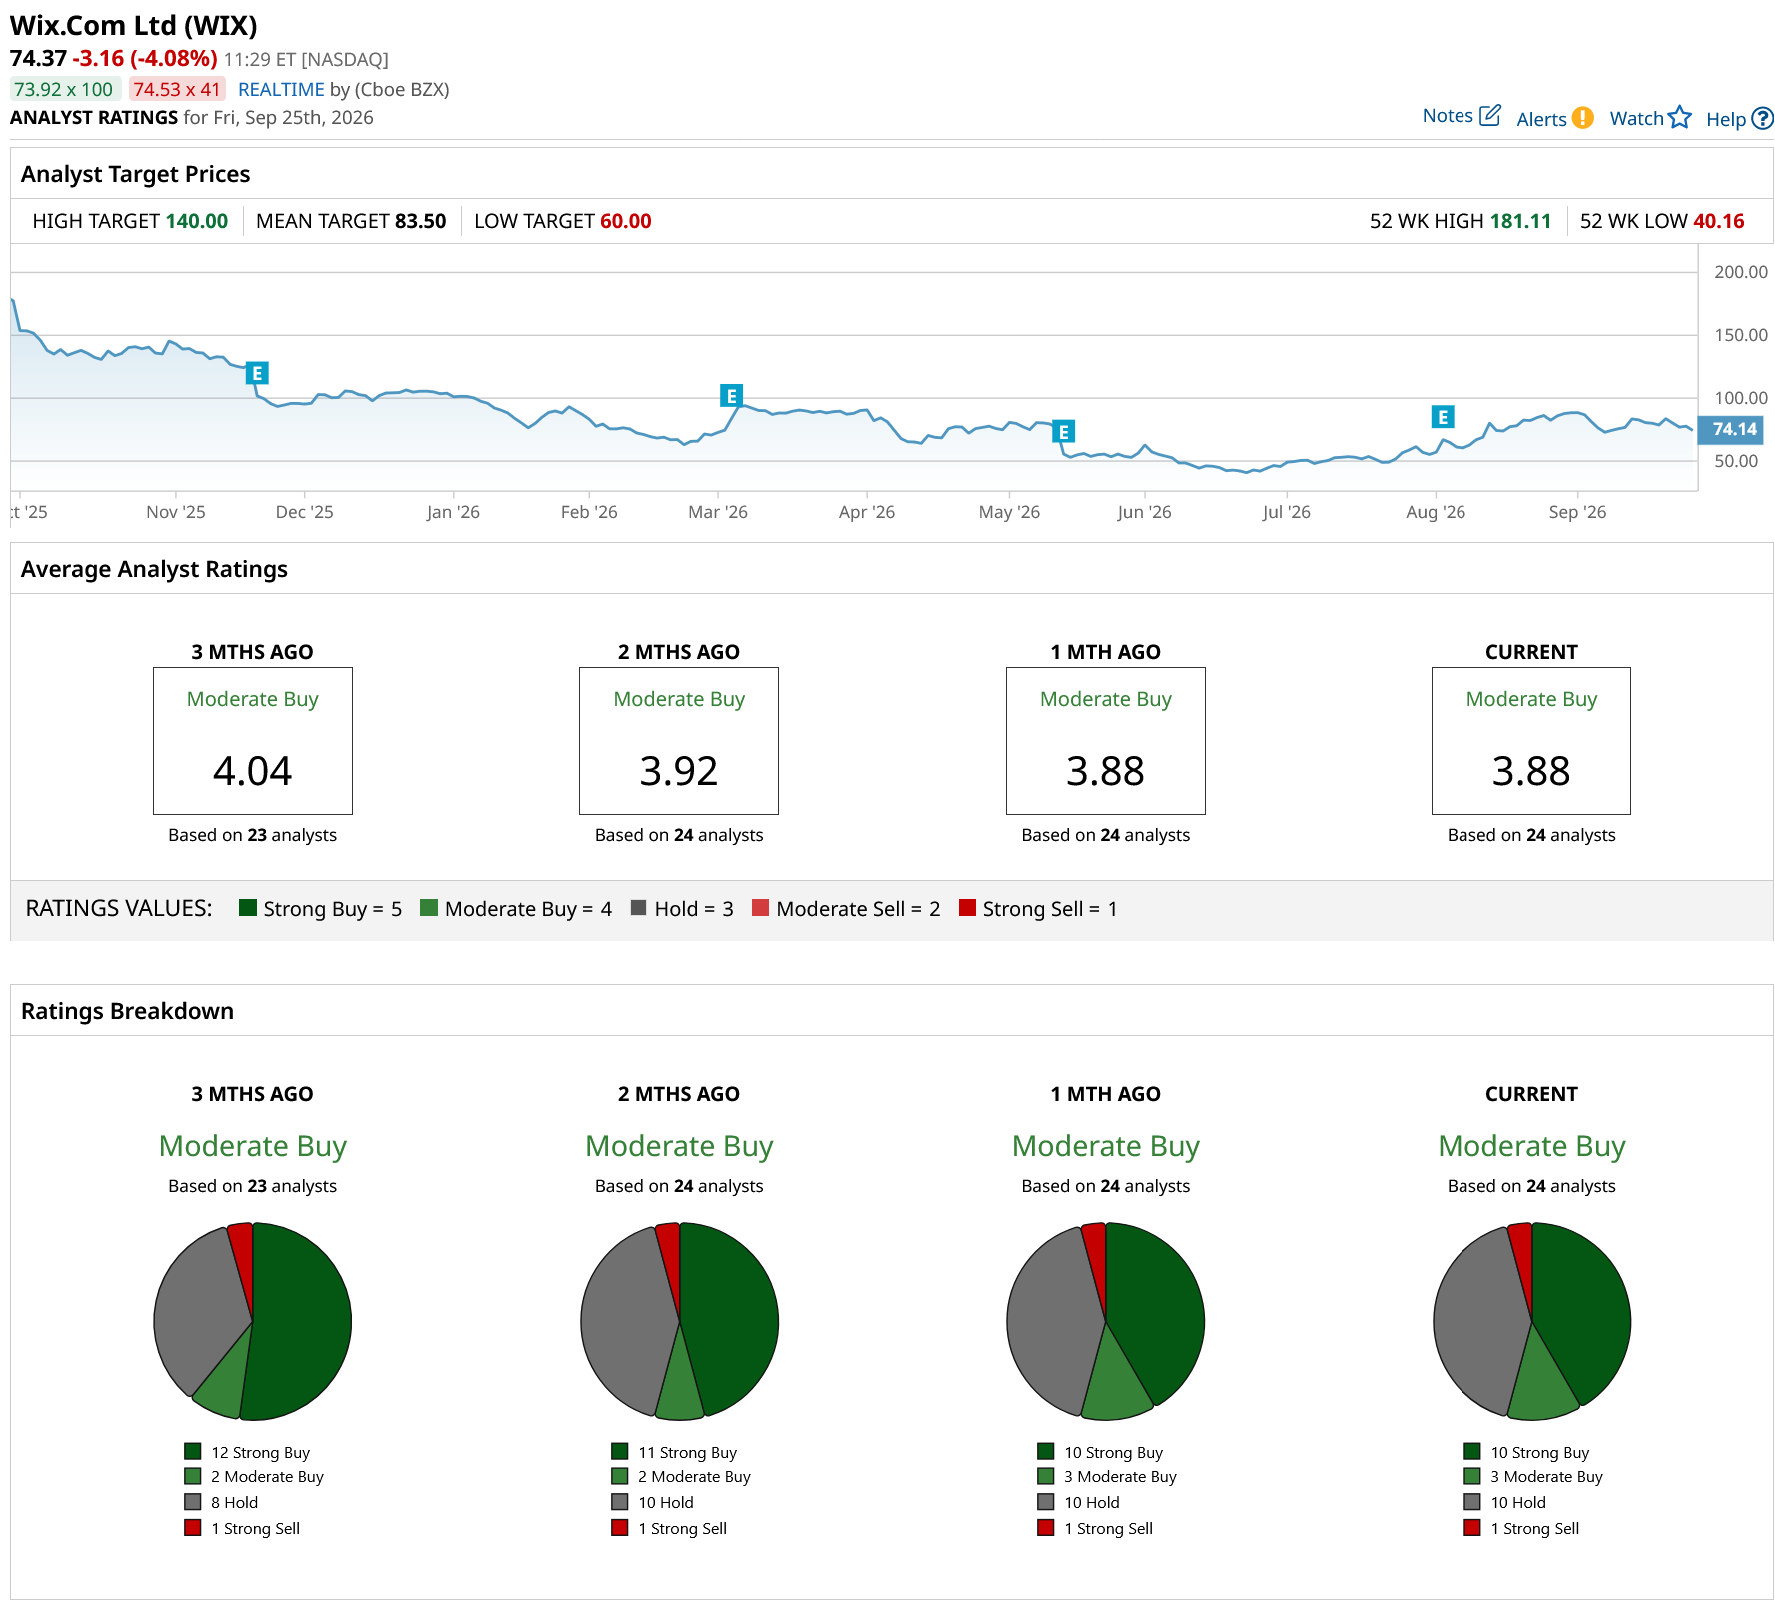
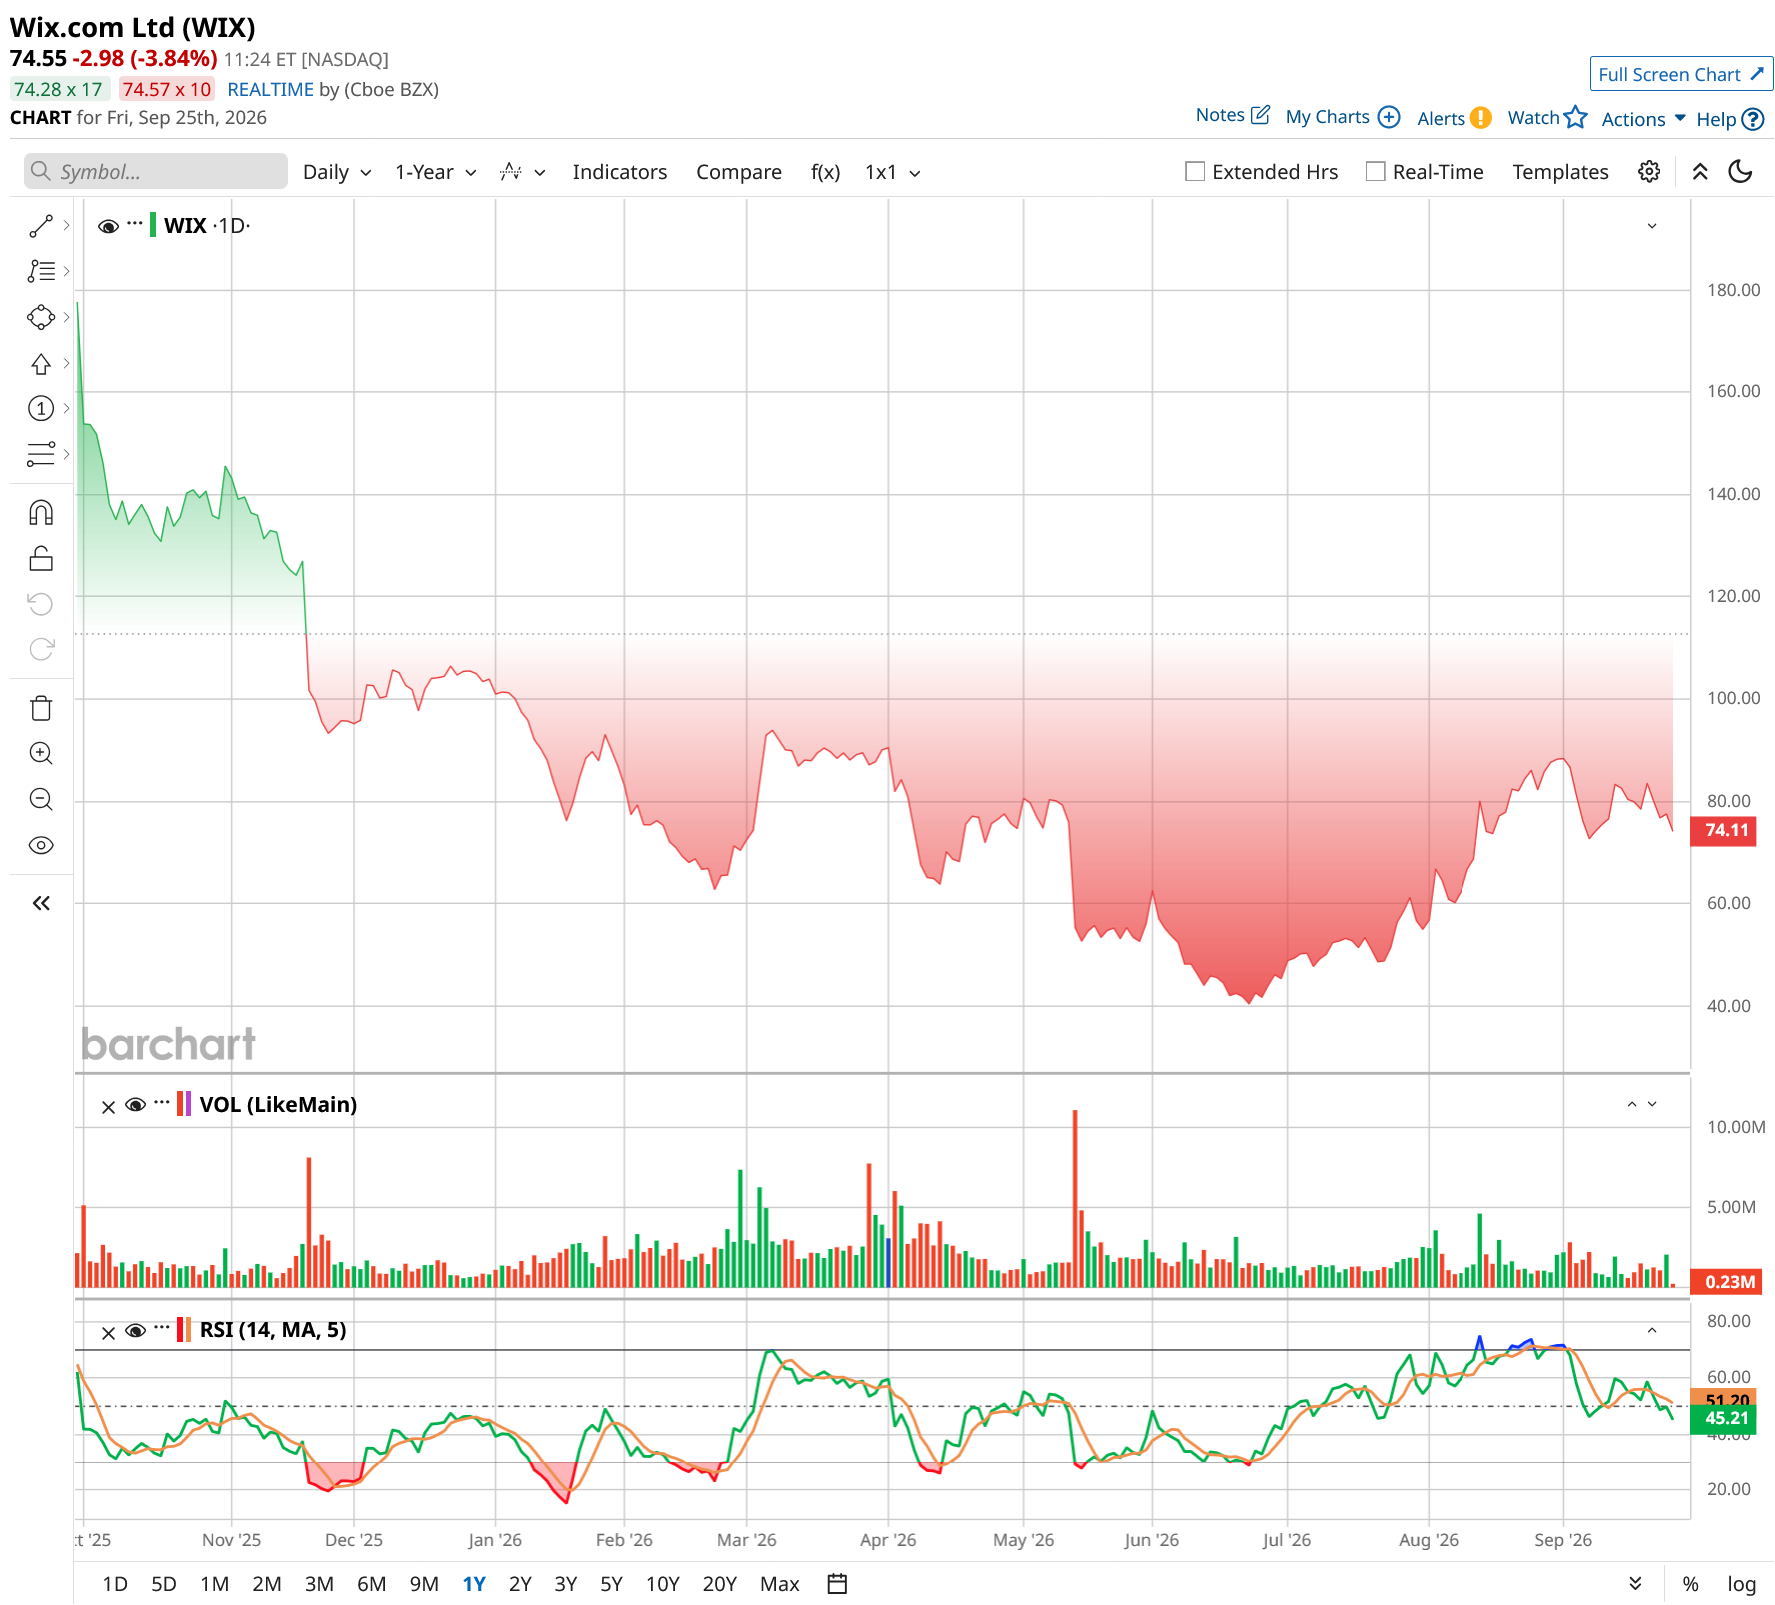
The stock chart tells a much different story. Over the past 52 weeks, WIX has lost over 57%, while the decline stands at 29% on a YTD basis. Investors have been uneasy about whether AI could disrupt Wix’s traditional website-building business, while a first-quarter earnings miss, higher AI-related costs, and weaker-than-expected performance in its Partners segment added more pressure.
The selling pushed WIX down to $40.16 in June, but that low eventually became a turning point. Since then, the stock has rebounded a striking 84%, including a 77% gain over the past three months. Even after that comeback, however, WIX stock remains well below its 52-week high of $181.11.
Technically, the 14-day RSI is around 47, sitting in neutral territory and suggesting the stock isn’t showing either overbought or oversold conditions right now.
Valuation-wise, WIX does not look too pricey. The stock trades at 16.53 times forward adjusted earnings and 1.42 times forward sales, both below sector averages and its own historical medians.
Wix’s second-quarter fiscal 2026 results, reported on Aug. 4, show a business that is still growing at a healthy pace, even as the company spends heavily to build out its AI ambitions. Revenue climbed 15% YoY to $563.1 million, helped by strong performance from Base44 and continued growth in the core Wix business. Non-GAAP EPS came in at $1.39, ahead of Wall Street’s expectations, although it slipped 39% annually.
The pressure was more visible in margins. Non-GAAP gross margin fell to 67% from 70%, largely because Wix continued investing in Base44 while also absorbing higher AI computing costs. Sales and marketing spending added to the pressure, leaving non-GAAP operating income at 12% of revenue.
Still, there was plenty to like underneath the headline numbers. Q2 bookings increased 12% to $569 million, with Creative Subscriptions bookings up 11% and Business Solutions bookings rising 13%. Total annual recurring revenue reached $1.963 billion, up 15% YoY.
A big part of Wix’s next chapter is Base44. The company launched Base 1, its own large language model (LLM) designed for software creation. Management expects greater control over AI inference to accelerate product development, reduce dependence on outside vendors, and eventually lower costs.
Base44’s non-GAAP gross margin is expected to reach roughly 60% in the second half of 2026, compared with nearly zero at the start of the year. AI costs are projected at 30% to 40% of Base44 bookings, while the resulting savings are expected to add about two percentage points to Wix’s consolidated non-GAAP gross margin in the second half. Wix also expanded AI Workflows and enterprise governance tools, while Wix Headless added connections to Claude Code, Codex, and Base44.
Looking ahead, management expects 2026 revenue growth in the low-to-mid teens, bookings growth in the low teens, and free cash flow margin, excluding acquisition and restructuring costs, in the high teens. For Q3, revenue is expected to grow at a low-double-digit rate year over year.
Analysts monitoring the company anticipate EPS for fiscal 2026 coming in at $0.24, narrowing by 92.9% YoY. But they are looking for a sharp rebound in fiscal 2027, when EPS is projected to jump 800% annually to $2.16.
Analysts also see an interesting twist in Wix’s AI strategy. Morgan Stanley analyst Elizabeth Porter argues that AI agents could actually expand the market for website software, even if people spend less time browsing traditional websites. Instead of simply helping businesses present information online, Wix could help them handle bookings, payments, customer chats, and AI-driven discovery. There is still a risk from AI-native website builders, Porter noted, but less human browsing does not necessarily mean less demand for the software businesses use to operate online.
Overall, Wall Street’s view on WIX is currently based on coverage from 24 analysts, with the stock carrying a consensus “Moderate Buy” rating. Out of those analysts, 10 have a “Strong Buy” rating, three have a “Moderate Buy” rating, 10 are playing it safe with a “Hold” rating, and just one suggests a “Strong Sell.”
The mean price target of $83.50 suggests WIX stock has a rebound potential of 12%, while the Street-high price target of $140 reflects that the stock could surge as much as 87% from here.