Williams-Sonoma, Inc. (WSM) is a global leader in home furnishings and décor, bringing together a portfolio of well-known brands including Williams Sonoma, Pottery Barn, Pottery Barn Kids, Pottery Barn Teen, West Elm, Williams Sonoma Home, Rejuvenation, Mark & Graham, GreenRow and Dormify. The company reaches customers through its e-commerce platforms, retail stores, catalogs and business-to-business channels, with its brands covering everything from furniture and home décor to kitchenware and gifts.
Headquartered in San Francisco, California, Williams-Sonoma has built a broad international presence. It operates across the U.S., Puerto Rico, Canada, Australia and the U.K., while franchise partners extend its brands into markets including Mexico, South Korea, India and the Philippines. At its core, Williams-Sonoma has turned shopping for the home into a multi-brand, design-focused experience, combining its strong physical-store presence with a digital-first approach to reach customers wherever they shop.
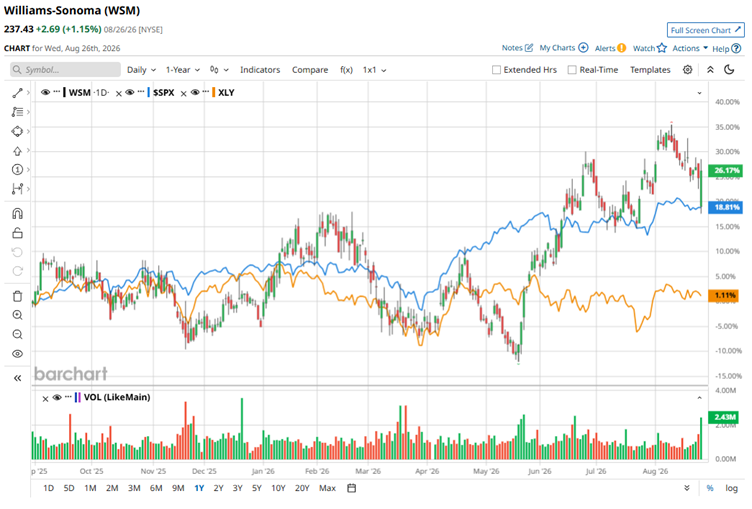
With a market capitalization of roughly $27.96 billion, Williams-Sonoma has been delivering a strong performance on Wall Street. The stock has climbed about 20% over the past year, with its momentum accelerating in 2026 as shares have surged 33% year to date (YTD). That performance looks even more impressive compared with the broader market. The S&P 500 Index ($SPX) has gained about 18.7% over the past year and 12.1% YTD, meaning Williams-Sonoma has comfortably outpaced the benchmark on both fronts.
The stock has also outperformed its consumer-discretionary peers. The State Street Consumer Discretionary Select Sector SPDR ETF (XLY) has posted only a marginal gain over the past year and is down about 1.9% in 2026.
Williams-Sonoma’s strong stock performance so far in 2026 is backed by a business that continues to hold its own in a tough home furnishings market. And its latest earnings report supports that view. The high-end retailer, which owns popular brands such as Pottery Barn and West Elm, delivered a strong fiscal 2026 second-quarter performance on August 26. The company’s comparable sales jumped 6.2%, comfortably outperforming its peers and showing that customers are still spending across its portfolio of brands.
Overall revenue also rose 6.7% to $1.96 billion, beating Wall Street’s estimate of $1.93 billion. Margins provided another boost. Williams-Sonoma benefited from IEEPA tariff refunds, helping its gross margin expand sharply from 47.1% to 51.6%. Even when excluding the benefit of those refunds, the company still posted healthy earnings growth. Adjusted EPS climbed 5% to $2.10, edging past analysts’ consensus estimate of $2.07.
Looking ahead, Wall Street expects WSM’s earnings momentum to continue. For the current fiscal year ending in January 2027, analysts project EPS of $9.38, representing a 6.1% increase year over year. WSM also has a solid track record when it comes to delivering beyond expectations. The company has beaten consensus earnings estimates in each of the past four quarters.
Wall Street’s confidence in Williams-Sonoma remains intact. The stock currently carries a consensus “Moderate Buy” rating, with nine of 21 analysts calling it a “Strong Buy,” one giving it a “Moderate Buy,” and 11 recommending a “Hold.” The sentiment has also edged slightly higher in recent months. Two months ago, WSM had eight “Strong Buy” ratings compared with nine today.
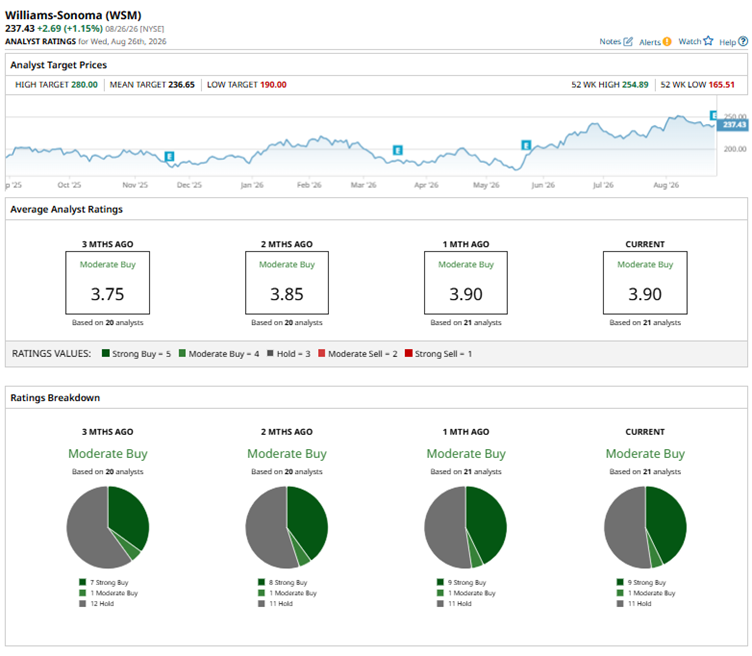
Following Williams-Sonoma’s strong Q2 earnings report, Wall Street is becoming increasingly upbeat on the stock. Most recently, Telsey raised its price target to $260 from $255 while maintaining an “Outperform” rating, signaling continued confidence in the retailer’s growth prospects. Interestingly, Williams-Sonoma shares have already surpassed the average analyst target of $236.65. But the bulls aren’t backing down. The Street-high target of $280 points to another potential 18% upside from current levels, suggesting analysts believe the stock may still have room to run.