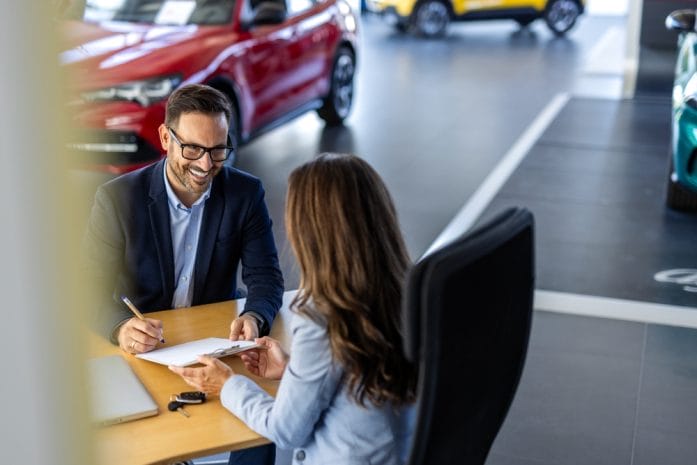
You’ve seen those shiny lease deals at the dealership: low monthly payments, new‑car smell, and no old clunker in your driveway. For middle‑income drivers juggling groceries, childcare, and rent or mortgage payments, leasing a car can feel like a practical way to get reliable wheels without breaking the bank. But the surface appeal of leasing a car hides a financial truth that many people only realize after year two — and often after a stack of monthly payments that never stop.
When you dig into the real costs — fees, restrictions, lack of equity, insurance premiums, and depreciation — the math frequently tells a story very different from what that enticing monthly payment suggested.