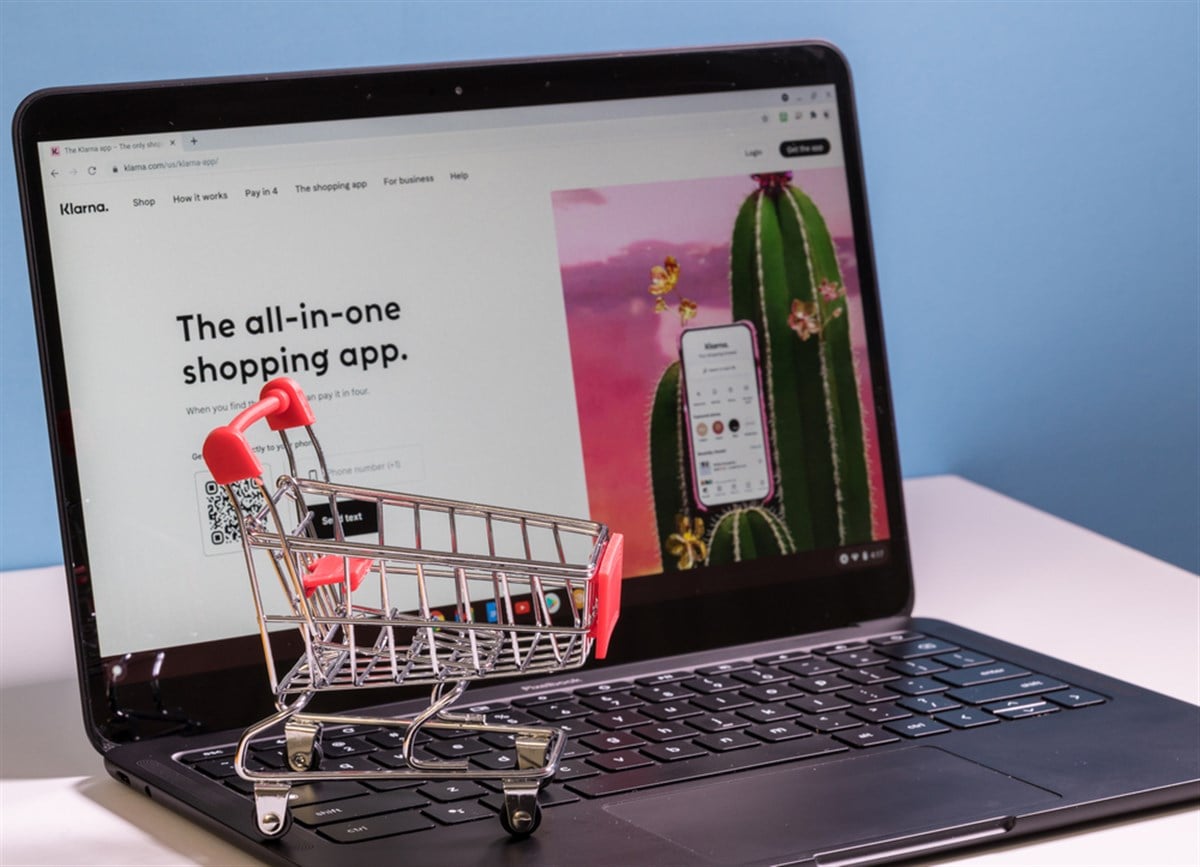
Buy now, pay later (BNPL) financial solutions company Klarna Group (NYSE: KLAR) has only been trading publicly since early September 2025, and shares are still finding their footing amid post-IPO volatility. There's an argument to be made that investors have an opportunity since Klarna has fallen below its IPO price of $40 after shares initially surged to about $52 following the IPO. In the meantime, analysts from Wall Street firms, including Bank of America, JPMorgan, Wedbush, and others, have all initiated coverage with Buy or equivalent ratings, signaling optimism.
For everyday investors, it's key to assess Klarna's potential both within and beyond the growing BNPL industry. Indeed, analysts with a bullish perspective on KLAR shares may be looking ahead to the company's potential as a much broader financial services firm with—for now, at least—a compelling case for value-minded investors. A first hurdle for the company will be a return to its IPO price and beyond, and analysts see this as easily achievable based on a consensus price target of close to $50 per share.