Monetizing AI matters for many reasons, including recapturing hundreds of billions in infrastructure spending, advancing technology, and, of course, profits. The problem is that AI monetization is a tightrope walk between upfront costs, the need for research, and adoption, and adoption may be the greatest risk of all.
While the upfront research costs are enormous, they can be mitigated if users flock to the tech. The risk is driving usage too far, too fast, and eroding confidence in capacity and capabilities. Companies that monetize AI today share a few qualities, including a proven utility for their consumers and the ability to innovate in their respective arenas. More importantly, each has a moat to protect future cash flow.
No Company Monetizes AI Like NVIDIA
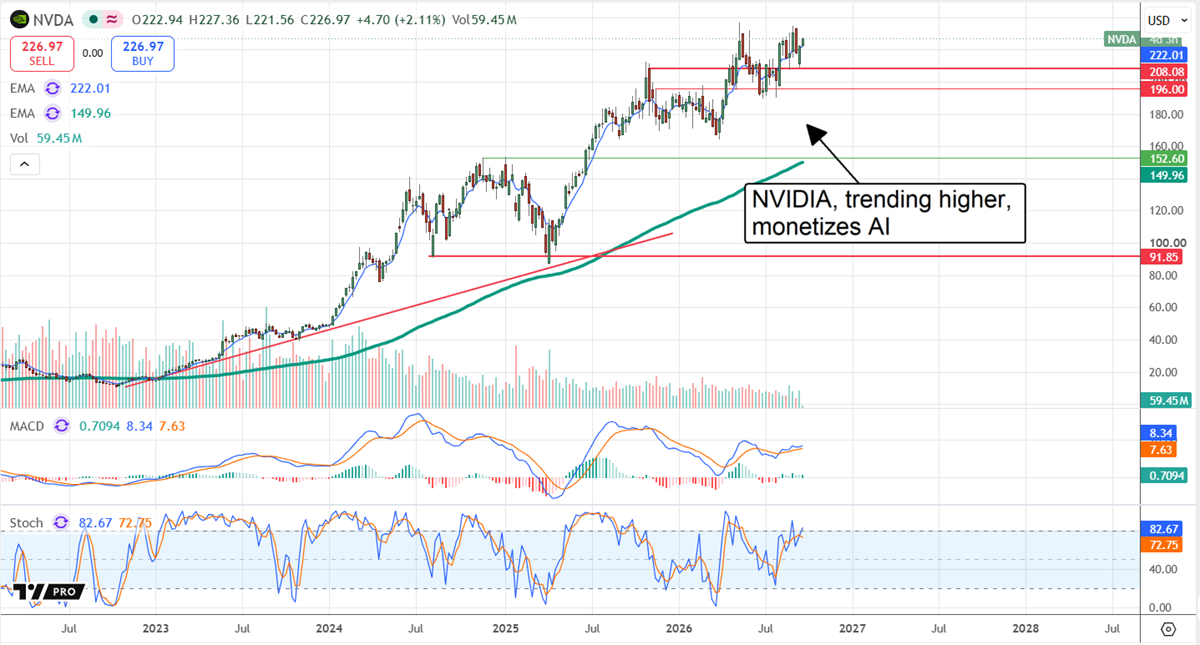
NVIDIA (NASDAQ: NVDA) is the hands-down winner when it comes to monetizing AI, providing both the AI hardware and the full-stack software to run it.
Hardware is the primary source, including the GPUs and the networking gear that connects them into clusters. It drives most revenue and earnings, but other avenues include royalties, revenue-sharing, and investing in future technology.
Royalties and revenue-sharing are linked to neoclouds and startups providing third-party services using NVIDIA technology; investment in future technology is circular, keeping NVIDIA ahead of the curve and GPU customers flush with capital.
The impact on NVIDIA’s cash flow is substantial and reflected in its balance sheet. The cash pile has grown over the past few years and remains high at more than $50.5 billion as of Q2 despite aggressive investments. This enables a token dividend, dividend increases, and share buybacks, which incrementally reduce the share count. Looking ahead, NVIDIA is likely to continue driving strong cash flow and sustain capital return over time.
Microsoft Leads With Embedded Services
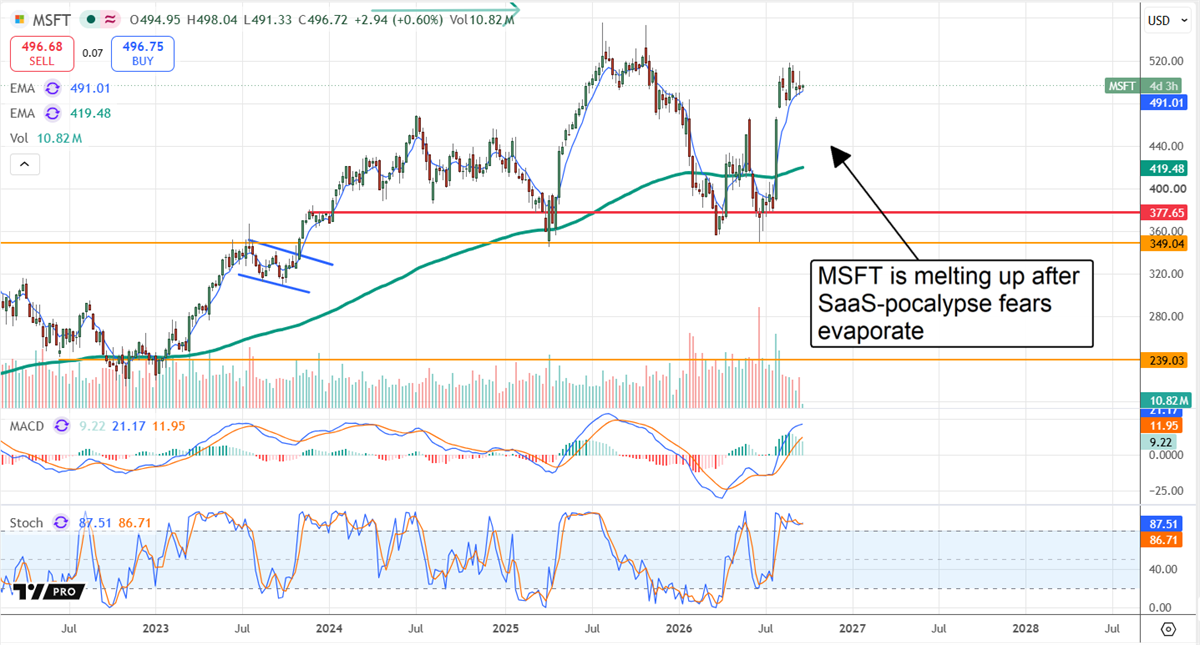
While it garners less of the spotlight than other AI companies, Microsoft (NASDAQ: MSFT) leads in monetizing applications.
It is embedding AI throughout its ecosystem, utilizing it as both an incentive and an upsell to drive business.
Recent earnings results included outperformance, acceleration in the cloud segments, and strength in Azure, the cloud infrastructure business, which saw revenue top $100 billion annually for the first time.
Looking ahead, analysts forecast that Microsoft will sustain modest single-digit growth and steadily widening margins over the next five to 10 years.
Like NVIDIA, Microsoft uses its cash flow to sustain financial health, reinvest in new technology, and return capital to shareholders. It also pays a token, albeit slightly larger, dividend while incrementally reducing its share count. Forty-seven analysts rate MSFT as a Moderate Buy with approximately 15% upside as of late September, compared to NVIDIA’s Buy rating and 40% upside potential.
Alphabet Taps Consumers to Monetize AI
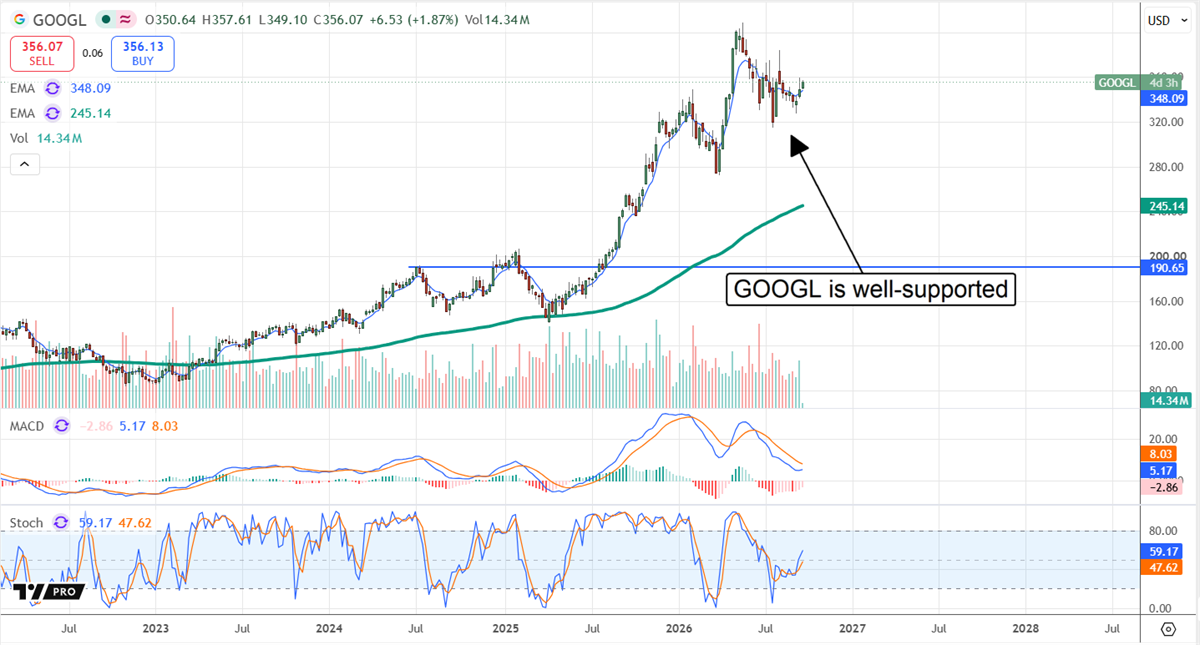
Alphabet (NASDAQ: GOOGL) monetizes AI in many ways, including with software, infrastructure, and services, but its real driver is the ad business.
AI increases clicks and quality, which, in turn, are reflected in the results. First-half 2026 results included the sixth and seventh quarters of sequential revenue growth acceleration, outperformance, and strong guidance, with Q2 revenue up nearly 25% year over year.
The Services segment, which accounts for about 90% of the business, underpins the results, supported by strength in Cloud. Google Cloud grew more than 80%, driven by strength across all business lines.
Alphabet, too, pays a token dividend and incrementally reduces its share count. A healthy balance sheet, low and manageable debt, and relatively unimpeded cash flow all offset its tepid return. These factors limit risk, provide some insulation amid higher interest rates, and give institutional investors a reason to buy.
Palantir Monetizes AI Safety
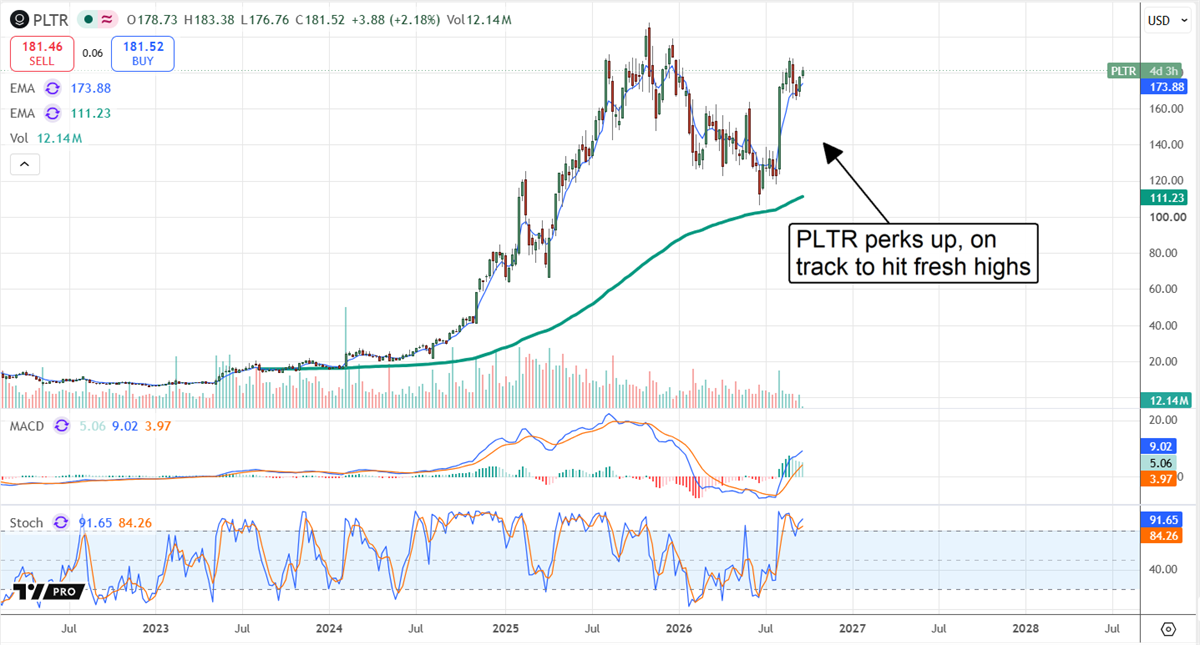
Palantir (NASDAQ: PLTR) monetizes AI in many ways, but first and foremost as an orchestration layer that lets businesses and governments access AI safely.
Its moat lies in compliance and its Ontology, the data layer beneath its AIP platform, which keeps data safe and secure while creating easy-to-follow roadmaps for AI. Not only do its products make AI safer, but they also make it more useful, which drives widespread adoption. Catalysts in 2026 include accelerating revenue growth and profitability.
Palantir is returning capital, but at an even slower pace, choosing to offset share-based compensation while preserving capital for growth initiatives. Palantir has an aggressive go-to-market strategy focused on onboarding clients and/or developing solutions before they commit, but it works, translating to long-term contracts and rapidly improving revenue visibility.
Analyst trends reflect the strengths, with coverage increasing, sentiment firming, and the price targets trending higher. The consensus price target forecasts only modest upside, but the trend matters, with the high-end price target implying fresh all-time highs. Institutions are buying and underpinning the stock price action.
The article "These 4 Companies Are Monetizing AI Today" first appeared on MarketBeat.