Today, I’m kicking off a new risk management series here at Barchart called “Look Both Ways Before You Cross Wall Street.”
Instead of hitting you with my topical trade ideas, I’ll get a little more nitty-gritty and into the weeds – explaining the what, why, how, and the real risk/reward math you need to know as a DIY manager of your own wealth.
Think of it as the best of my fund manager “Rob-servations” from decades in the industry… distilled for a retail audience trying to navigate the nuttiest market any of us has ever seen.
Let’s get started this week with a major soft spot in most investors’ education.
What Would You Do for 5% Yields?
Here’s the question I’ve been asking anyone who will listen – a group that includes my subscribers, family and friends.
If you knew you could make a 5% average annual return for the next 10 years with no risk of dollar loss, what percent of your portfolio would you invest in it?
How would you answer? My personal percentage is actually something more like “a majority of my liquid assets.” For others, it could be anywhere from zero to 100%.
Note that I did not say anything about what you’d be investing in. Only that:
- You make a 5% annual return.
- For 10 to 20 years.
- You will not lose dollars (inflation is not part of this exercise, and it IS just an exercise).
In fact, I’ll add another detail: during those years, you can take money out of the investment at any time you like, as often as you like. It might be worth more or less than you put in, but the closer you get to the end of the term, the higher the value is likely to be.
The 10-year U.S. Treasury yield was rightfully ignored for years. But a move from 0.5% during the pandemic of 2020 to 5% recently has forced many investors to sit up and take notice. I know I have.
Who Is This For?
Before we go any further, let's establish who needs to pay attention to this:
- The AI & High-Beta Equity Investor: You’ve had a massive run in mega-cap tech and stocks, but deep down you know you're playing with fire. And I don’t mean the “Financially Independent Retire Early” kind of FIRE, either. Just the opposite is more likely if you plan on the past being a prologue.
- The TLT Bagholder: You took a beating holding long-duration bond funds during the 2022 rate hikes, and learned that owning any one ETF is not “bond investing.” Yes, $50 billion worth of TLT chaser capital can be wrong. You now realize you need a smarter, hedged, or ultra-short yield strategy. Or maybe all three.
- The Bond Novice: You spent the last 15 years ignoring fixed income because 0% yields made bonds completely irrelevant to your wealth building.
- The Stock-Heavy Boomer: You are approaching or in retirement, sitting on a portfolio overwhelmingly weighted in equities, and facing historic market valuation shifts.
In short: this strategy is not for the folks who want to have fun with their wealth today, tomorrow, next week, or next month.
It is for those who want to have fun with their lifestyle anywhere from a couple of years to a couple of decades from now.
Rob's Rule: A 4-5% return is a damn great baseline to build on.
What’s the Trade, Rob?
Yes, there’s an ETF for that.
Meet iShares 0-3 Month Treasury Bond ETF (SGOV).
If you want the ultimate embodiment of "chill" in today's market, look at ultra-short term Treasury ETFs like SGOV, along with peers like the iShares Short Treasury Bond ETF (SHV) and SPDR Bloomberg 1-3 Month T-Bill ETF (BIL).
As opposed to the endless set of stock ETFs that sound different but act the same in down markets (they head south, maybe well before winter this year), these ETFs yield around 4% annualized, simply by holding US Treasury bills.
They carry virtually zero price volatility and pay out monthly cash distributions.
The Bond Market is Back
“Long-term investing” sounds great when it is pitched to us by people whose own livelihood relies implicitly on matching financial products with cash-carrying people who are financially equipped to buy them. At least, that’s how it is supposed to go.
However, these are without a doubt the strangest of times for those relying on market history to project their returns forward based on whatever happened in the past. And it all starts with bond yields. Now that we actually have yield from bonds.
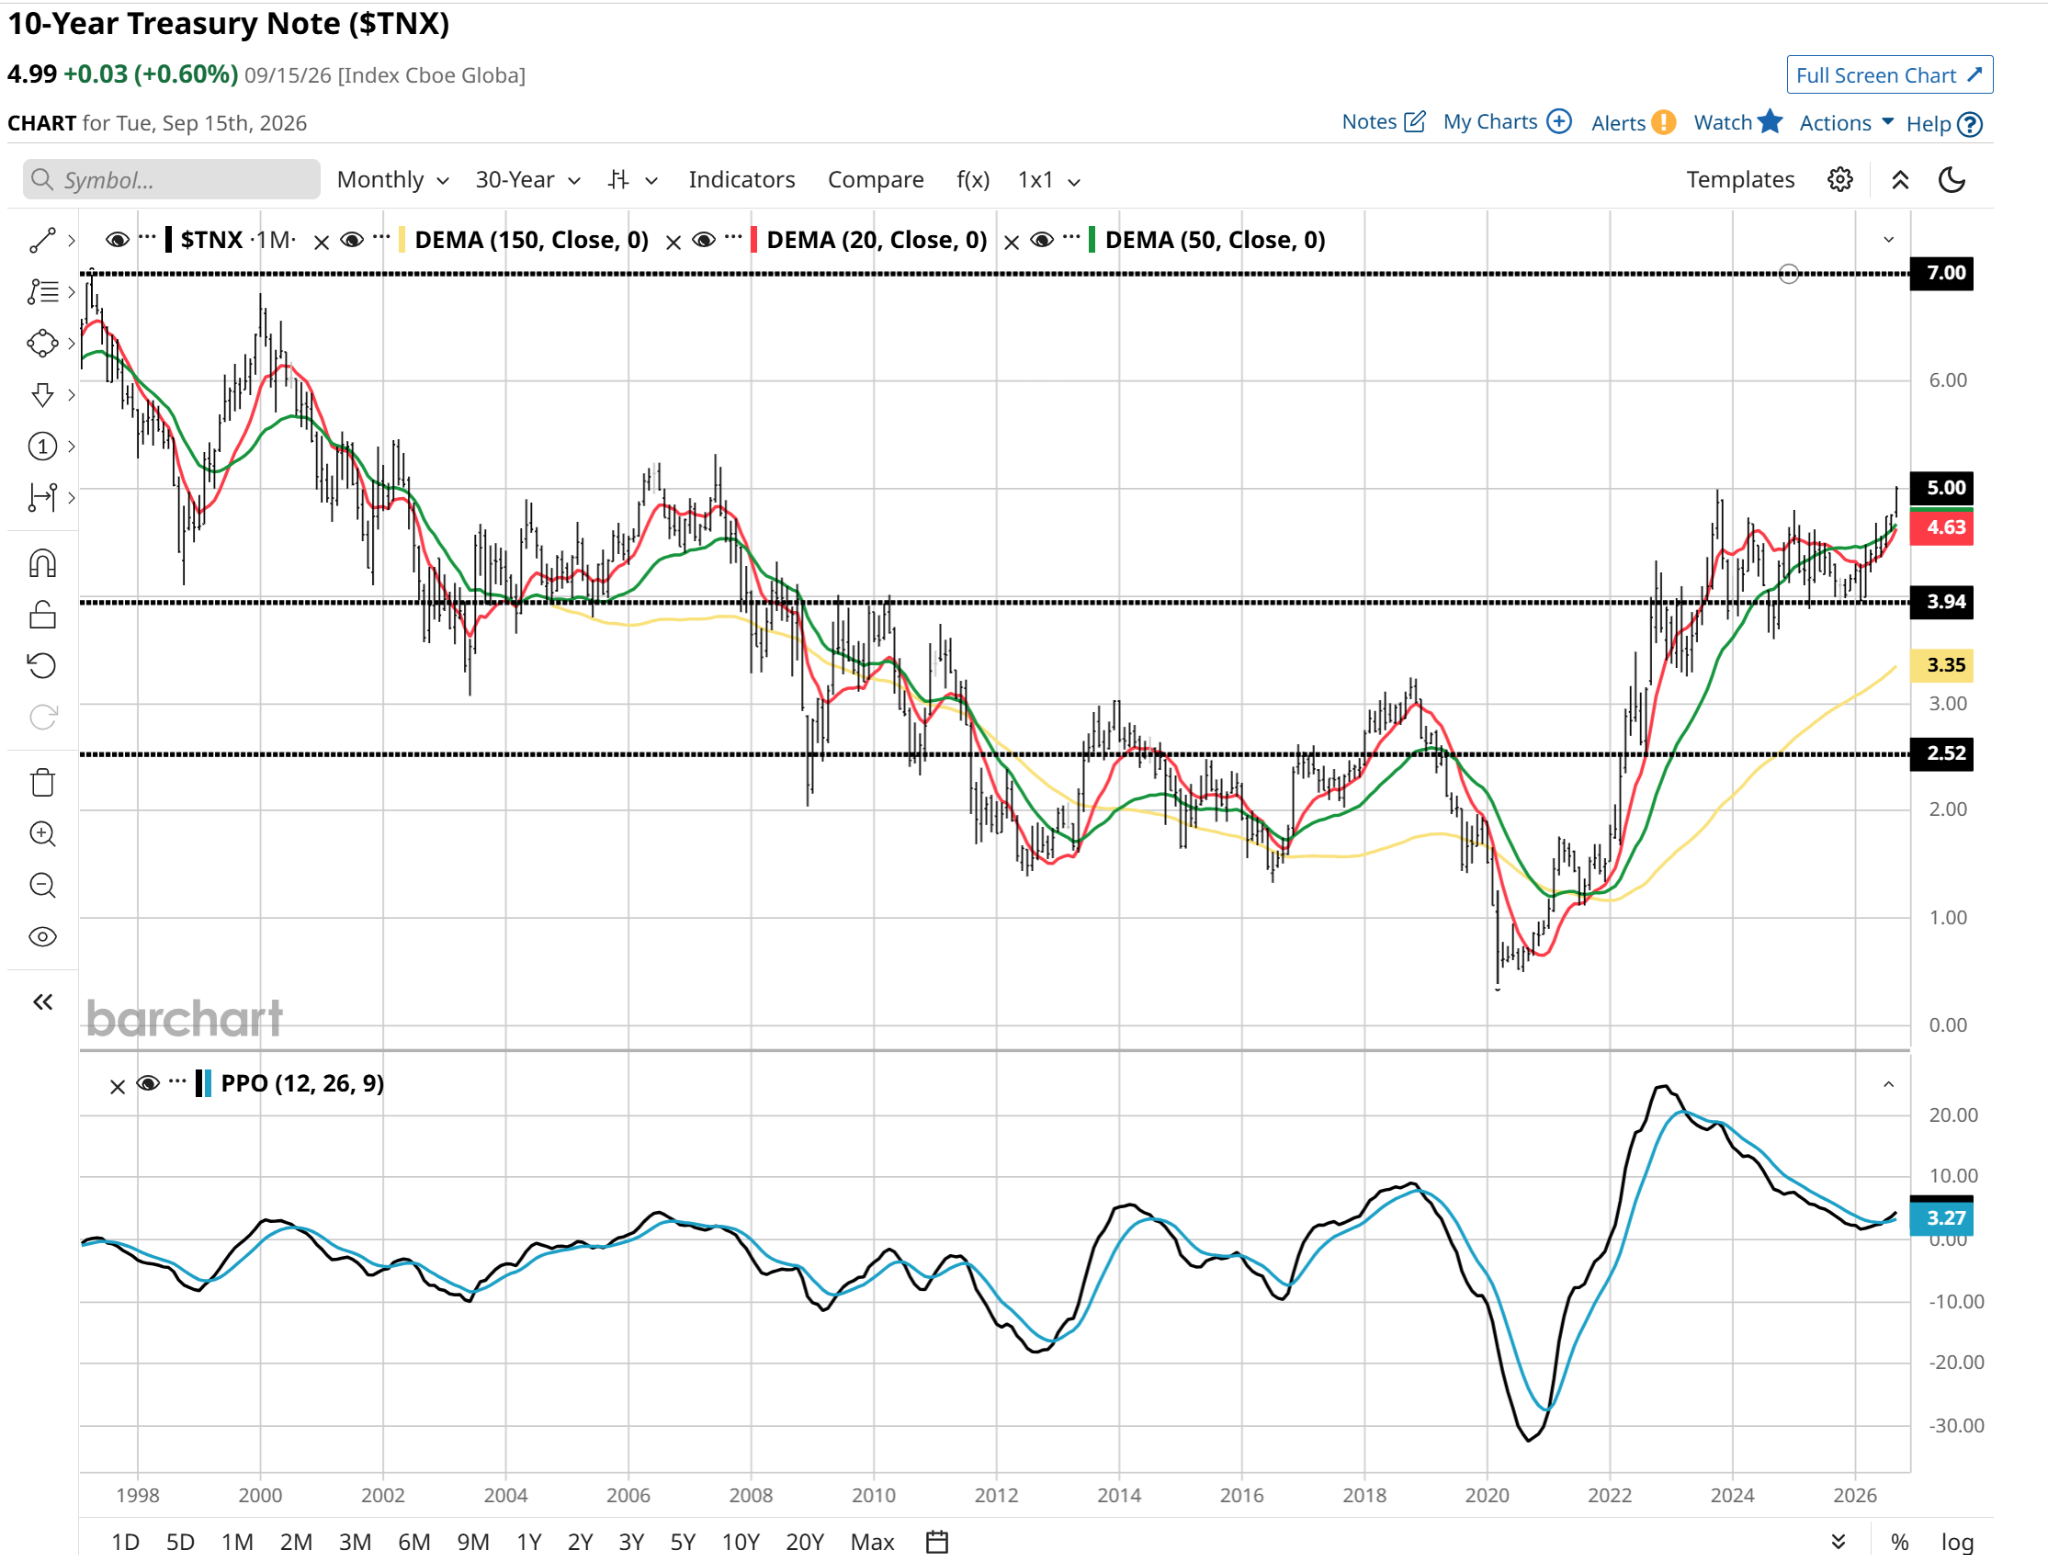
To state the obvious, a 5% annual return is… 5% a year. (Duh.) However, it has been nearly 20 years since we earned that much in exchange for the risk that the U.S. Treasury could not pay us back.
As I see it, if that transaction fails to function as it has forever, we have much bigger issues at hand. So, yeah – 5% is a really big deal.
Now look backward on the yield curve to Treasury bills maturing anywhere from very soon to 12 months out.
That’s 3-month Treasury Bills ($IRX) right there. They were literally at rock bottom for most of 2008–2022. Then, like a penny stock that turns into a meme stock…bang! Up to 5% recently, and hovering around 4% now.
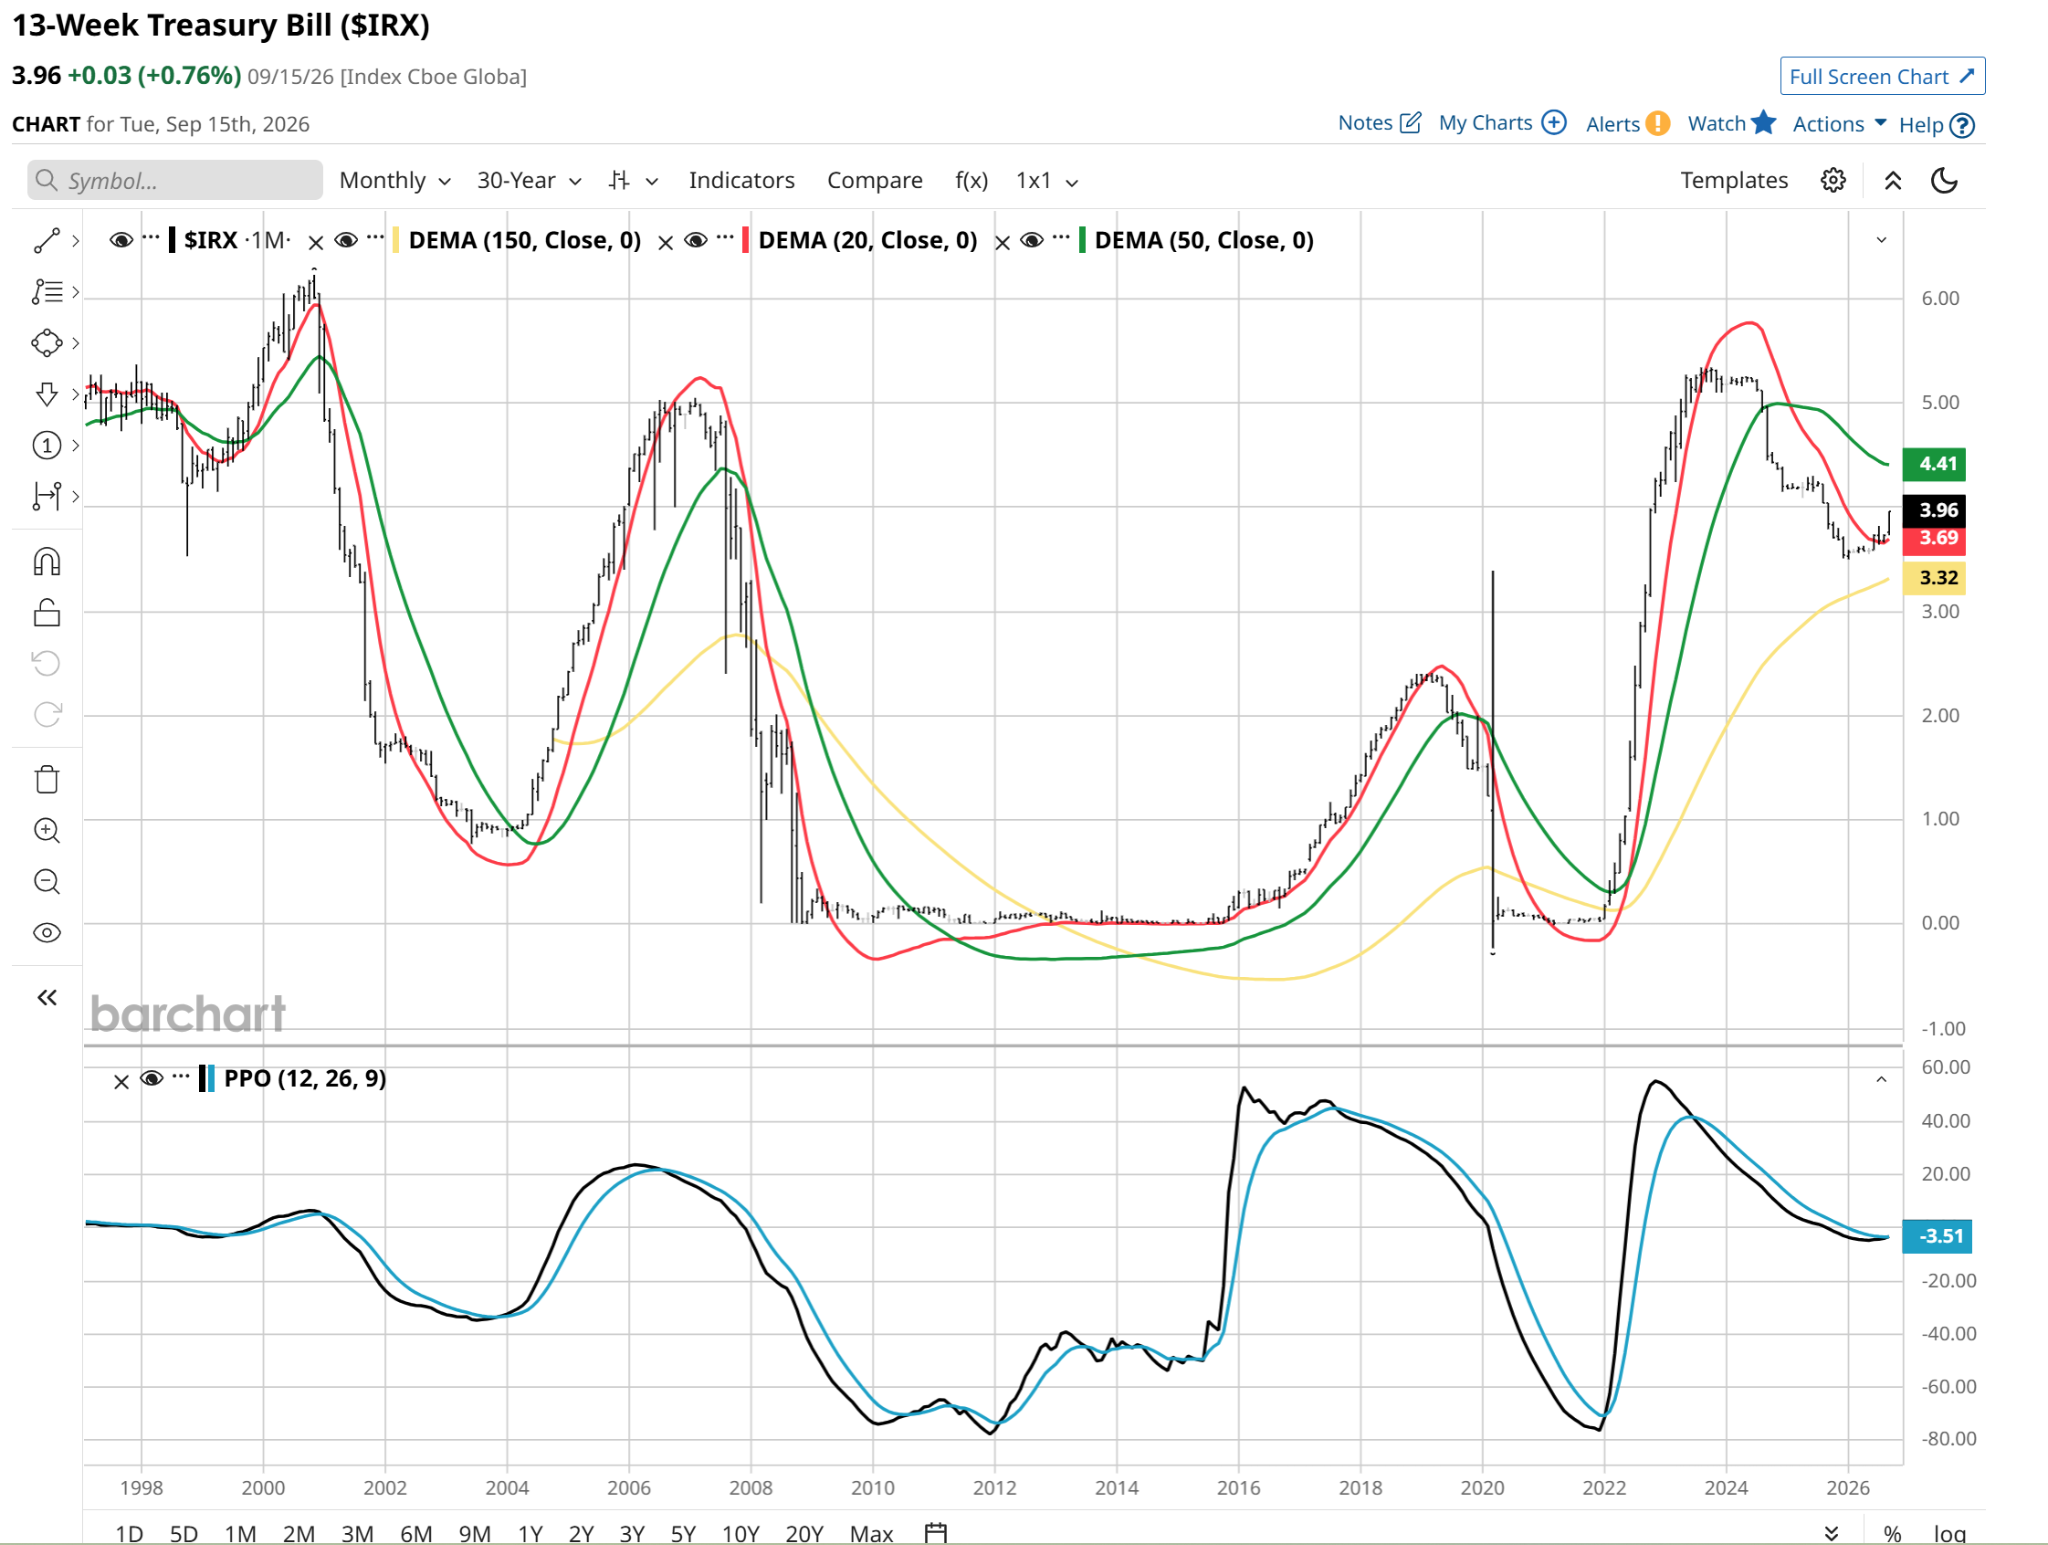
For doing what? As a client from my former days as an investment advisor often said, “sitting on my fat ass.”
For a month, a quarter, a year, or in between. And with the markets we have right now, you’re not going to convince me that it isn’t a primary player in my portfolio.
Deeper Dive: The Math, The History, and The Risks
It’s not because we can’t do better in stocks or something else. But after this type of run in equities, with the S&P 500 Index ($SPX) up 13.5% a year over the past 10 years, check out this stat:
Looking at rolling 10-year returns since 1970, equity returns exceeded the 5% return one can get on a 10-year bond today about two-thirds of the time.
So over the next 10 years, back-of-the-envelope style, there’s a one-in-three chance a 10-year bond return beats stocks.
If we take it a step further and assume that investors require, say, 2% a year more than what they can get by sitting on my fat ass (there it is again) for 10 years, how often did the S&P 500’s 10-year annualized return exceed 7%?
The chances drop to about 58%. Sweating yet?
Probably not if you’re a Baby Boomer. My fellow boomers, by many accounts, are habitually overweight in stocks. And there’s no GLP-1 for that.
However, the bond “drug” in some form might just be a cure. Not as a full-scale replacement; anyway, I’m long past the point of my career where my job is to tell other people what to do with their own money.
That was my job for a long time. Now, after doing this for 40 years as of last month, I’m just conveying what I see: 5% is a damn great return to build around.
Longevity Shots & The Yield Curve
A recent survey by Bank of America revealed that more than 90% of wealthy Americans say longevity is an important factor in financial planning. That makes sense.
However, the biggest hurdle might not be future market returns. It could be "expected arrogance," built up from years of great S&P 500 returns timed perfectly with their heaviest accumulation years.
Bonds and T-bills? Those are for wimps, right?
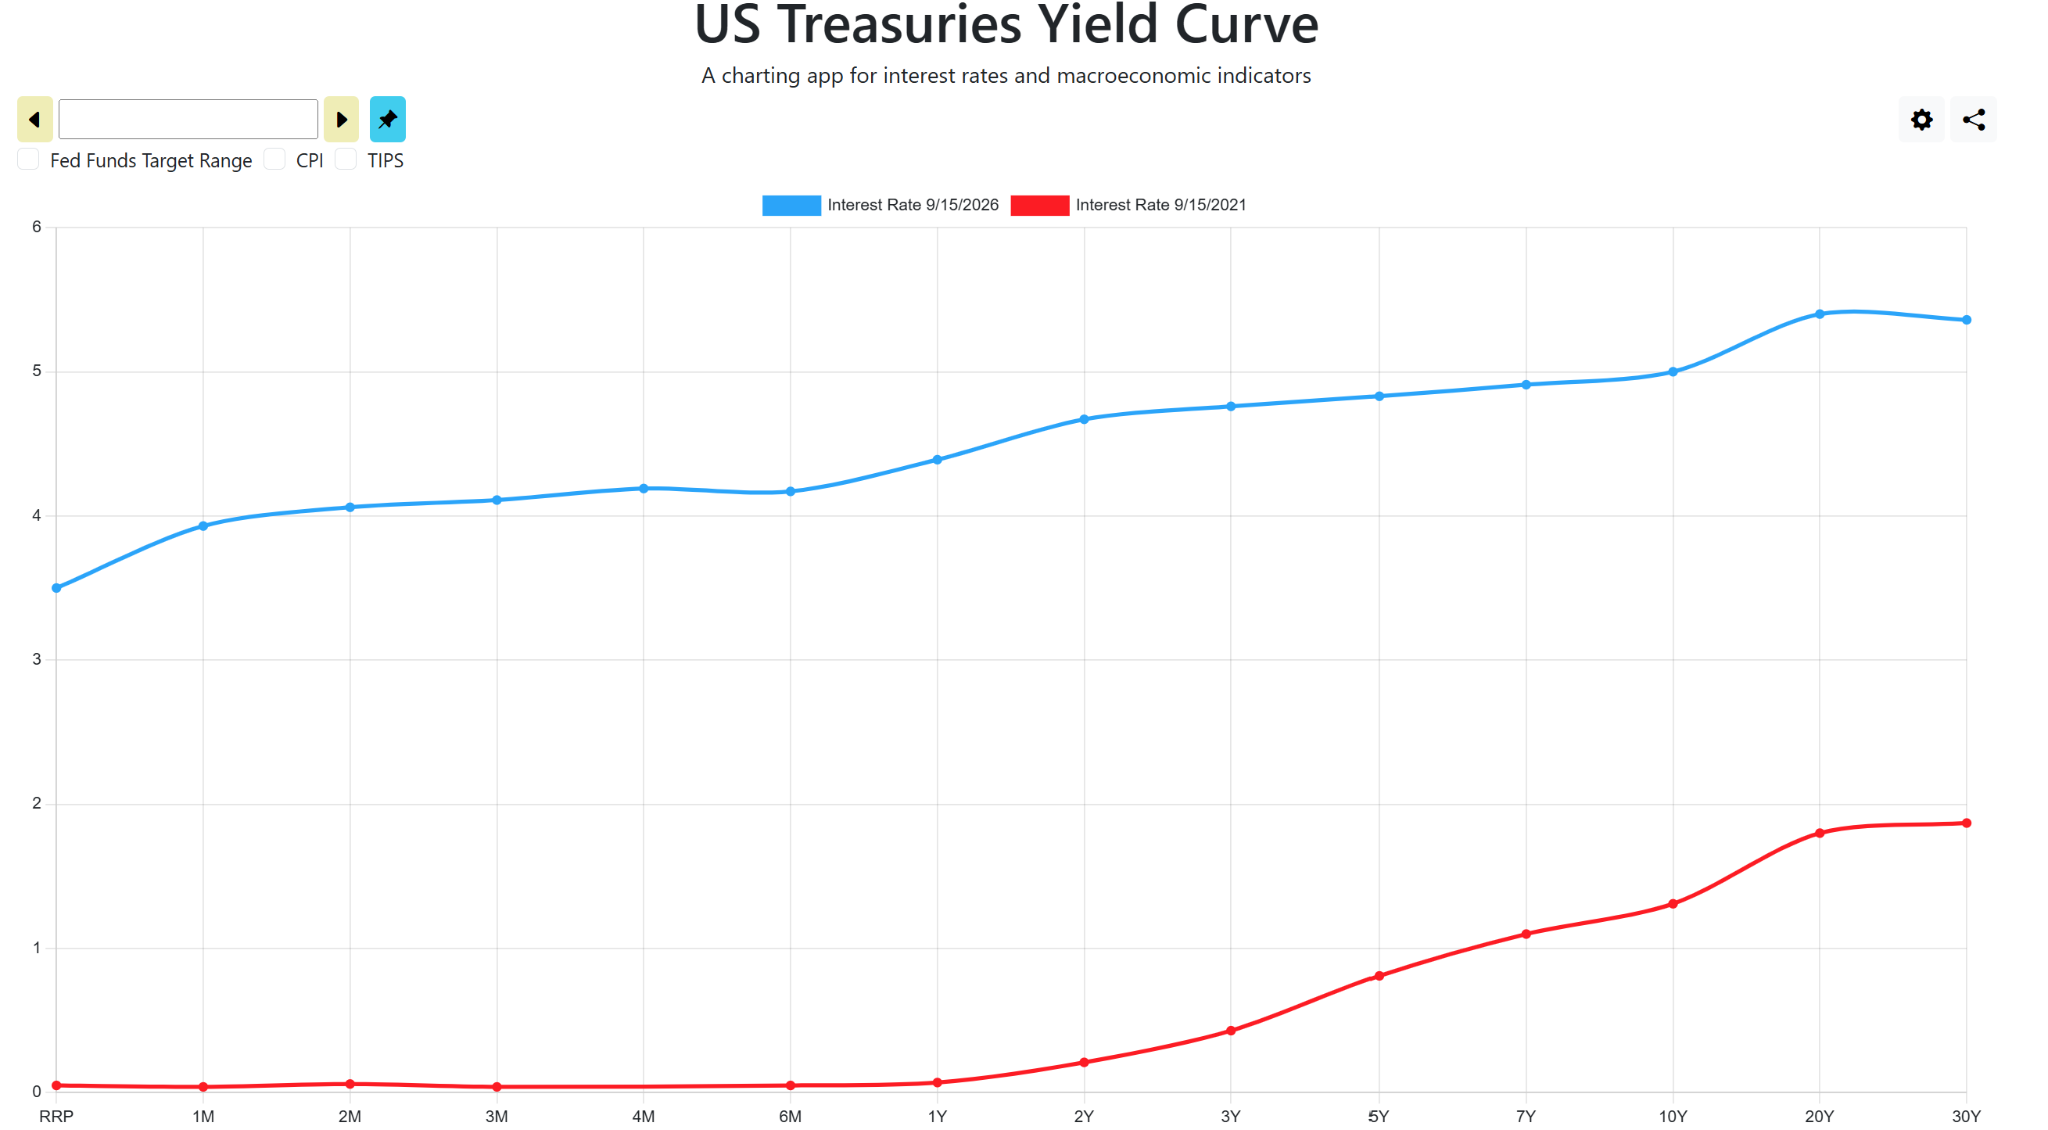
Look at that yield curve above. The red line shows 0-to-30-year bonds from five years ago; the blue line is where we sit today. When I see how bonds have been maligned or ignored for so long, I can’t help but have the theme from TV’s The Greatest American Hero running through my head:
"Look at what's happened to me, I can't believe it myself. Suddenly I'm up on top of the world, it should have been somebody else..."
(Feel free to dovetail that with George Costanza’s classic “Seinfeld” answering machine message.)
If you think this article is strictly about buying static bonds, not really. It is about how the bond market is back in play.
Going out 10 years (or even 5) carries price volatility if rates spike further. If rates go from 5% to 7%, which is that top line drawn across the first $TNX chart above, that would be a 30-year high and a total mess for unhedged bond investors.
That’s why in my next column in this series, I’ll focus on how I hedge a bond portfolio against rising rates, and later, how to capture equity-like gains when yields drop.
In Closing: Why T-Bills Are Like Drinking Beer in the Rain
Sort of like beer, I’m not going to "own" T-bills in massive size forever. I’ll rent them.
Down here in South Florida, we are in the heart of the rainy season. Hurricanes, downpours, blah blah blah. You know what we do when the rain falls like cats and dogs almost daily? We take shelter.
T-bills and short bonds are a nice, sturdy roof over the head of a portfolio. And that is worth getting excited about. As I sit on my… well, you know, watching the equity markets sway back and forth.
Rob Isbitts is a semi-retired CIO, former fiduciary investment advisor, and Barchart columnist. Check out his other work at ETFYourself.com (featuring the Fresh Charts weekly trading post) and ROAR.PiTrade.com, helping investors better manage their own portfolios.