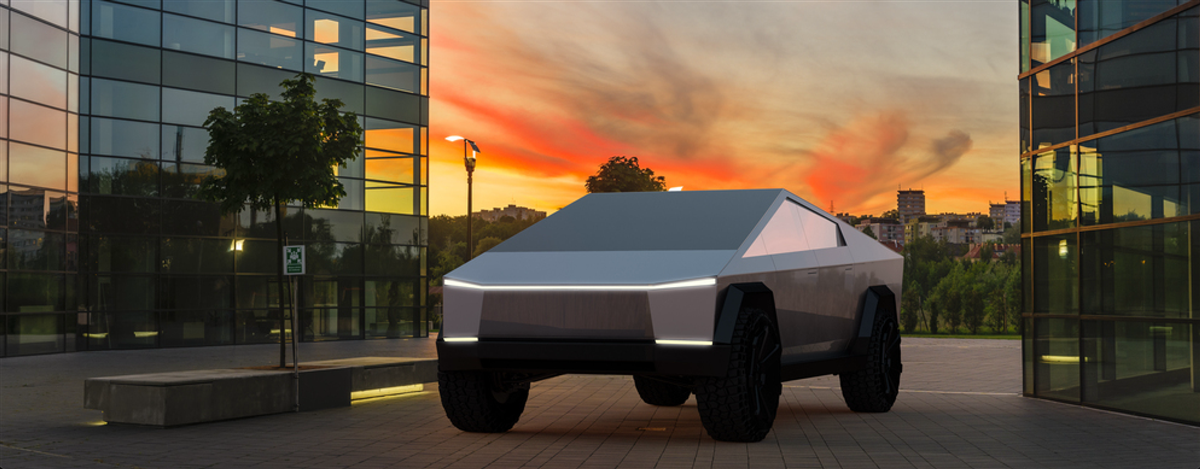
Tesla, Inc. (NASDAQ: TSLA)’s Cybertruck discounts are bad news for the stock price. The company announced a series of discounts in early January that suggest tepid demand in what should be a growth driver. The news includes shifting workers to other lines, indicating no pick-up in demand is expected. The takeaway is that the leading EV manufacturer faces increasing competition and will likely report another annual decline in total vehicle deliveries while the remainder of the industry grows.
The outlook for Q4 and 2025 is optimistic despite the downtrend in revisions. The analysts expect revenue growth to accelerate sequentially and year over year, topping 15% in 2025. Growth drivers will include power generation and services, but weakness in the core automotive unit will offset them. Headwinds to growth include the higher-for-longer interest rate environment, affordability, and policy. President Trump is expected to quash OEM and consumer incentives for EVs early in his administration, increasing hurdles and slowing demand.