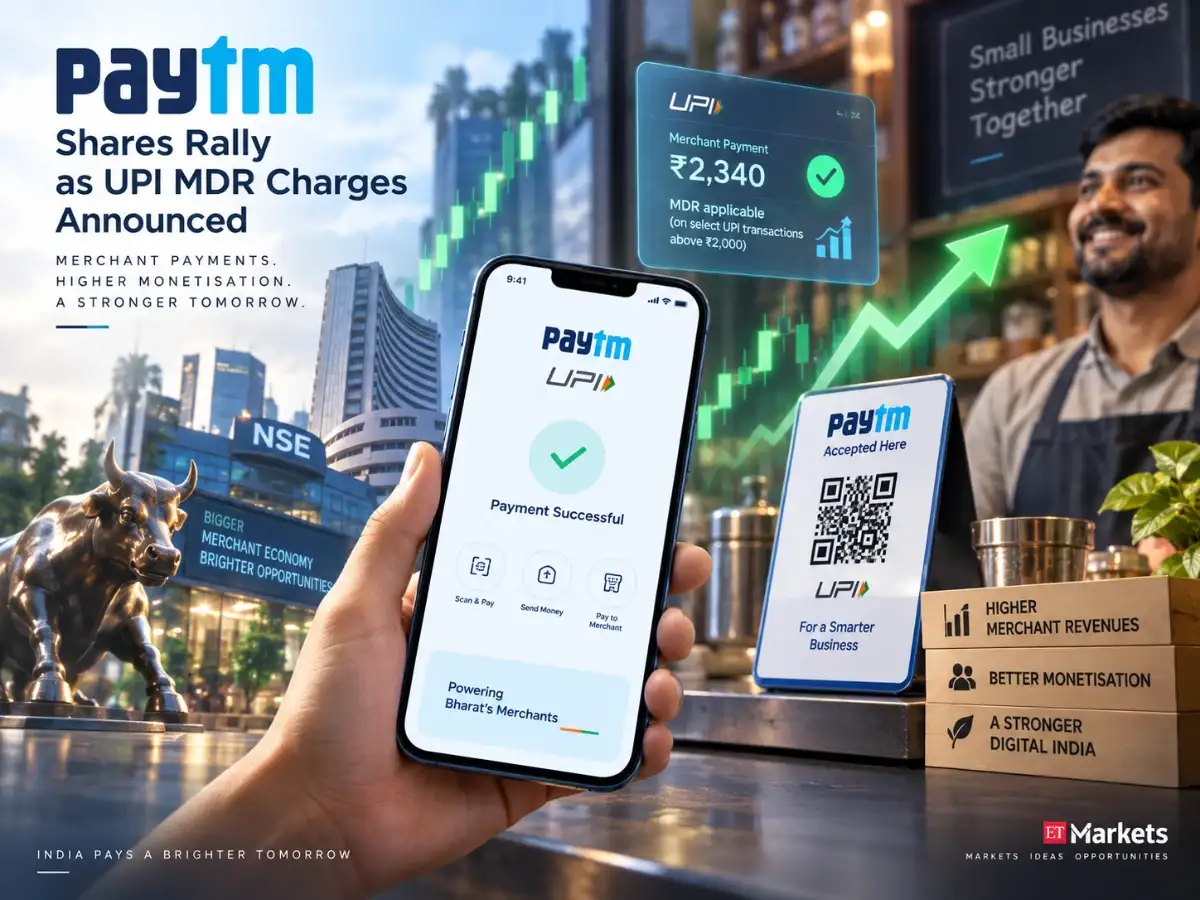
Paytm shares sharply rallied more than 7% on Wednesday as brokerages issued bullish notes and increased target prices for the fintech stock after the government announced the first-ever Merchant Discount Rate (MDR) on select UPI transactions above Rs 2,000.
The company's shares rallied sharply to Rs 1,855.50 apiece on NSE, on track to record the sharpest single-day jump since August 10, when they surged 10% after Bernstein gave its first-ever price target above the company’s original IPO price.
The government will introduce MDR on some Person-to-Merchant (P2M) UPI transactions from October 15 onwards, with merchants paying 0.4% on transactions above Rs 2,000, the National Payments Corporation of India (NPCI) announced on Tuesday. A maximum fee of Rs 300 can be levied on such transactions of Rs 75,000 or more.
What Paytm said on new MDR charges
Paytm, in an exchange filing on Tuesday, said the government’s latest move will generate additional revenue from the merchant business for many of the payment transactions that were free earlier. The fintech platform highlighted that no charge will be levied on customers for UPI payments, which shall continue to remain free of charge for them.
NPCI announced that consumers will not be charged for making UPI payments, while Person-to-Person (P2P) transfers will also remain free. Small merchants classified under the P2PM framework, including vendors receiving up to Rs 1 lakh a month through UPI QR codes, will continue to be protected from MDR.
Jefferies on Paytm share price
Jefferies maintained its ‘Buy’ call on Paytm shares, and increased its target price to Rs 2,150 apiece, implying over 24% upside potential. After recently increasing earnings estimates for the fintech platform, Jefferies again increased its earnings estimates for FY28-29 by 10-12% to factor in a 40 bps revenue pool even after making adjustments for exemptions, competitive pricing and other aspects.
The international brokerage also raised FY27 profit estimate by 18%, factoring in a slight benefit in FY27 as well. It also raised the target price for Pine Labs to Rs 235 apiece.
JM Financial on Paytm share price
JM Financial increased its target price for the shares of Paytm to Rs 2,150 apiece, implying more than 24% upside potential from the stock’s previous closing price, while maintaining its ‘Buy’ call on the stock. The notified MDR rate is materially above the 25 bps JM Financial had modelled in, but the carve-outs are also broader than assumed, forcing our hand to cut the eligible-GMV overlay to 20% (from 30% earlier).
The new charges on UPI transactions are expected to generate incremental revenue of Rs 2.1 billion in FY27 and Rs 4.7 billion in FY28, according to the domestic brokerage. “MDR converts a structurally zero-revenue GMV pool into ‘monetisable’ volume with nearly full flow-through to EBITDA, not to mention a clear resolution to the long-standing regulatory overhang on UPI monetisation,” it added.
Emkay Global on Paytm share price
Emkay Global Research meanwhile said the latest move will likely benefit Paytm and Pine Labs, while maintaining its ‘Buy’ calls on the stocks and increasing target prices to Rs 2,400 and Rs 230 respectively. The latest target price for Paytm implies around 39% upside potential.
“UPI acquiring now carries a commercial revenue model that is contractual, recurring, and scales with value, in place of a discretionary annual subsidy. This will make the payment business structurally self-sustaining, making the business model much more resilient,” the domestic brokerage said, adding that even on conservative assumptions, it estimates Paytm to generate UPI MDR revenue of Rs 1,120 crore in FY28, and expects Pine Labs to generate Rs 155 crore in the same year.
Also read | New charges on UPI payments: Here's what you will be charged for stock market investments
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.