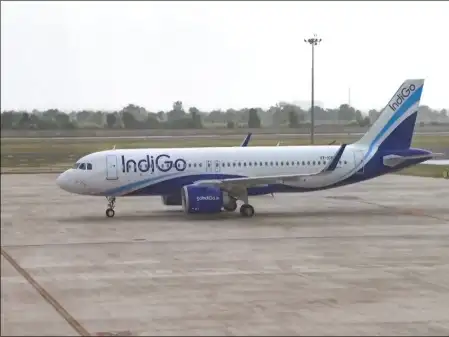
Nomura has initiated coverage on InterGlobe Aviation, the parent company of IndiGo, with a Buy rating and a target price of Rs 6,000, implying around 20% upside from the stock’s September 30 closing price of Rs 4,984. The brokerage believes IndiGo’s large aircraft order book, low-cost structure and expanding international network could help it emerge stronger even if elevated fuel prices persist.
Nomura’s core argument is that the current fuel shock may hurt near-term profitability, but could also widen IndiGo’s competitive advantage over airlines operating with higher cost bases. The brokerage expects revenue and EBITDA to grow at CAGRs of 16% and 38%, respectively, between FY26 and FY29, assuming partial normalisation of the war situation in FY28.