
Microsoft (MSFT) raised its quarterly dividend to $0.98 per share on Sept. 15. That is a $0.07, or about 8%, increase from its previous $0.91 payout. The dividend will be paid on Dec. 10 to shareholders of record as of Nov. 19. Nov. 19 is also the ex-dividend date.
As Microsoft continues to pour capital into AI infrastructure while revising its reporting structure to give investors a clearer view of its Azure-led cloud business, the company returned $10.2 billion to shareholders through dividends and buybacks in a single quarter. It has now raised its dividend for 24 consecutive years, moving it closer to Dividend Aristocrat status.
With the stock trading near $500 and a yield still below 1%, the question is whether this latest 8% increase is enough to make MSFT worth buying today.
A Look at Microsoft’s Financial Strength
Microsoft generates the bulk of its revenue from business software, cloud computing, productivity tools, devices, gaming, and AI products.
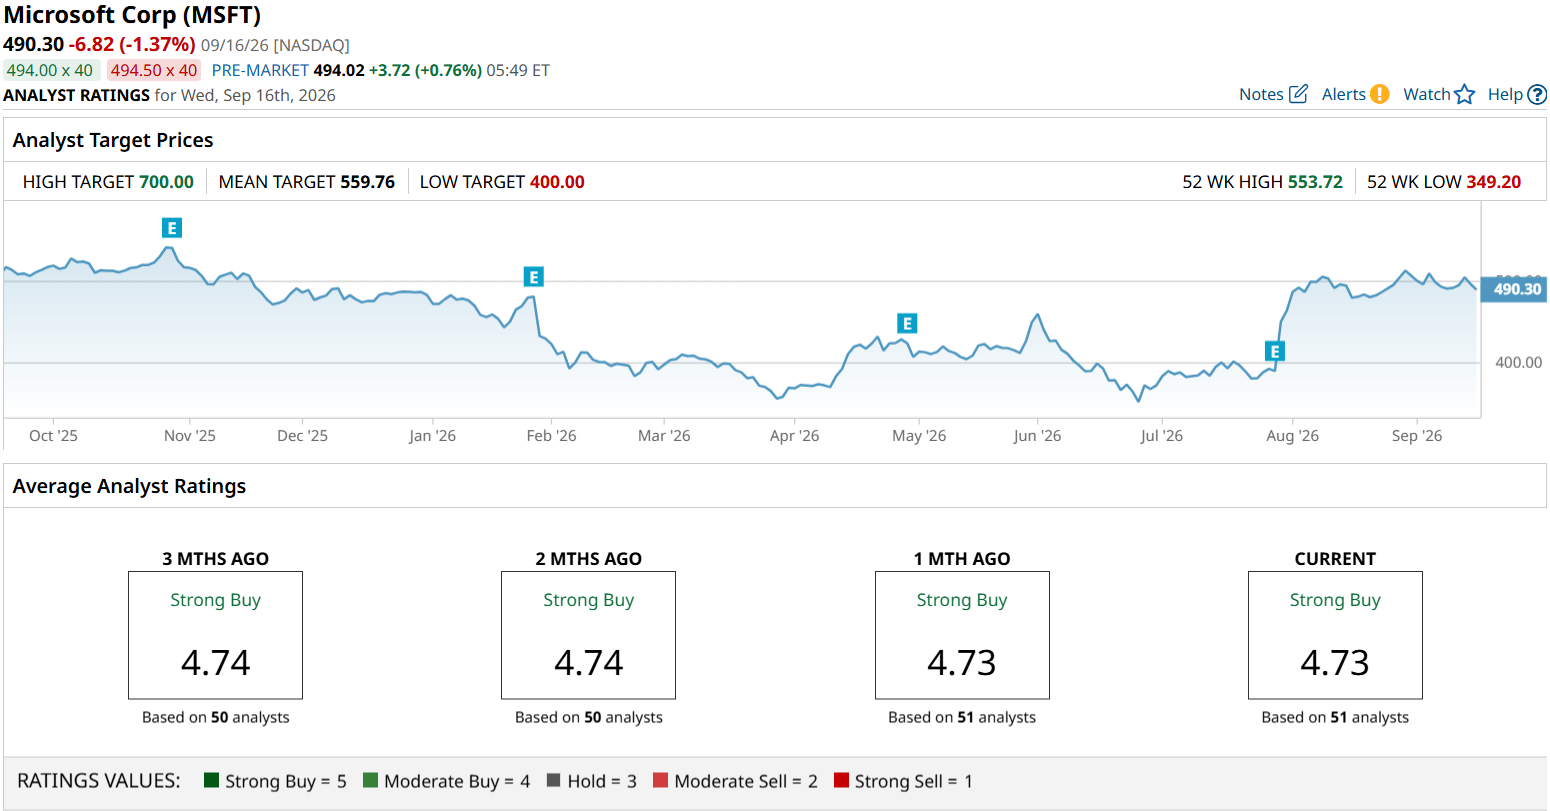
Over the past 52 weeks, the stock has declined 3.68%, though it has edged up 1.38% year-to-date. It currently trades at 25.77 times forward earnings — above the technology sector average of 22.18x.
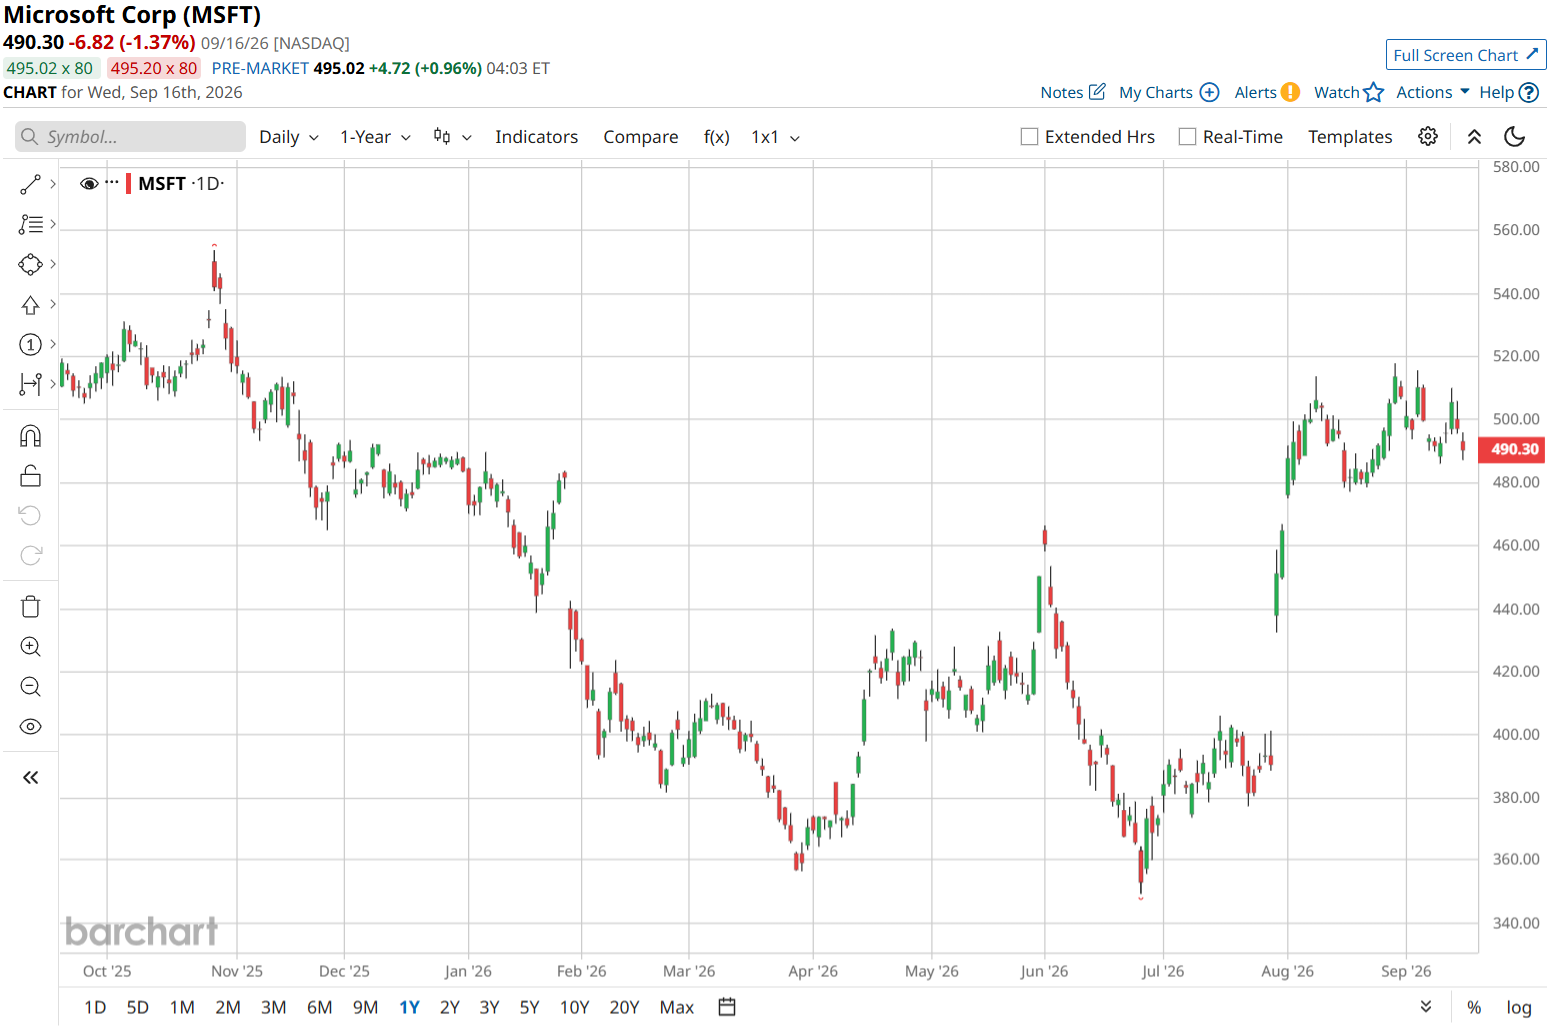
The company recently raised its quarterly dividend by $0.07, or 8%, to $0.98 per share (from $0.91), with the new dividend being paid on Dec. 10 to shareholders of record on Nov. 19. Before the increase, the annual payout stood at $3.64 per share, equating to a 0.73% yield, with a forward payout ratio of just 20.53% that leaves ample room for future growth. Although Microsoft pays shareholders every quarter, its yield remains well below the technology sector average of 1.37%.
That modest yield is underpinned by strong earnings momentum. In fiscal fourth-quarter 2026, revenue climbed 18% year-over-year to $90 billion, operating income rose 18% to $40.6 billion, GAAP net income surged 31% to $35.8 billion, and GAAP earnings per share increased 32% to $4.81 (non-GAAP EPS advanced 23% to $4.74).
Segment performance was led by Microsoft's Intelligent Cloud unit that jumped 32% to $39.3 billion, while Productivity and Business Processes grew 14% to $37.8 billion. More Personal Computing revenue slipped 4% to $12.9 billion even as Microsoft Cloud overall expanded 27% to $59.3 billion. The company’s commercial backlog soared 84% to $678 billion.
The Growth Engines Behind MSFT
Microsoft is deepening its collaboration with Nokia (NOK) to help telecom operators automate more of their network operations. Together the companies are building a shared data platform that integrates Nokia Data Suite with Microsoft Fabric, giving carriers ready-to-use network data alongside Microsoft’s data, governance, and AI tools in a single environment. The aim is to let operators pull reliable insights in minutes rather than weeks and eliminate much of the manual work of stitching together disparate systems.
At the same time, Microsoft is broadening its AI strategy beyond its long-standing reliance on OpenAI. In June the company began deploying its own MAI models inside certain Office applications and is already routing tens of thousands of Excel and Outlook requests each week to these in-house models instead of sending every query to OpenAI or Anthropic. At Build 2026, Microsoft unveiled seven MAI models, including its first reasoning model, MAI-Thinking-1. The result is a flexible multi-model approach: OpenAI remains a key partner, Anthropic’s Claude powers parts of Copilot, and Microsoft can turn to its own models whenever they prove more cost-effective.
That flexibility sits alongside an updated commercial agreement with OpenAI that continues to underpin Microsoft’s cloud business. Under the terms announced in late April, OpenAI committed to purchase $250 billion of Azure computing capacity. Revenue-share payments to Microsoft will continue through 2030 (subject to a total cap), while Microsoft retains access to OpenAI’s models and products through 2032. OpenAI is now free to work with other cloud providers, yet Microsoft is no longer required to share revenue in the opposite direction.
What Analysts Expect Next
Microsoft is set to report fiscal first-quarter 2027 results on Nov. 4, 2026. Wall Street expects the company to earn $4.69 per share for the September quarter, up 13.56% from $4.13 per share a year earlier. For the full fiscal year ending in June 2027, analysts expect earnings of $19.61 per share, up 13.48% from fiscal 2026 EPS of $17.28.
JPMorgan Chase (JPM) raised its price target on Microsoft to $625 on August 13. That target points to more than 25% upside through the end of 2027. Analyst Samik Chatterjee expects AI demand to support further gains, as Microsoft turns its cloud infrastructure and AI products into more revenue.
Similarly, Stifel Financial (SF) raised its price target to $530 from $450 but kept its “Hold” rating. The firm sees stronger demand for Microsoft 365 Copilot and noted that more customers are moving from testing AI tools to using them more widely. That could help Microsoft bring in more recurring revenue over time.
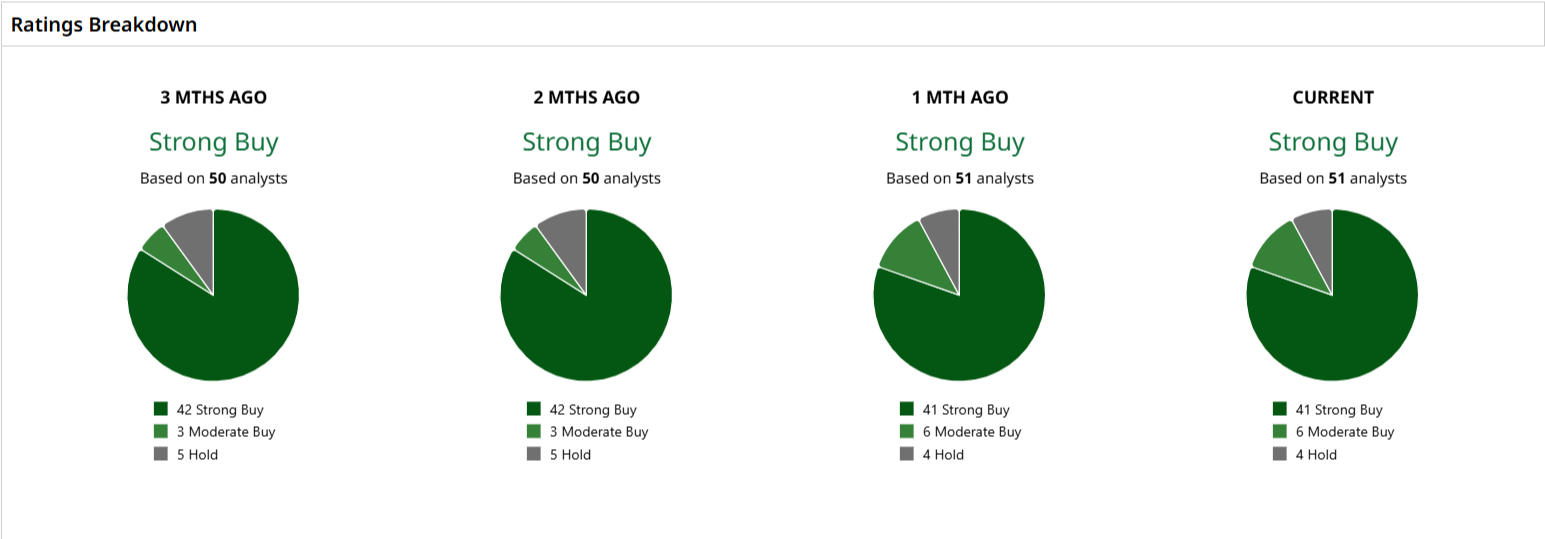
Overall, all 51 analysts covering Microsoft rate the stock a consensus “Strong Buy” with an average price target of $559.76. It suggests about 14.2% upside from current price levels.
Conclusion
Microsoft’s 8% dividend increase is a welcome sign, but the stock’s appeal rests much more on its AI, cloud, and enterprise-software growth than on its sub-1% yield. The company has the earnings power, cash flow, and modest payout ratio to keep rewarding shareholders while funding its enormous AI buildout. At 25.77x forward earnings, MSFT is not cheap, so investors should expect occasional volatility if AI spending rises faster than revenue. Still, with Azure demand, Copilot adoption, and analyst expectations pointing to continued double-digit earnings growth, shares are more likely to trend higher over the long term than materially lower.