
Mastercard (MA) just took another step into AI-powered shopping. It’s partnering with a startup called Alchemy to let AI agents make purchases on your behalf. Alchemy builds virtual cards for these bots, with built-in rules, spending limits, product restrictions, and permission checks before buying. Plugged into Mastercard’s Agent Pay system, those bots can now shop anywhere Mastercard is accepted online. For shoppers, the whole point is convenience. You tell an agent what you need, set a budget, and let it do the buying. That could mean restocking your pantry or grabbing movie tickets before they sell out. Alchemy bluntly stated that the checkout button is dying. As shopping shifts from humans clicking “buy” to bots doing it for us, Mastercard wants to be the trusted layer that makes it work.
But I don’t think Mastercard is doing this just to make your life easier. A bot doing your shopping has no loyalty and cares only about cost. Analysts have warned that AI agents could target the 2%-3% cost of card payments, routing them to far cheaper options like stablecoins instead. Mastercard has already shown it takes that seriously. This year it paid up to $1.8 billion to acquire BVNK, a stablecoin infrastructure company. The point was to own those cheaper rails rather than be bypassed by them.
So Mastercard is placing itself in the middle of these agent payments early. That way, the bots keep paying through its network instead of skipping it. Visa is racing to do the same, and the two are fighting to own this space before it forms.
The potential opportunity is massive. Morgan Stanley estimates AI agents could drive as much as $385 billion in US e-commerce by 2030. Whoever agents trust to handle the money stands to win big, which is exactly why Mastercard can’t afford to wait.
About Mastercard Stock
Mastercard operates in the payments industry and is one of the leading payment processors for everyday consumers, financial institutions, governments, and businesses. Beyond card payments, Mastercard offers services such as digital and cross-border payments, fraud prevention, cybersecurity, data analytics, and consulting services. Founded in 1966, the company is headquartered in Purchase, New York.
Since early June, the stock has been gaining traction, reaching a 52-week high of $601. However, over the past year, the shares have declined 3%. Similarly, the Amplify Digital Payments ETF (IPAY) has declined 19% during the same period. The stock’s modest decline reflects investor concerns around the company’s valuation, regulatory scrutiny, and emerging payment technologies rather than any weakness in the company’s underlying business.
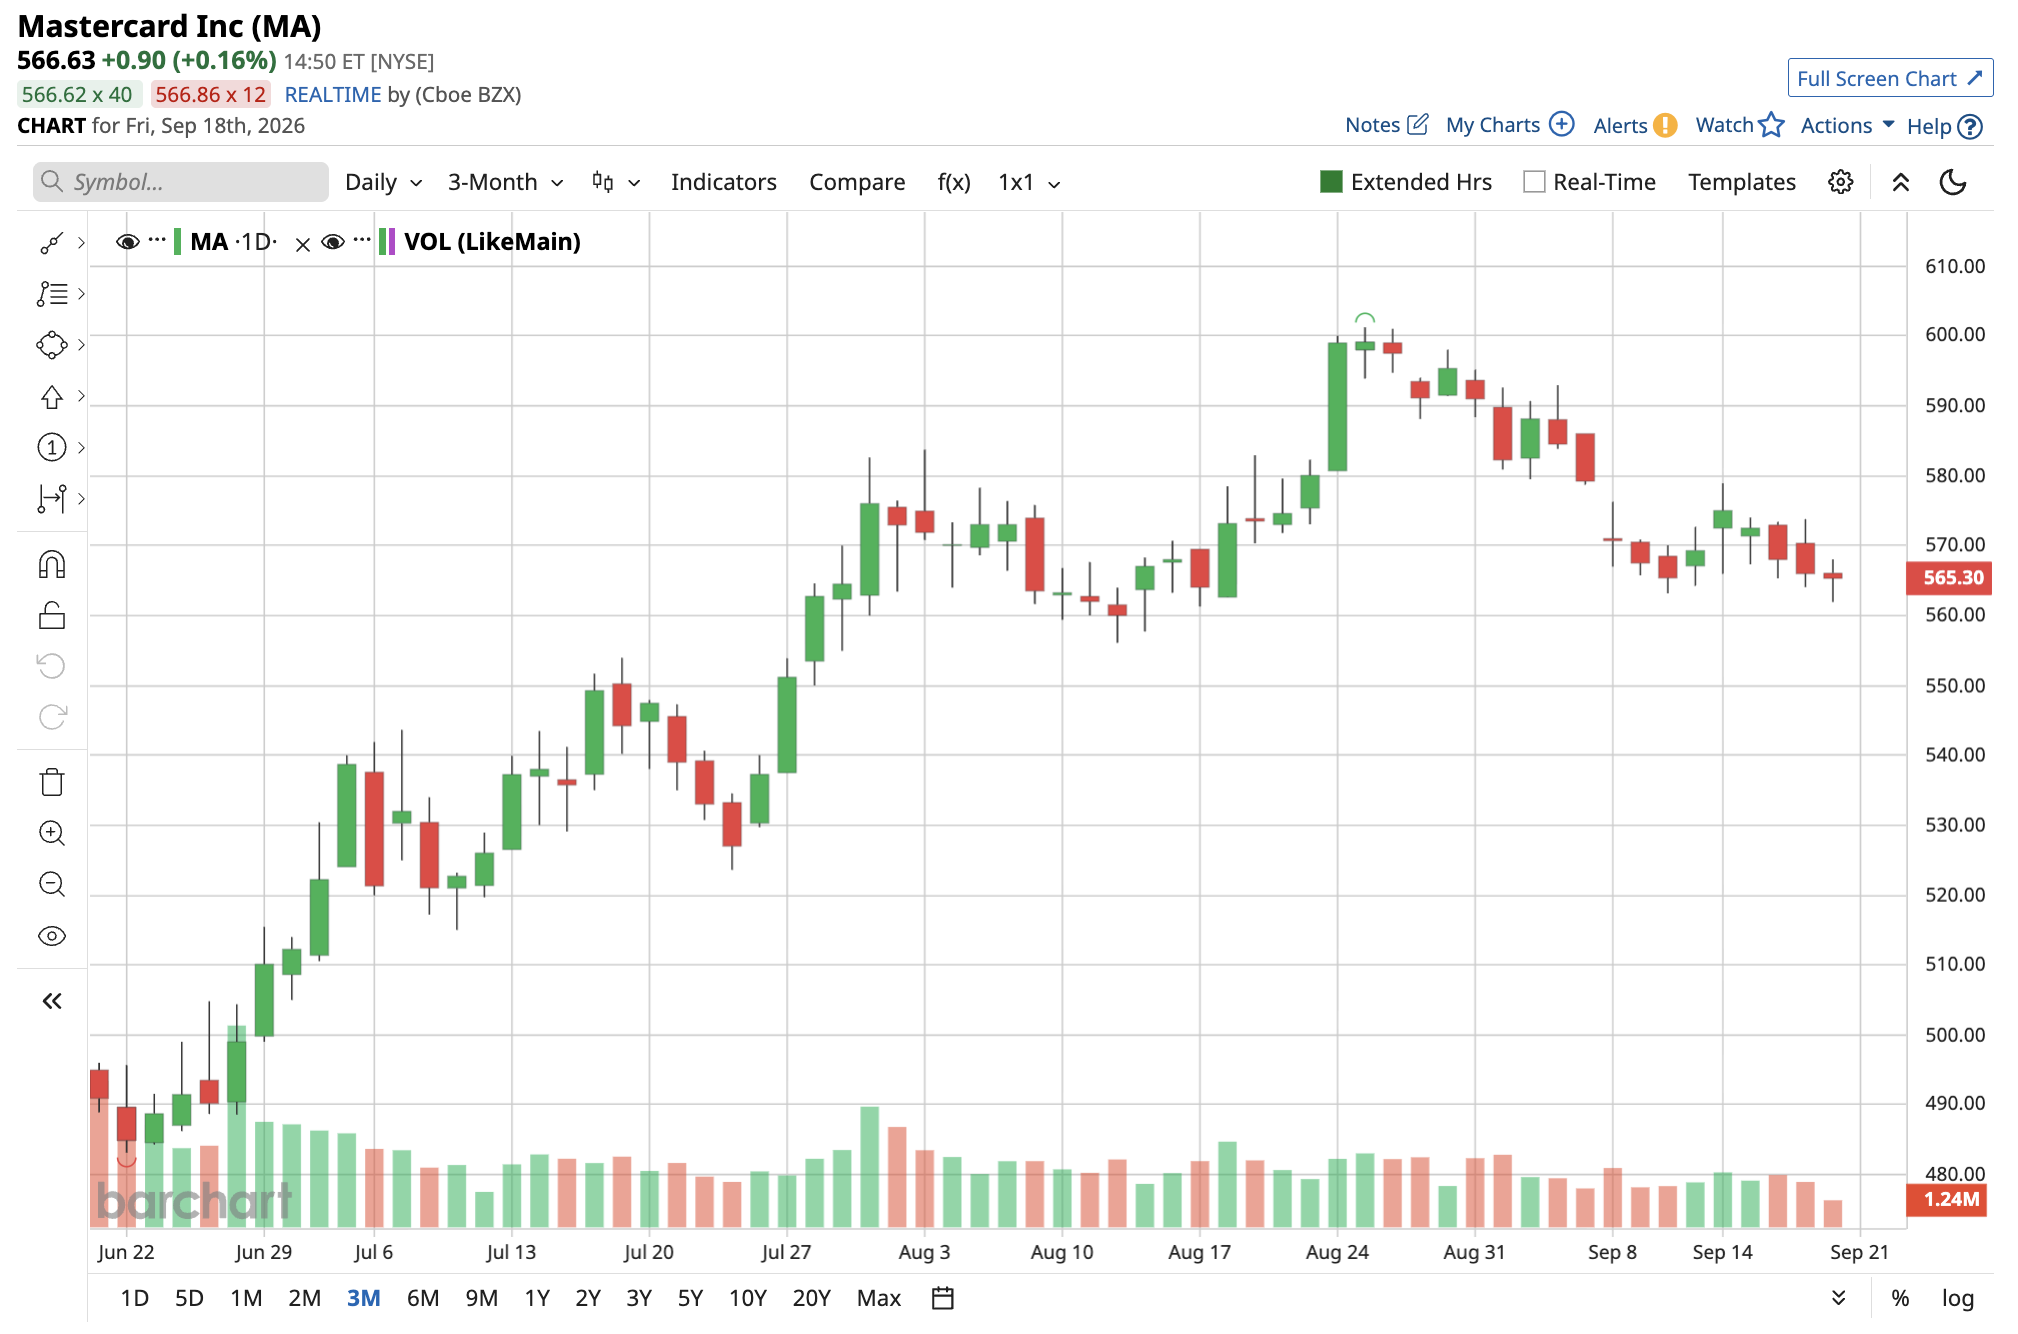
Mastercard isn’t a cheap stock, but it’s trading below its own history. Its forward P/E of 28.93x sits about 13% under its five-year average, and the price-to-sales ratio shows a similar discount. For a company with Mastercard’s margins and steady growth, that discount is worth noticing. The earnings outlook is dependable, with analysts expecting growth of 15%-17% a year through the end of the decade. That consistency is what earns Mastercard its premium in the first place. But the discount likely reflects the risk I’ve covered above. If AI agents move spending off card rails, Mastercard’s fees suffer. The market appears to be pricing in a bit of that worry.
Mastercard Sees Revenue Growth at High End of Expectations Despite Industry Headwinds
Mastercard reported its second-quarter fiscal 2026 earnings on July 30. The company’s net revenue was $9.3 billion, up 12% YoY, reflecting continued growth in its payment network and value-added services. Earnings per share came in at $5.04, comfortably beating the Wall Street consensus of $4.77. Operating income for the quarter was up 14% year-over-year. CFO Sachin Mehra said the company’s operating expenses increased 10%, including a 1 ppt benefit from dispositions.
Looking forward to the third quarter of fiscal 2026, the company expects net revenue growth at the high end of the low-double-digit range on a currency-neutral basis. Mastercard also expects operating expense growth in the low-double-digit range, with a small foreign exchange headwind. Mehra also mentioned that impacts from the Middle East conflict are expected to remain at similar levels to what the company saw at the end of Q2. Management was asked about why purchase volume growth in Europe has slowed from the mid-teens growth rates seen previously, to which Mehra said the company is now comparing against stronger results from earlier periods. He also emphasized that the company is focused on generating profitable transaction volume rather than pursuing growth at any cost.
What Do Analysts Expect for MA Stock?
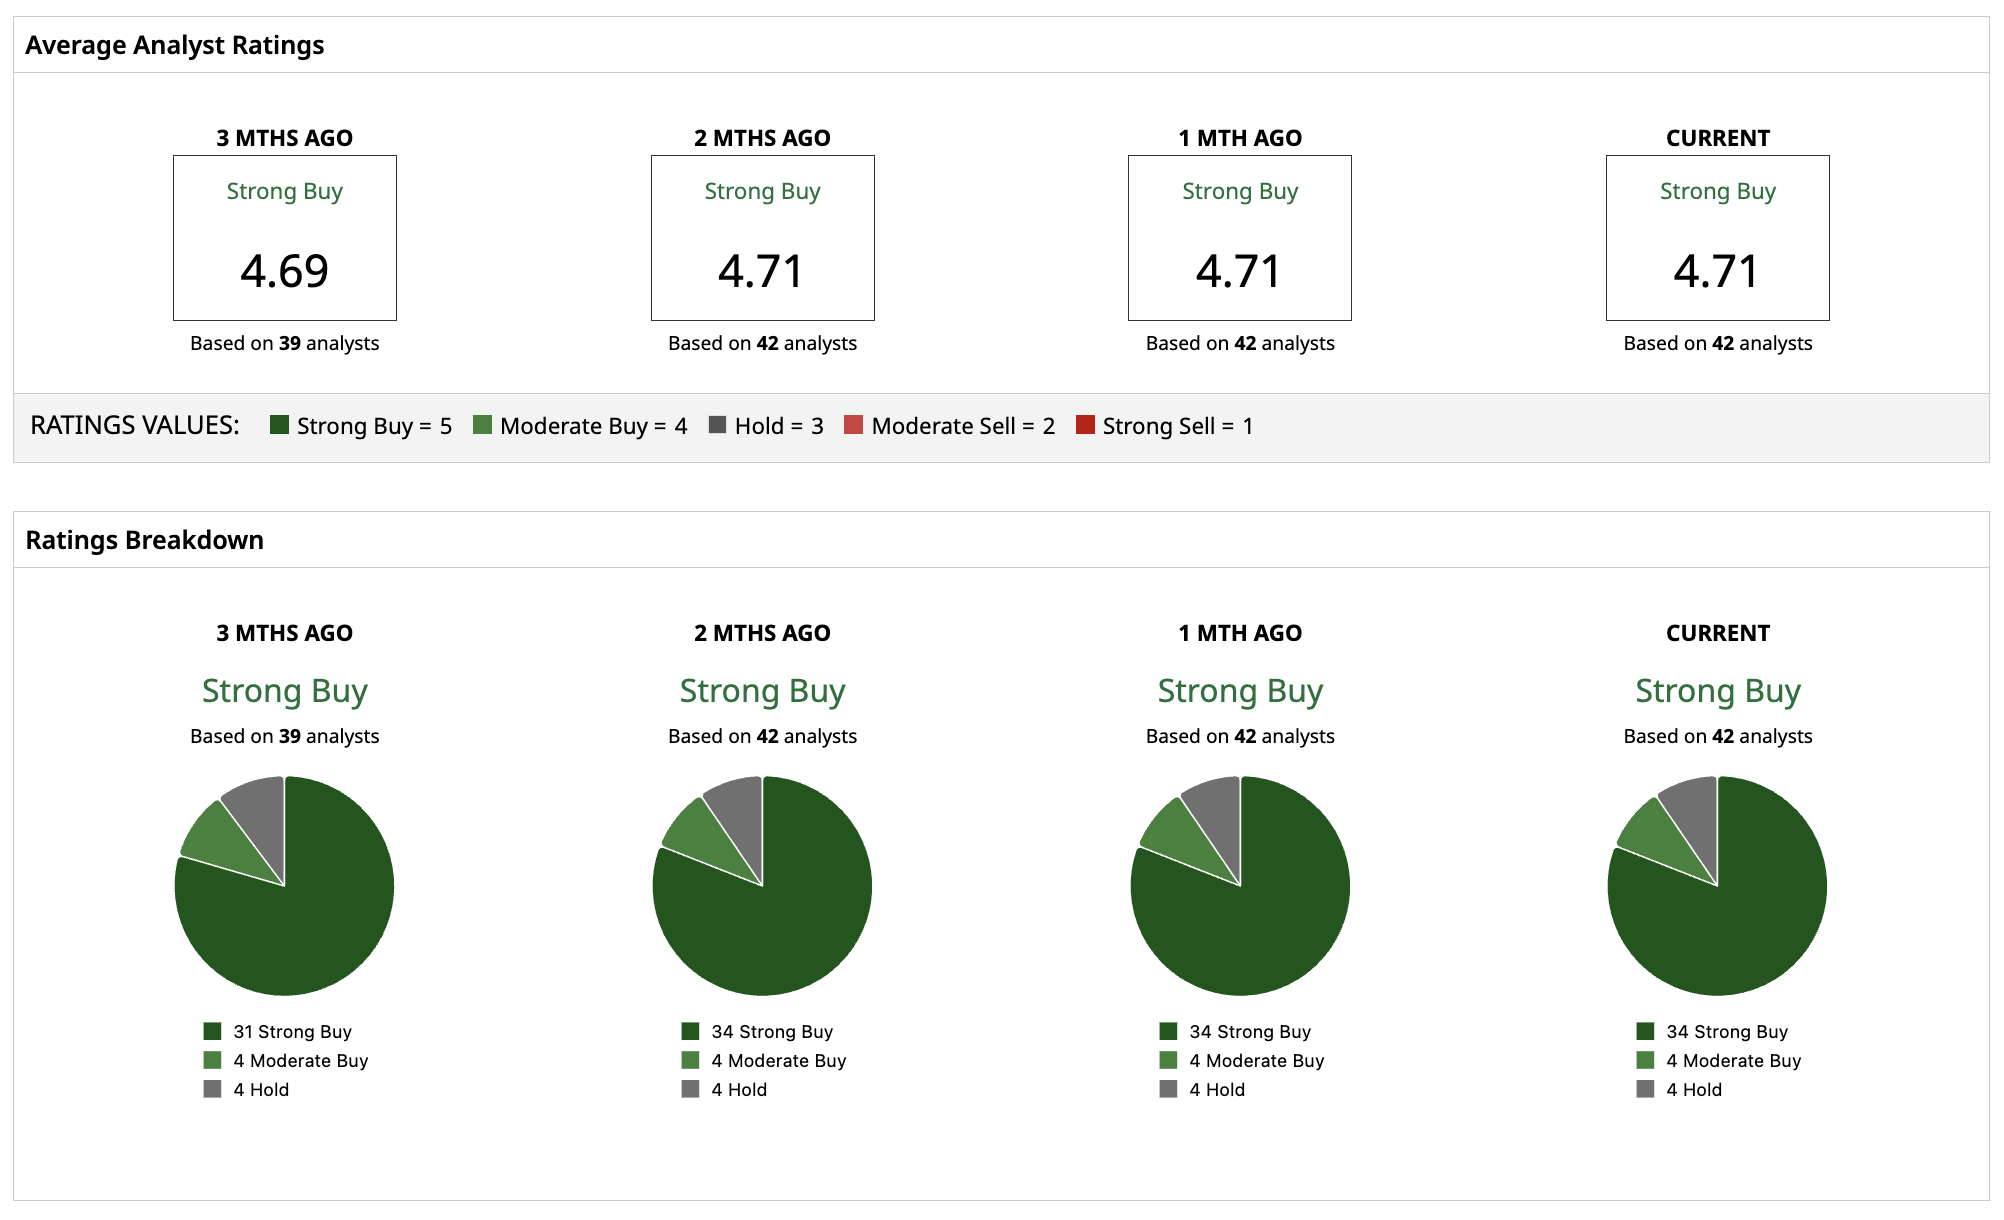
Wall Street remains bullish on Mastercard following its second-quarter results. The stock is being covered by 42 Wall Street analysts and carries a consensus “Strong Buy” rating. On Sept. 9, RBC Capital Daniel Perlin reiterated a Buy rating with a price target of $696. Similarly, Wolfe Research raised the firm’s price target from $680 to $740 and kept an Outperform rating. As the company provided optimistic guidance for the third quarter, Wall Street is likely to remain bullish on the stock. The median price target of $665 reflects 17% upside from current levels. The stock has a high price target of $740, which further implies 31% upside from the current share price.