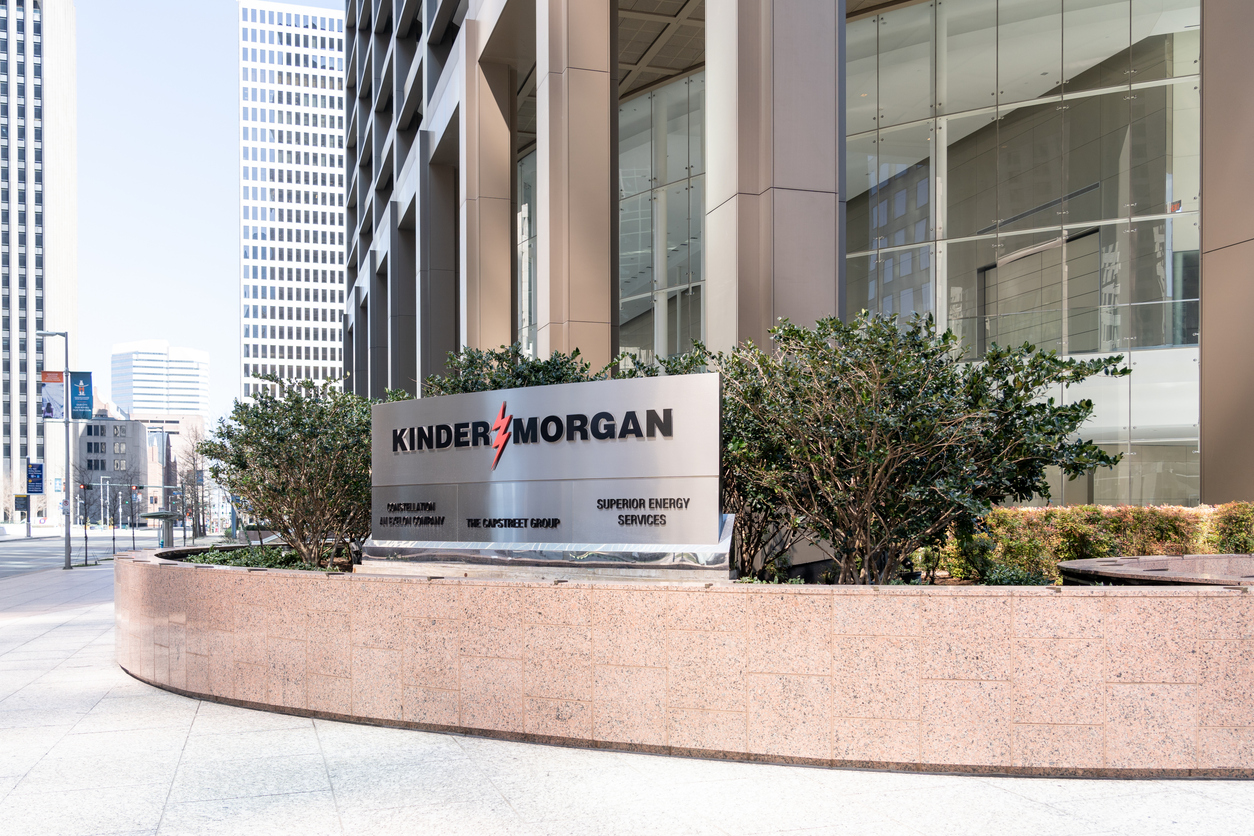
Thanks to the Iran conflict and the subsequent global energy crisis, the typically reliable but boring midstream specialist Kinder Morgan (KMI) has enjoyed a surge of cynical relevance. Since the start of the year, KMI stock gained nearly 16%, which really isn’t the norm. Basically, Kinder Morgan is the toll booth of the North American energy sector.
It doesn’t have the high-risk, high-reward profile of your pureplay upstream business or those entities involved in drilling and exploration. It also lacks the volatile edge of the downstream (refining) sector that can deliver either blistering gains or agonizing losses. Instead, Kinder Morgan operates a massive infrastructure that connects the two.