The Fed’s latest rate hike looks straightforward on the surface: inflation remains a problem, so policymakers are keeping pressure on the economy. There is reason to believe the FOMC remains behind the curve, as it has been since inflation reared its ugly head. But a case can be made that the committee is setting the market up for a massive rate cut. It takes some forward thinking (and a penchant for conspiracy theories), but raising interest rates amid economic headwinds could push the economy into stagnation, putting the Fed in a position to cut rates, perhaps by larger-than-normal increments, within the next few quarters. The more speculative version of the argument is that the Fed may be creating that room intentionally.
Oil Price Wild Card Sets Stage for Inflation Implosion
Oil prices aren’t the only cause of inflation, but they have contributed to this year’s acceleration, and the FOMC is all too aware. The risk for the Fed is that the market gives up oil’s Iran War premium, pulling headline inflation lower. As it stands, demand erosion, Strait of Hormuz workarounds, ramped non-OPEC production, and the eventual resolution of the conflict could eventually lead to a much looser supply balance.
A supply glut means lower oil prices, and the market will likely price it in long before it becomes reality. Some forecasts suggest oil prices could revert to long-term lows in the low $60 range by the middle of 2027. As it is, oil markets are in backwardation, as most participants don’t expect prices to stay high for long, with forward contracts reflecting the premium and long-term contracts not. WTI’s price action is also reflecting potential for a top, with resistance at $105 confirmed by September activity.
The question is why the Fed might do this. The initial reaction to September’s rate hike was minimal, as it was largely expected, and did little to impair business activity. They’ll need to hike rates another 50 to 75 basis points to really impair activity, and that much hiking is unlikely, given the oil price risk. What the quarter-point September hike did do, however, is give the FOMC extra ammunition for when inflation falls, enabling the aforementioned massive interest rate cut, when the timing is right.
The End Result—Unsticking the Housing Market
A massive interest rate cut is generally good for rate-sensitive markets, but which market will benefit most? Could it be the housing market? Long constrained by capacity, high prices, and high interest rates, a sudden rate drop, potentially leading mortgages to below 5.5%, might unstick the housing market. Unsticking the housing market will unleash broad-based economic activity and usher in a generational economic expansion.
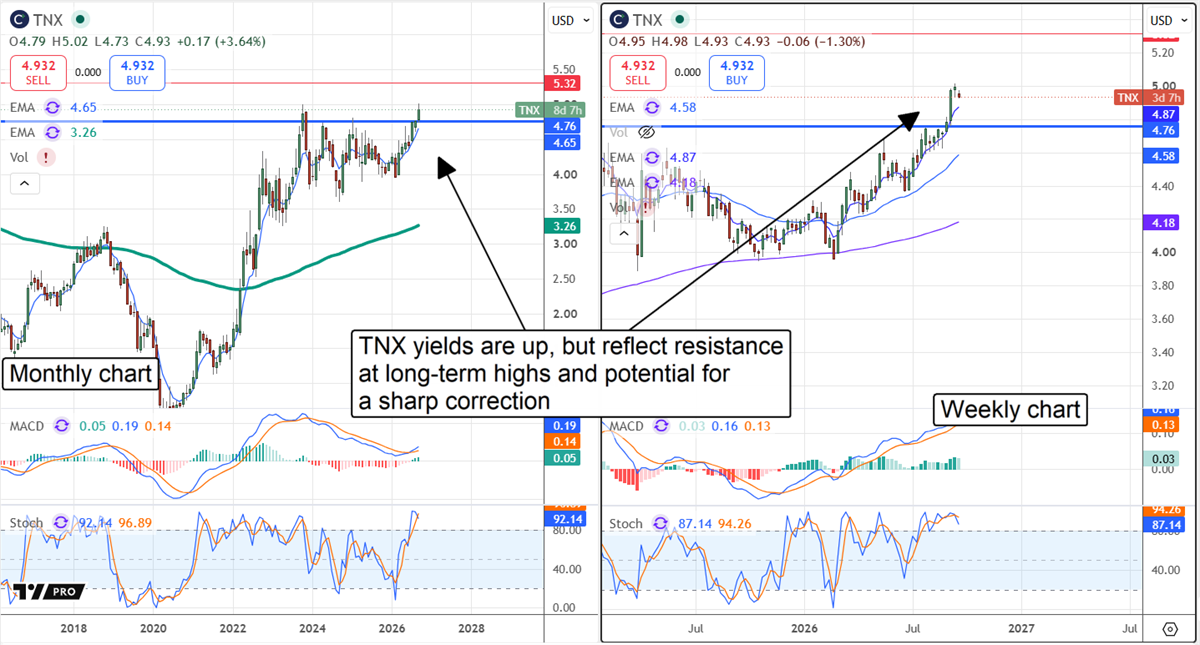
Yields on the 10-year Treasury foreshadowed the Fed’s September hike, rising to long-term highs, and may now be foreshadowing the interest rate ceiling. Market action for this instrument has hovered near long-term highs for several weeks, reflecting resistance at a critical level, with MACD divergences and oversold conditions on the monthly and weekly charts. There is no guarantee yields will start to fall (and bond prices to rise), but the technical setup strongly suggests a top is in.
Lennar (NYSE: LEN), for one, is well-positioned in the housing market to benefit from falling rates. It's leaned into efficiency, reducing overall costs and lead times, while gaining share nationally. Falling rates will drive accelerated growth, wider margins, faster cash flow improvement, and share buybacks. Until then, the company is leveraging its cash flow and balance sheet to aggressively reduce shares while they trade at multiyear lows.
What the Fed’s Rate Cut Means for the S&P 500
The rate hike presents hurdles for the S&P 500, but history shows the market tends to rise after the first hike in a rate-hiking cycle. While the initial response may be a correction, pullbacks are usually short-lived, and the market often gains over the subsequent 12 months of hiking because of underlying economic fundamentals. Today's fundamentals include resilient labor markets and consumer spending, expansion in the services and manufacturing sectors, and aggressive business investment driven by AI.
AI fears persist, but are not the problems the market makes them out to be. Software-as-a-service companies are defying logic and implementing AI faster than AI can disrupt their businesses, and the call to slow down frontier modeling is great news for cash flow. Frontier modeling and its infrastructure costs have dragged on cash flow across the industry, pushing many tech companies into negative cash flow, debt increases, and/or dilutive activities, which have impaired stock price performance. Slowing spending will allow these companies to monetize existing infrastructure, return to positive cash flow, free up capital for returns, and improve balance sheets, regardless of the Fed’s quarter-point hike.
The critical takeaway is that near-term volatility is expected, but the S&P 500’s uptrend is intact. Potential catalysts arrive in late October and early November with the onset of Q3 earnings and the midterm elections. The nearer-term factors to watch are declining oil prices and persistent signals that the AI build continues.
The article "Is the Fed Playing Chess With Rates—Or Just Behind the Curve Again?" first appeared on MarketBeat.