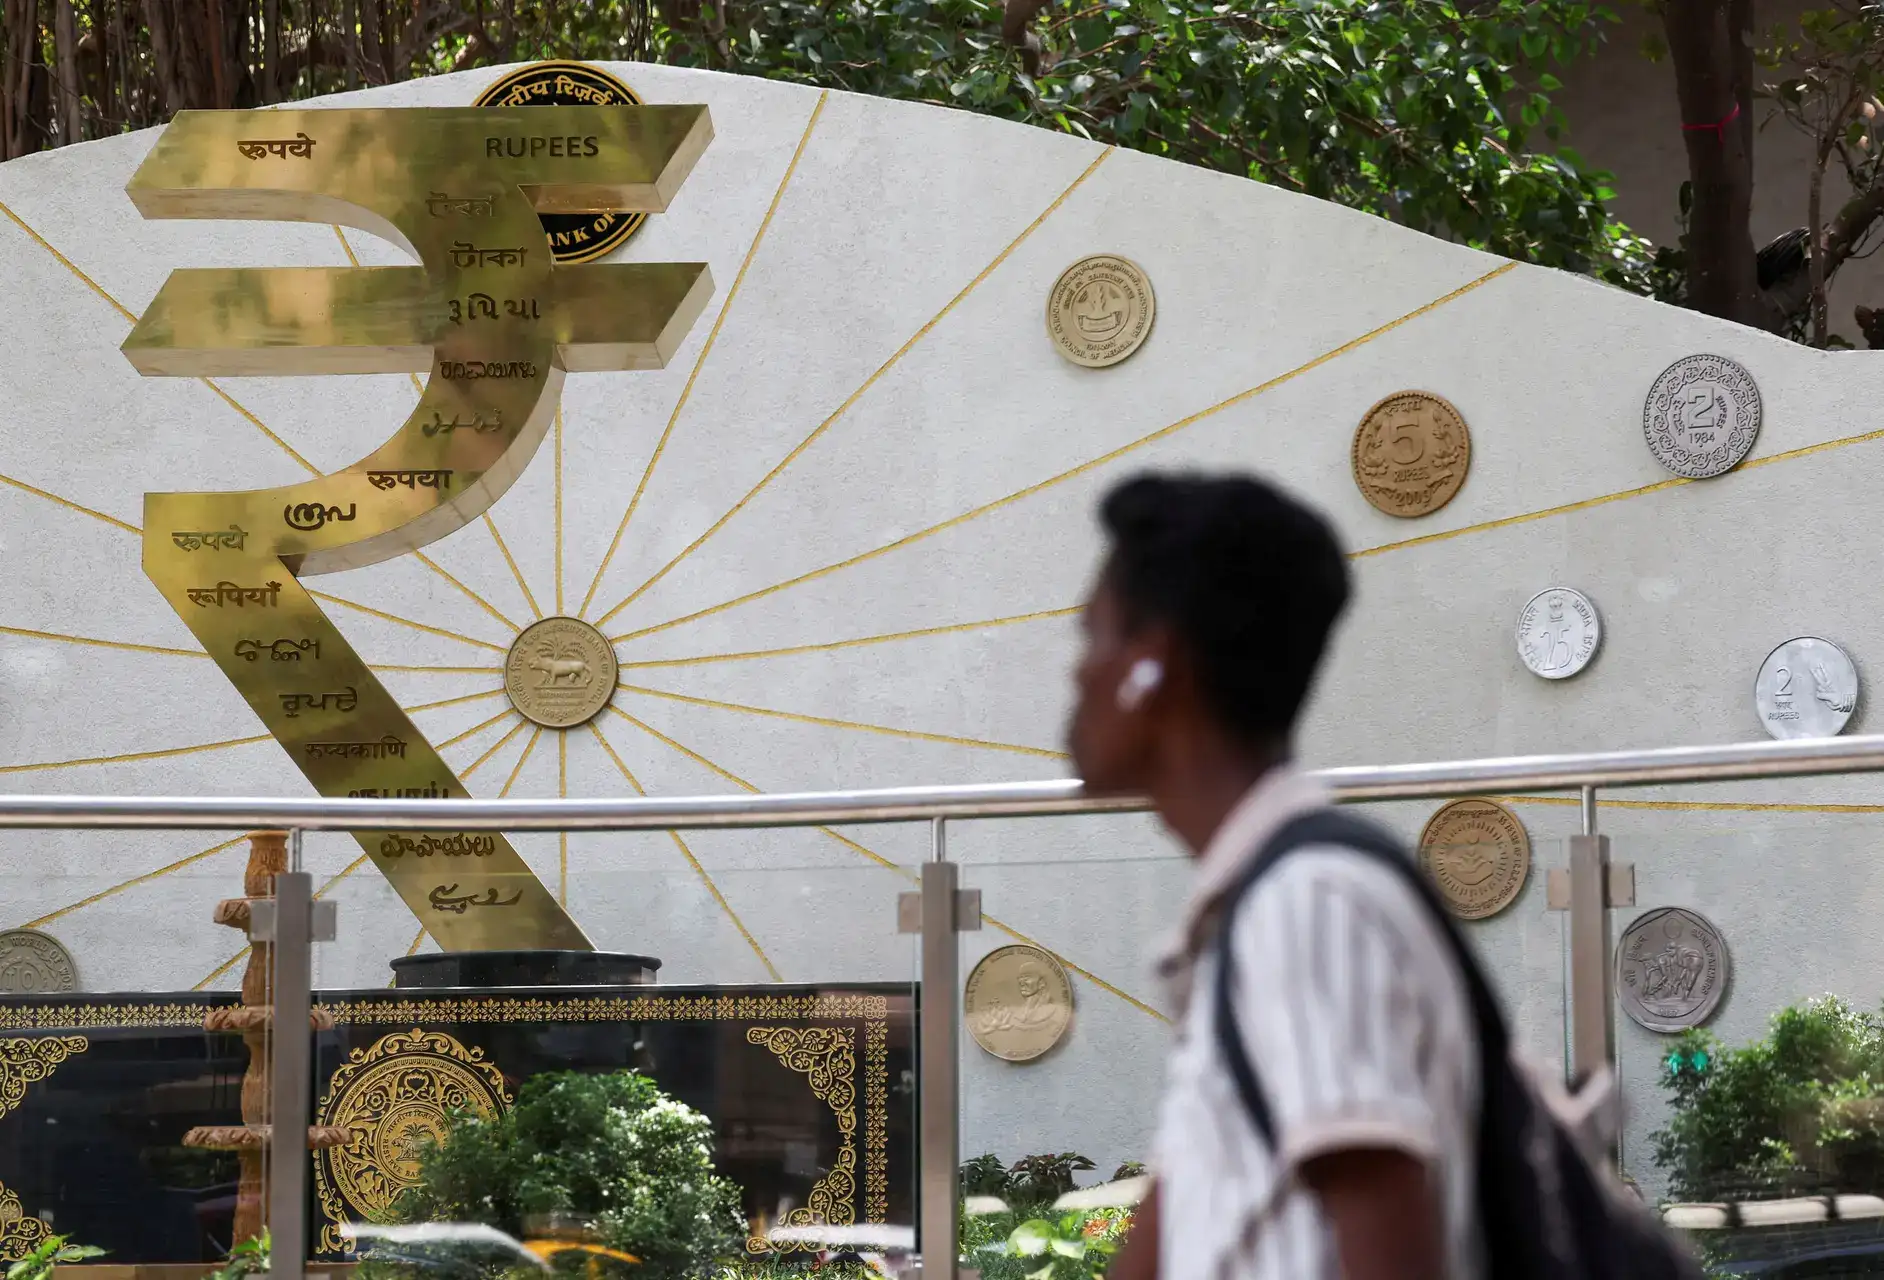
India has announced a raft of measures to revive global confidence in the sagging rupee. The best thing about the package announced Friday is what’s not in it: capital controls.
During the 2013 currency crisis, authorities had slashed the dollar amount that individual savers could legally take out of the country in a year. This time, they wisely left the $250,000 limit untouched. Nowadays, when that money is widely used for everything from funding foreign education to buying stocks in the US and homes in Dubai, such a step would have been deeply unpopular.