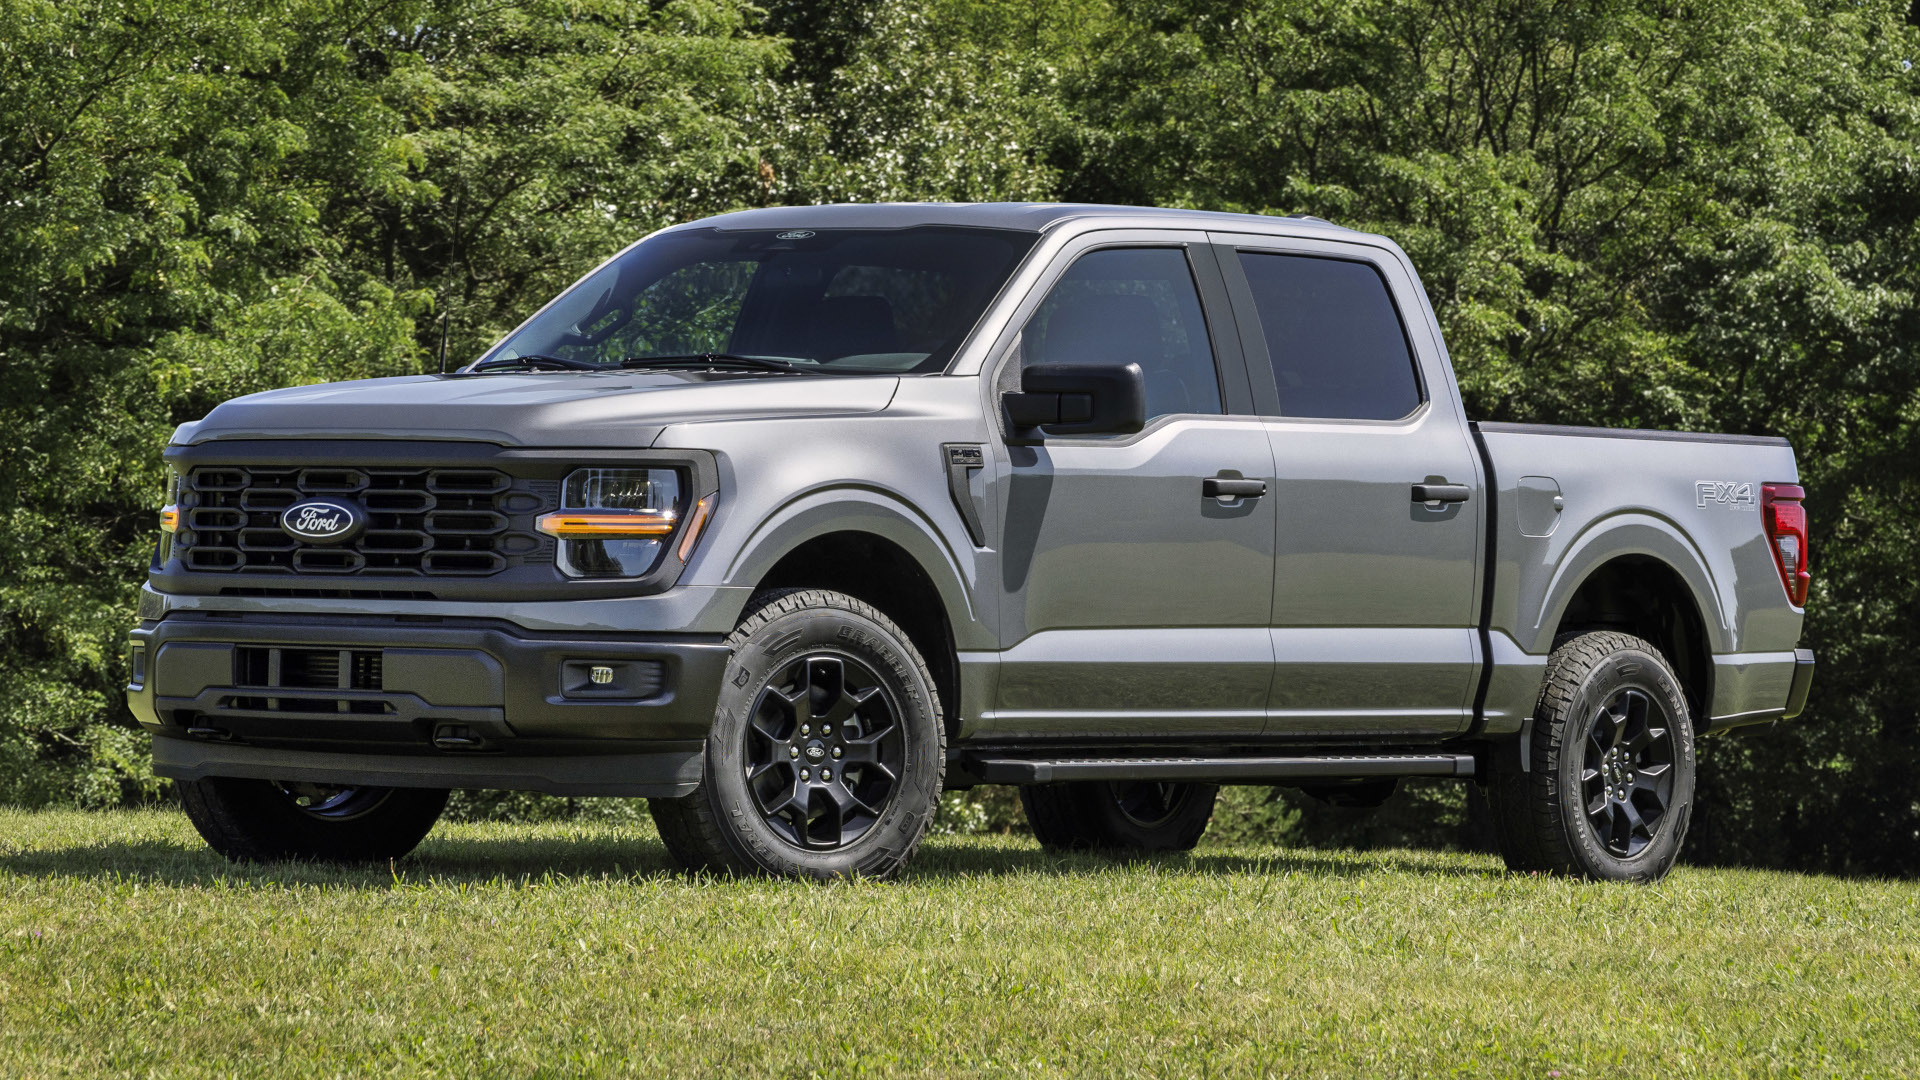
If you’re looking to buy a new car, you’re probably going to finance a large part of it unless you’ve saved a bundle for a down payment. According to The Guardian, auto loans rank as the third-largest form of consumer credit in the U.S., following mortgages and student loans and make up 85% of all new car purchases.
Before you put the pedal to the test model metal, you’ll need to figure out factors like the amount you can put toward a down payment, what you can get on a trade-in and the state tax you’ll pay. And, of course, you’ll need to factor in the interest rate you’re going pay or the cost of borrowing money, expressed as a percentage of the remaining loan balance.