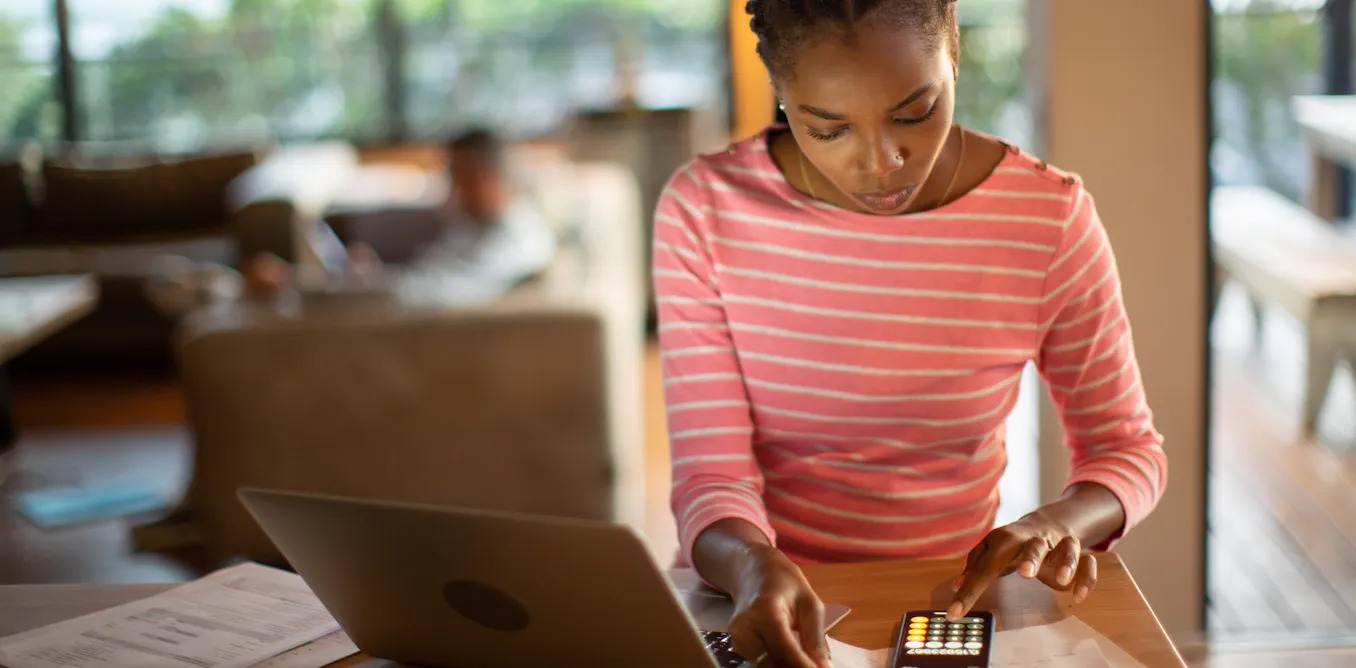
When interest rates rise, most people feel the financial pinch as repayments for home loans, car purchases or personal loans increase. This leads to less money for everyday spending and tightens the household budget.
Middle- and upper-income households tend to hold secured debt such as property, which builds wealth. Lower-income households are pushed into debt as they try to maintain their consumption levels. The result is that the impact of rising interest rates is even more significant for lower-income households. They may have to reduce spending on necessities to service interest payments. Even renters wanting to become home owners are indirectly influenced by rising interest rates, as home loans become less affordable.