The Iran war has thrown the global oil market into turmoil, disrupting oil routes and supply across the Middle East. It has also exposed the risks of relying too heavily on concentrated supply sources. Yet these same issues have also pushed energy producers to think harder about production capacity, exploration, and investment in longer-term projects outside the most exposed areas.
For Halliburton (HAL) and SLB (SLB), two of the world's largest oilfield-service companies, the bigger opportunity could come after the disruption. As operations restart, that could translate into more drilling, well intervention, production optimization, and infrastructure work. These are exactly the kind of services these two companies provide.
However, only one is better positioned to turn the changing energy landscape into long-term growth.
The Case for Halliburton
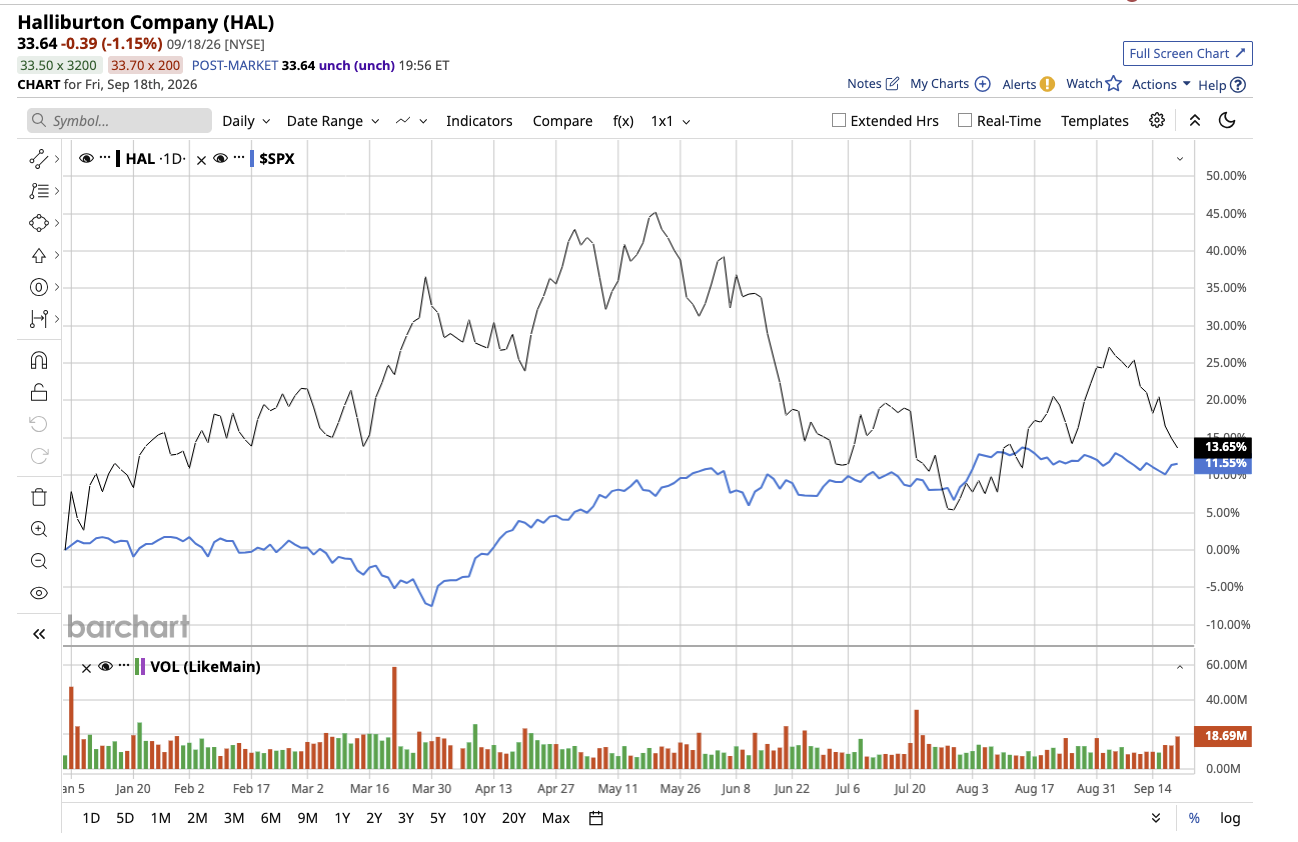
Halliburton is an oilfield-services and technology company that helps energy companies drill wells, complete them, and increase production from existing assets. So far this year, HAL stock has climbed 13%, outperforming the broader market gain.
It operates under two major business segments:
- Completion and Production: It includes services such as stimulation and well intervention.
- Drilling and Evaluation: It covers drilling-related services, wireline, and other technologies used to construct and evaluate wells.
The oilfield recovery has begun benefiting Halliburton. In the second quarter, the company generated $5.7 billion in revenue, a 6% sequential increase. Completion and Production revenue rose 6% sequentially to $3.2 billion, with operating income increasing 8% to $474 million. Drilling and Evaluation revenue increased 5% to $2.5 billion, although operating income declined 4% to $338 million because software sales rolled off seasonally.
The company added 30 rigs to the U.S. land market in the quarter, supporting a recovery in drilling and evaluation activity. However, management also said that the North American market will require increasingly sophisticated technology and greater service intensity to maintain and eventually increase production. Halliburton indicated that its worldwide growth engines are on track to generate $2.5 billion to $3 billion in annual revenue by 2028, with opportunity for further development. Management highlighted stronger activity in unconventional resources, offshore projects, and well intervention.
Importantly, the company has secured major awards in Iraq, Saudi Arabia, and Suriname, including work involving approximately 285 wells for Saudi Aramco and a major integrated well-construction contract for TotalEnergies' (TTE) GranMorgu development in Suriname.
Halliburton spent $235 million on capital expenditures in Q2 and expects full-year 2026 capital spending of about $1.1 billion. Nonetheless, it also returned to shareholders a quarterly dividend of $0.17 per share and repurchased roughly $200 million of stock during the quarter. It offers a forward dividend yield of 2.02%. Overall, Halliburton offers investors a combination of improving oilfield activity, international expansion, cash generation, and shareholder returns.
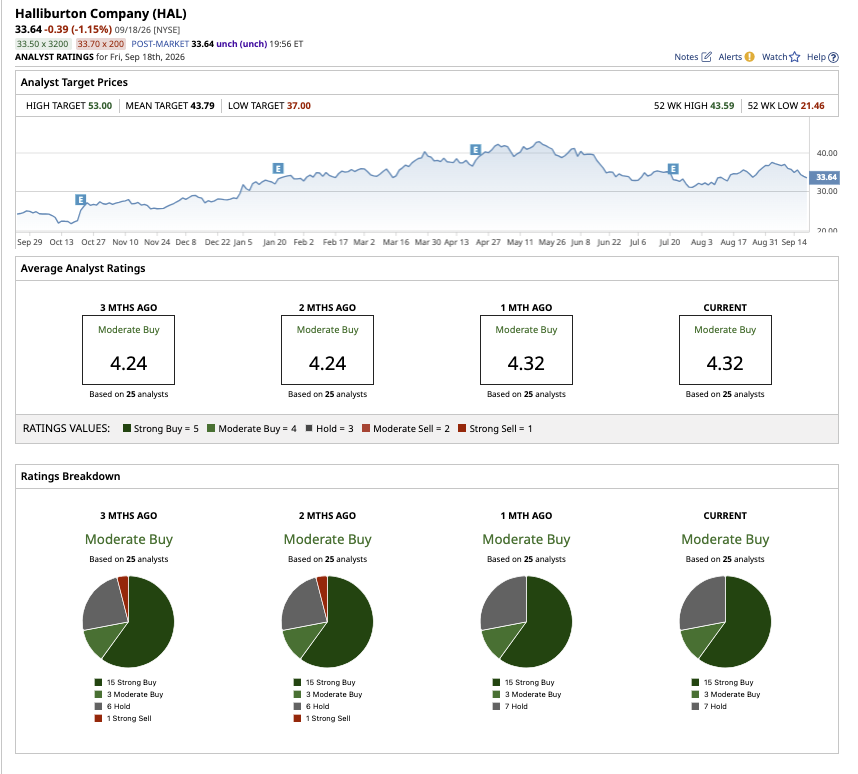
On Wall Street, HAL stock holds a consensus “Moderate Buy” rating. Of the 25 analysts that cover the stock, 15 rate it a “Strong Buy,” three say it is a “Moderate Buy,” and seven rate it a “Hold.” The average target price of $43.79 for the stock suggests a potential upside of 30.17% from current levels. The high-end estimate of $53 suggests the stock can climb by 57.5% over the next 12 months.
The Case for SLB
SLB is also an oilfield-services and technology company but on a much broader global platform. Its core business is to help customers evaluate reservoirs, drill and construct wells, and improve production and recovery.
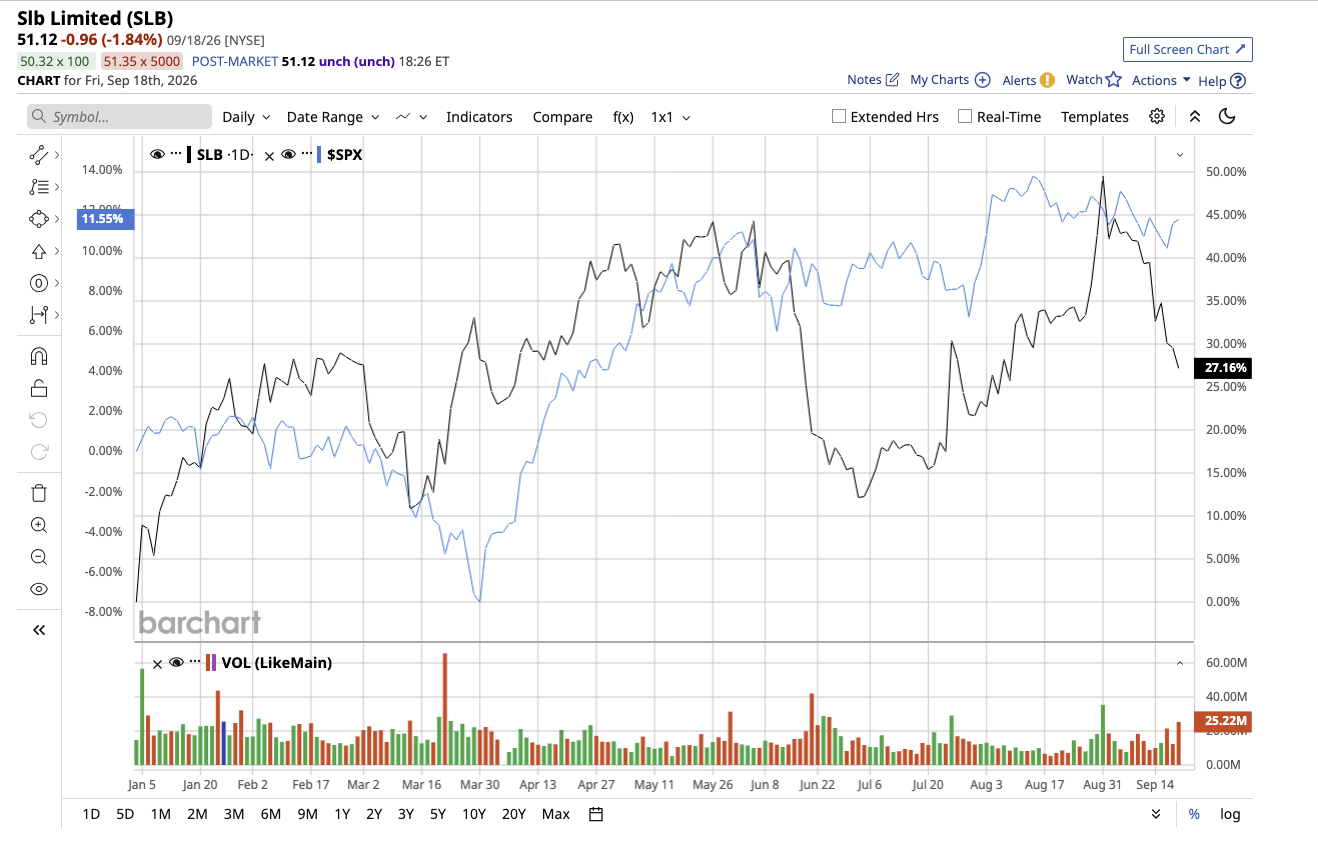
So far this year, SLB stock has climbed 27%, surpassing the S&P 500 Index ($SPX) gain of 11.5%.
In the second quarter, SLB’s revenue climbed 5% YOY to $8.97 billion, while adjusted EPS jumped 30% to $0.52 from the year-ago quarter. The company also generated $716 million of free cash flow. Excluding the Middle East, its offshore activity strengthened in Latin America, Europe and Africa, and Asia. SLB sees international and deepwater activity accelerating, with final investment decisions for long-cycle projects expected to rise around 30% YOY in 2026. Over the next two years, SLB also has an ambition for its subsea bookings to reach $9 billion. Basically, the company benefits in two ways: one through the short-cycle exposure from production recovery, the other from a longer-cycle exposure from deepwater projects.
Interestingly, beyond traditional oilfield services. SLB has multiple avenues for growth with digital technologies, artificial intelligence, production optimization, offshore and subsea systems, and its rapidly expanding data-center business. Its Data Center Solutions generated $186 million of revenue in Q2, up 33% sequentially and 80% YOY. Management expects the business to end 2027 at an annualized revenue run rate of more than $2 billion.
While the business is small compared to its oilfield operations, the diversification matters for its long-term investment case. This gives SLB a growth avenue that is not dependent entirely on drilling activity or crude prices.
SLB is also a dividend stock, offering a forward dividend yield of 2.3%. What makes SLB better is that it also supports dividend growth. It has been increasing its dividend for the past six years, including the most recent 3.5% hike to its quarterly dividend. The company also repurchased $648 million worth of shares in Q2. Earlier in the year, SLB committed to repurchasing shares and pay dividends totaling over $4 billion to shareholders in 2026.
Overall, SLB offers investors a combination of international oilfield exposure, deepwater growth, production recovery, Digital, AI, and a rapidly scaling data-center business. It runs a company that has more than one way to grow as the energy cycle develops.
Which is the Better Buy Now?
Although Halliburton has a strong recovery story, SLB is the better buy now. It has a broader long-term growth platform, with exposure to both short-cycle production recovery and longer-cycle deepwater investment. At the same time, SLB is returning substantial cash through dividends and buybacks.
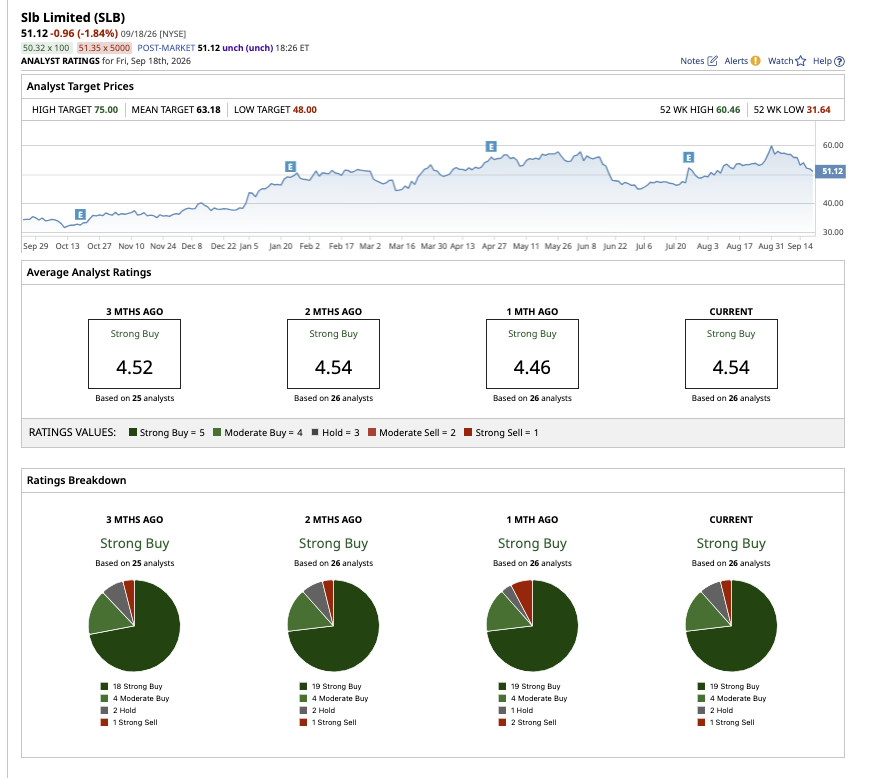
On Wall Street, SLB stock holds a consensus “Strong Buy” rating. Of the 26 analysts that cover the stock, 19 rate it a “Strong Buy,” four say it is a “Moderate Buy,” two rate it a “Hold,” and one rates it a “Strong Sell.” The average target price of $63.18 suggests a potential upside of 23.6% from current levels. The high price estimate of $75 suggests the stock can climb by 46.7% over the next 12 months.