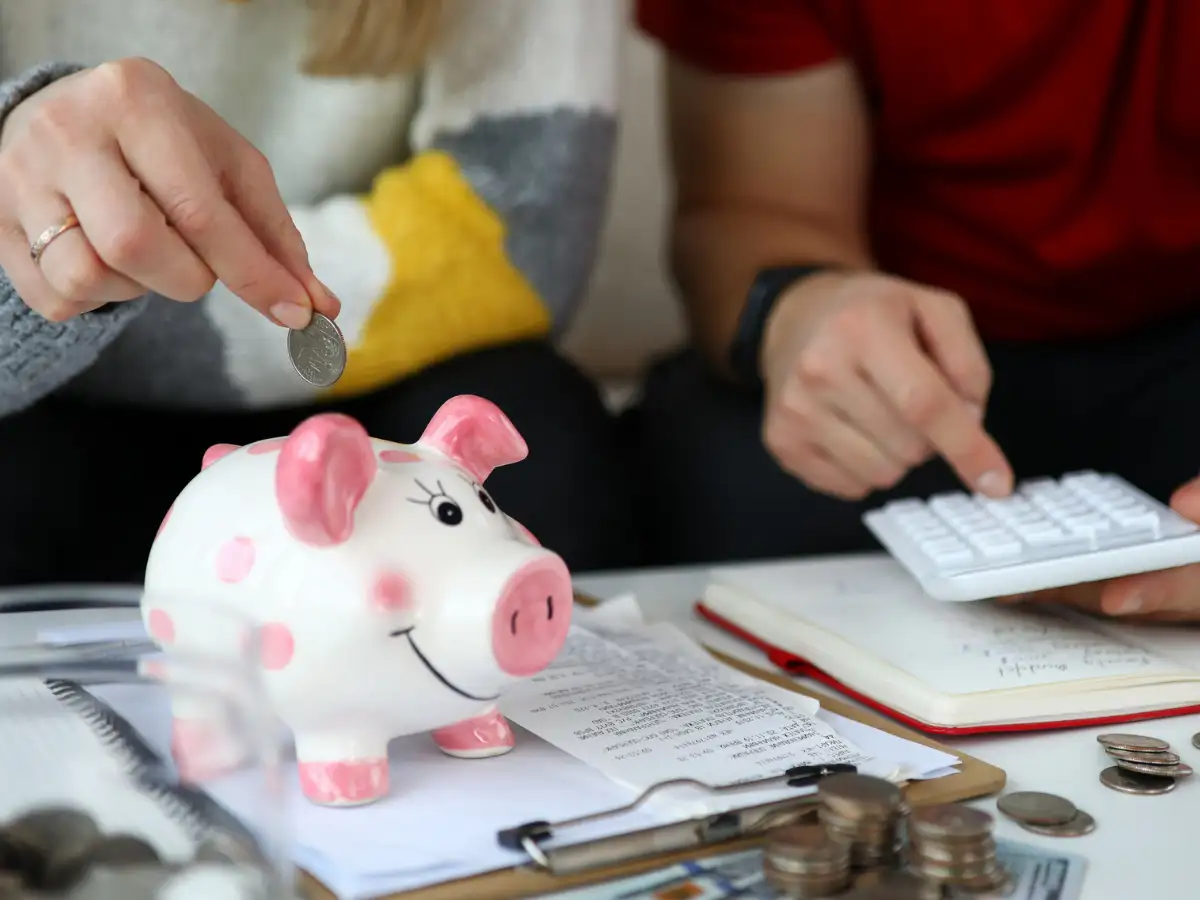
Some themes recur in this column. The idea of a unique money personality is one of them. Our attitudes towards money are shaped by too many factors to list here. We may think of our life’s experiences as the dominant one, but even this is tough to map straight-line connections. If we have grown up in a frugal household, our memories hold equal potential to make us either frugal adults or rebellious spendthrifts. We have seen repeating credit card defaults from people who we assume would have been shamed and scarred by earlier instances of failing to pay their dues; and we see those who cut up their credit cards and never use them after a default. The discussion I would like to open is this—what happens when one makes financial decisions for another, and why the agency or freedom to make decisions is critical in household personal finance.
Let me underline another recurring theme in this column to provide a framework. There are two important features of money that shape our attitude towards it. One, money is a limited resource for the majority of us. Two, alternative uses for money can always be found. We call this opportunity cost. We spend our personal finance journey figuring out how to work with these money features. We have to make choices about where to earn, spend, save, invest and give money. The choice we make precludes other choices because there is only a limited amount of money or ability to include all. The caution about choices and regret about what we chose are more common than carefree decision-making that fills us with pride. Therefore, the question of who makes these choices directly impacts the outcomes, and how we feel about them.