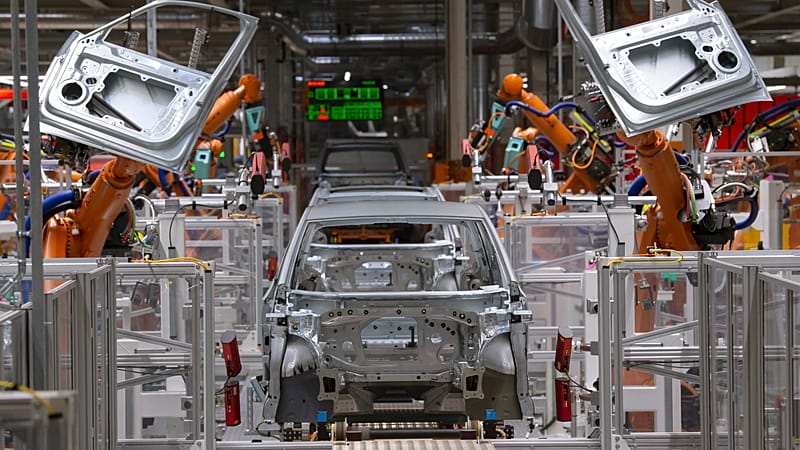
Europe's carmakers rely on a narrow group of countries, suppliers and processing hubs for the chips, magnets and metals their vehicles need, and that dependence is the biggest supply-chain risk facing automotive manufacturing in the bloc, a new study found.
The analysis, carried out by the Czech and German arms of consultancy EY at the request of the European Automobile Manufacturers' Association (ACEA) and published on Tuesday, scored ten critical materials and components against six factors that could constrain supply.
Concentration of supply scored highest, at 4.6 on a five-point scale.
Five inputs stood out as the most vulnerable: semiconductors, silicon, tungsten, neodymium-iron-boron magnets used in electric motors and wiring harnesses, the cable bundles that connect a car's electrical systems.
The industry has felt the risk before.
Chinese curbs on rare-earth exports shut several European production lines last year, according to suppliers' association CLEPA, while a supply crisis at chipmaker Nexperia prompted ACEA to warn of potential "significant disruption to European vehicle manufacturing" last October.
For six of the ten inputs, the riskiest stage is refining and processing the minerals rather than extraction.
China dominates rare-earth refining and magnet production as well as gallium and germanium processing, while Taiwan and South Korea are major chipmaking hubs.
"Europe's main challenge is not only access to raw materials. More critical are the shortages of processing capacity, qualified suppliers and specialised expertise," said Zdeněk Dušek, automotive consulting partner at EY Czech Republic.
"These capabilities cannot be built within one or two years," Dušek added.
Competing with AI
Electrification sharpens the problem.
Electric cars need fewer conventional parts but more semiconductors, power electronics and critical materials, putting carmakers in competition with AI, data centres, defence and clean energy for the same supplies.
The shift to electric vehicles increases competition with other industries for the same critical materials and components by about 15%, the study estimates.
Carmakers are often small customers in these markets, accounting for 17% of end demand for semiconductors and just 3% for gallium, a metal used in power electronics and radar.
Increased competition and concentrated supply chains are pushing prices higher. Gallium, for instance, has risen more than elevenfold in price since 2016, from about $197 to around $2,269 per kilogram, amid growing demand fuelled in part by AI development.
"Carmakers are increasingly competing for these supplies with other industries, such as manufacturers of chips for artificial intelligence," said Martina Nimčová, a manager in business consulting at EY Czech Republic.
Self-driving ambitions add to the pressure, as autonomous functions increase reliance on chips, sensors, gallium and germanium, the study notes.
For instance, Volkswagen partnered with Uber to deploy a fleet of autonomous, all-electric "ID. Buzz AD" microvans, with rides on the Uber platform planned to begin in Los Angeles in late 2026 before scaling to thousands of vehicles.
Meanwhile, Stellantis aims to start producing robotaxis for Uber in 2028 using Nvidia's self-driving technology.
No quick fix
The study outlines four scenarios in which disruptions around the world could leave European carmakers short of vital supplies: disruption to electronics supplies from Taiwan, resource nationalism in Asia, strained trade corridors in the Americas and instability along Africa's mineral export routes.
Logistics is the common thread, and even a short interruption can halt just-in-time production lines, as the 2021-2022 chip shortage showed.
"Expanding capacity for the most critical inputs often takes more than five years," Dušek explained, adding that the advantage goes "not to those with the best strategy on paper, but to those who act earlier and can scale capacity more quickly."
Full self-sufficiency is not realistic, the study concludes.
Instead, it urges Europe to speed up permitting and qualification, target investment at the tightest bottlenecks, diversify suppliers and logistics routes, monitor supply chains more closely and give private investors long-term demand certainty.
"This isn't just risk management. It's about safeguarding Europe's industrial strength," said Sigrid de Vries, ACEA's director general.
With new capacity measured in years, the study's message is that the time to act is before the next shortage, not during it.