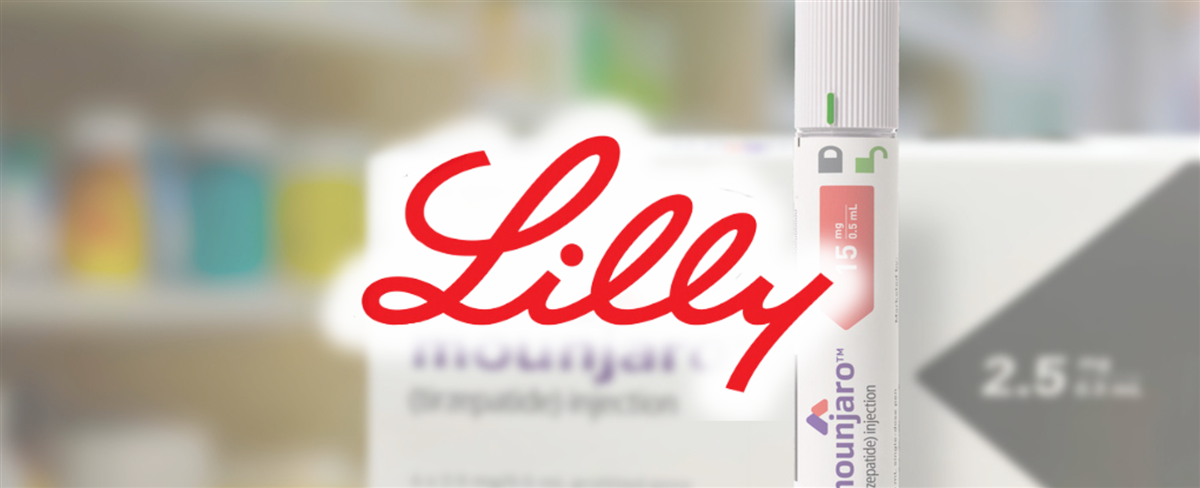
Eli Lilly & Co. (NYSE: LLY) is a major global pharmaceutical company in the medical sector. The company made headlines with its dominant GLP-1 drug, Tirzepatide, sold as Mounjaro for type 2 diabetes and Zepbound for obesity. While there are many potential contenders in clinical trials, the current GLP-1 market is a duopoly that Eli Lilly dominates with Novo Nordisk A/S (NYSE: NVO), maker of Semaglutide sold under Ozempic and Wegovy brands. Additionally, Lilly has a robust pipeline led by its recently FDA-approved and launched treatment for Alzheimer's disease, Donanemab, sold as Kisunla. Mirikizumab is a treatment for Crohn's disease, and Lebrikizumab is for atopic dermatitis and asthma. Pirtobrutinab is a next-generation BTK inhibitor.
Record sales of its GLP-1 drugs drove Lilly’s stock to a new all-time high of $972.59 in 2024 but have since fallen 17.75% as of Jan 10, 2025. Lilly authorized a $15 billion stock buyback on Dec 9, 2024. For bullish investors, this pullback may be the opportunity they have been waiting for. Here are four reasons not to look a gift horse in the mouth and consider taking a position in the company on this pullback.