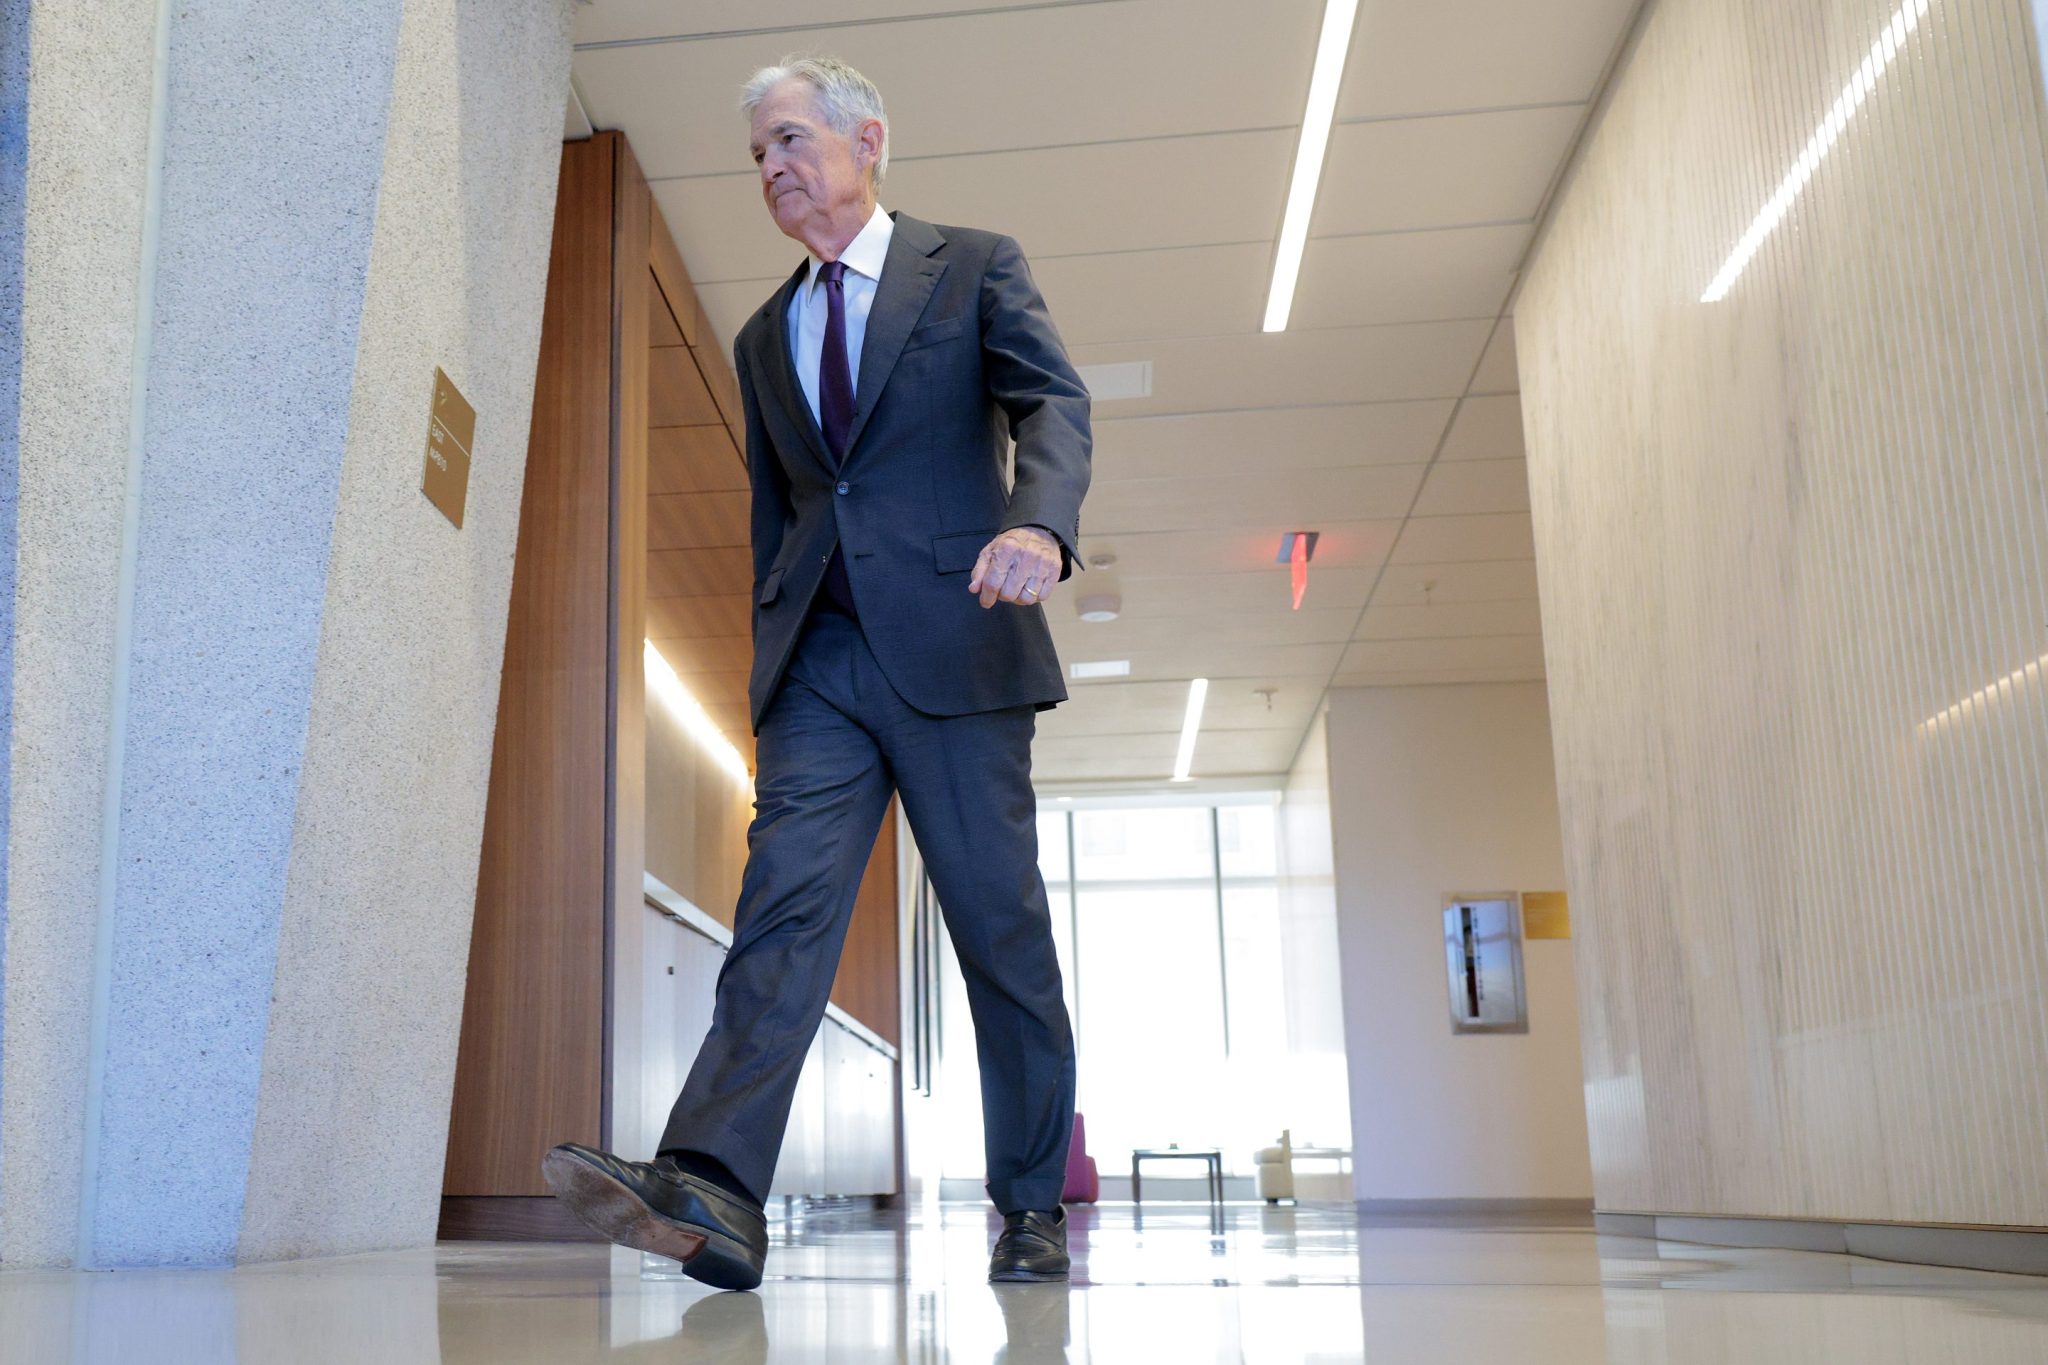
Here we go again. It’s Federal Open Market Committee (FOMC) meeting week, and Chair Jerome Powell is likely to once again disappoint the White House by announcing a hold to the base interest rate.
How fierce the reaction from the Oval Office will be is anyone’s guess, but markets are fairly convinced that the two-day conference concluding tomorrow will result in the interest rate being held steady in the range of 3.5% to 3.75%. Per CME’s FedWatch barometer, there’s a only a 2.8% likelihood of a cut tomorrow, even by the smallest increment of 25 basis points.
But while investors have reached a general consensus on the outcome of this week’s deliberations, they’re not quite so in line on the fiscal path for the rest of the year. Many economists, for some time now, have been expecting 2026 to be the year of further easing.
Their reasoning points to a weakening labor market and relatively low pass-through thus far from the White House’s tariff regime. In addition, Chair Powell will be replaced in the spring by a candidate nominated by President Trump, who has already said he wants a dovish individual at the head of the Fed.
Dissenters to that narrative include investment bank Macquarie, where North America economists David Doyle and Chinara Azizova see the Fed’s next move as a hike to the base rate—potentially in the final quarter of this year.
“Underpinning this is our belief that the labor market is improving, and that unemployment will decline ahead on a trend basis,” the duo wrote in a note seen by Fortune this week. “A key risk to this view is the potential for an incoming Fed chair to sway the committee in a more dovish direction. However, we believe this risk is mitigated by a potential shift in the new chair’s incentives once they assume the role.”