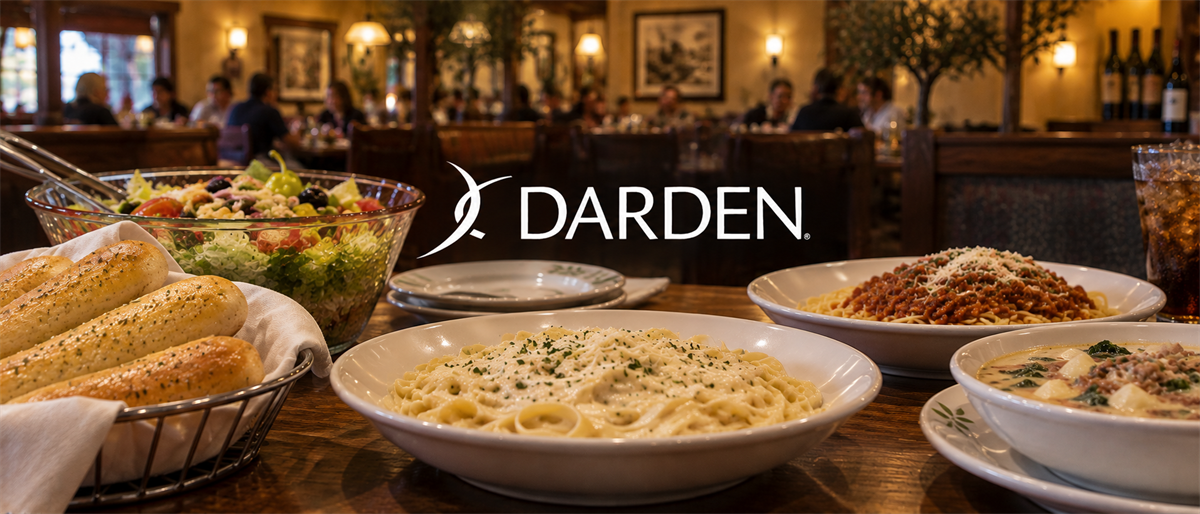
Darden Restaurants’ (NYSE: DRI) late-September post-earnings release price pullback could be a sell-the-news, buy-the-dip event because the strengths were expected. Investors should focus on the strengths: a portfolio of well-known, market-leading brands in key categories, including niche fine dining, which is about as good as it gets. Tepid results don’t necessarily mean weak results when analysts forecast industry-leading growth and sufficient profitability to sustain financial health, capital returns, and the uptrend in stock prices.
As always, the brand, management, and results influence stock-price valuation and outlook, but cash flow and capital returns drive it. In this case, capital returns include dividends and buybacks, providing significant leverage, even with share prices trading near record levels. Darden’s dividend annualizes to about 3.1%, and aggressive share buybacks compound it. Trailing-12-month (TTM) activity reduced the count by 2.7% as of Q1 fiscal year 2027 (FY2027).