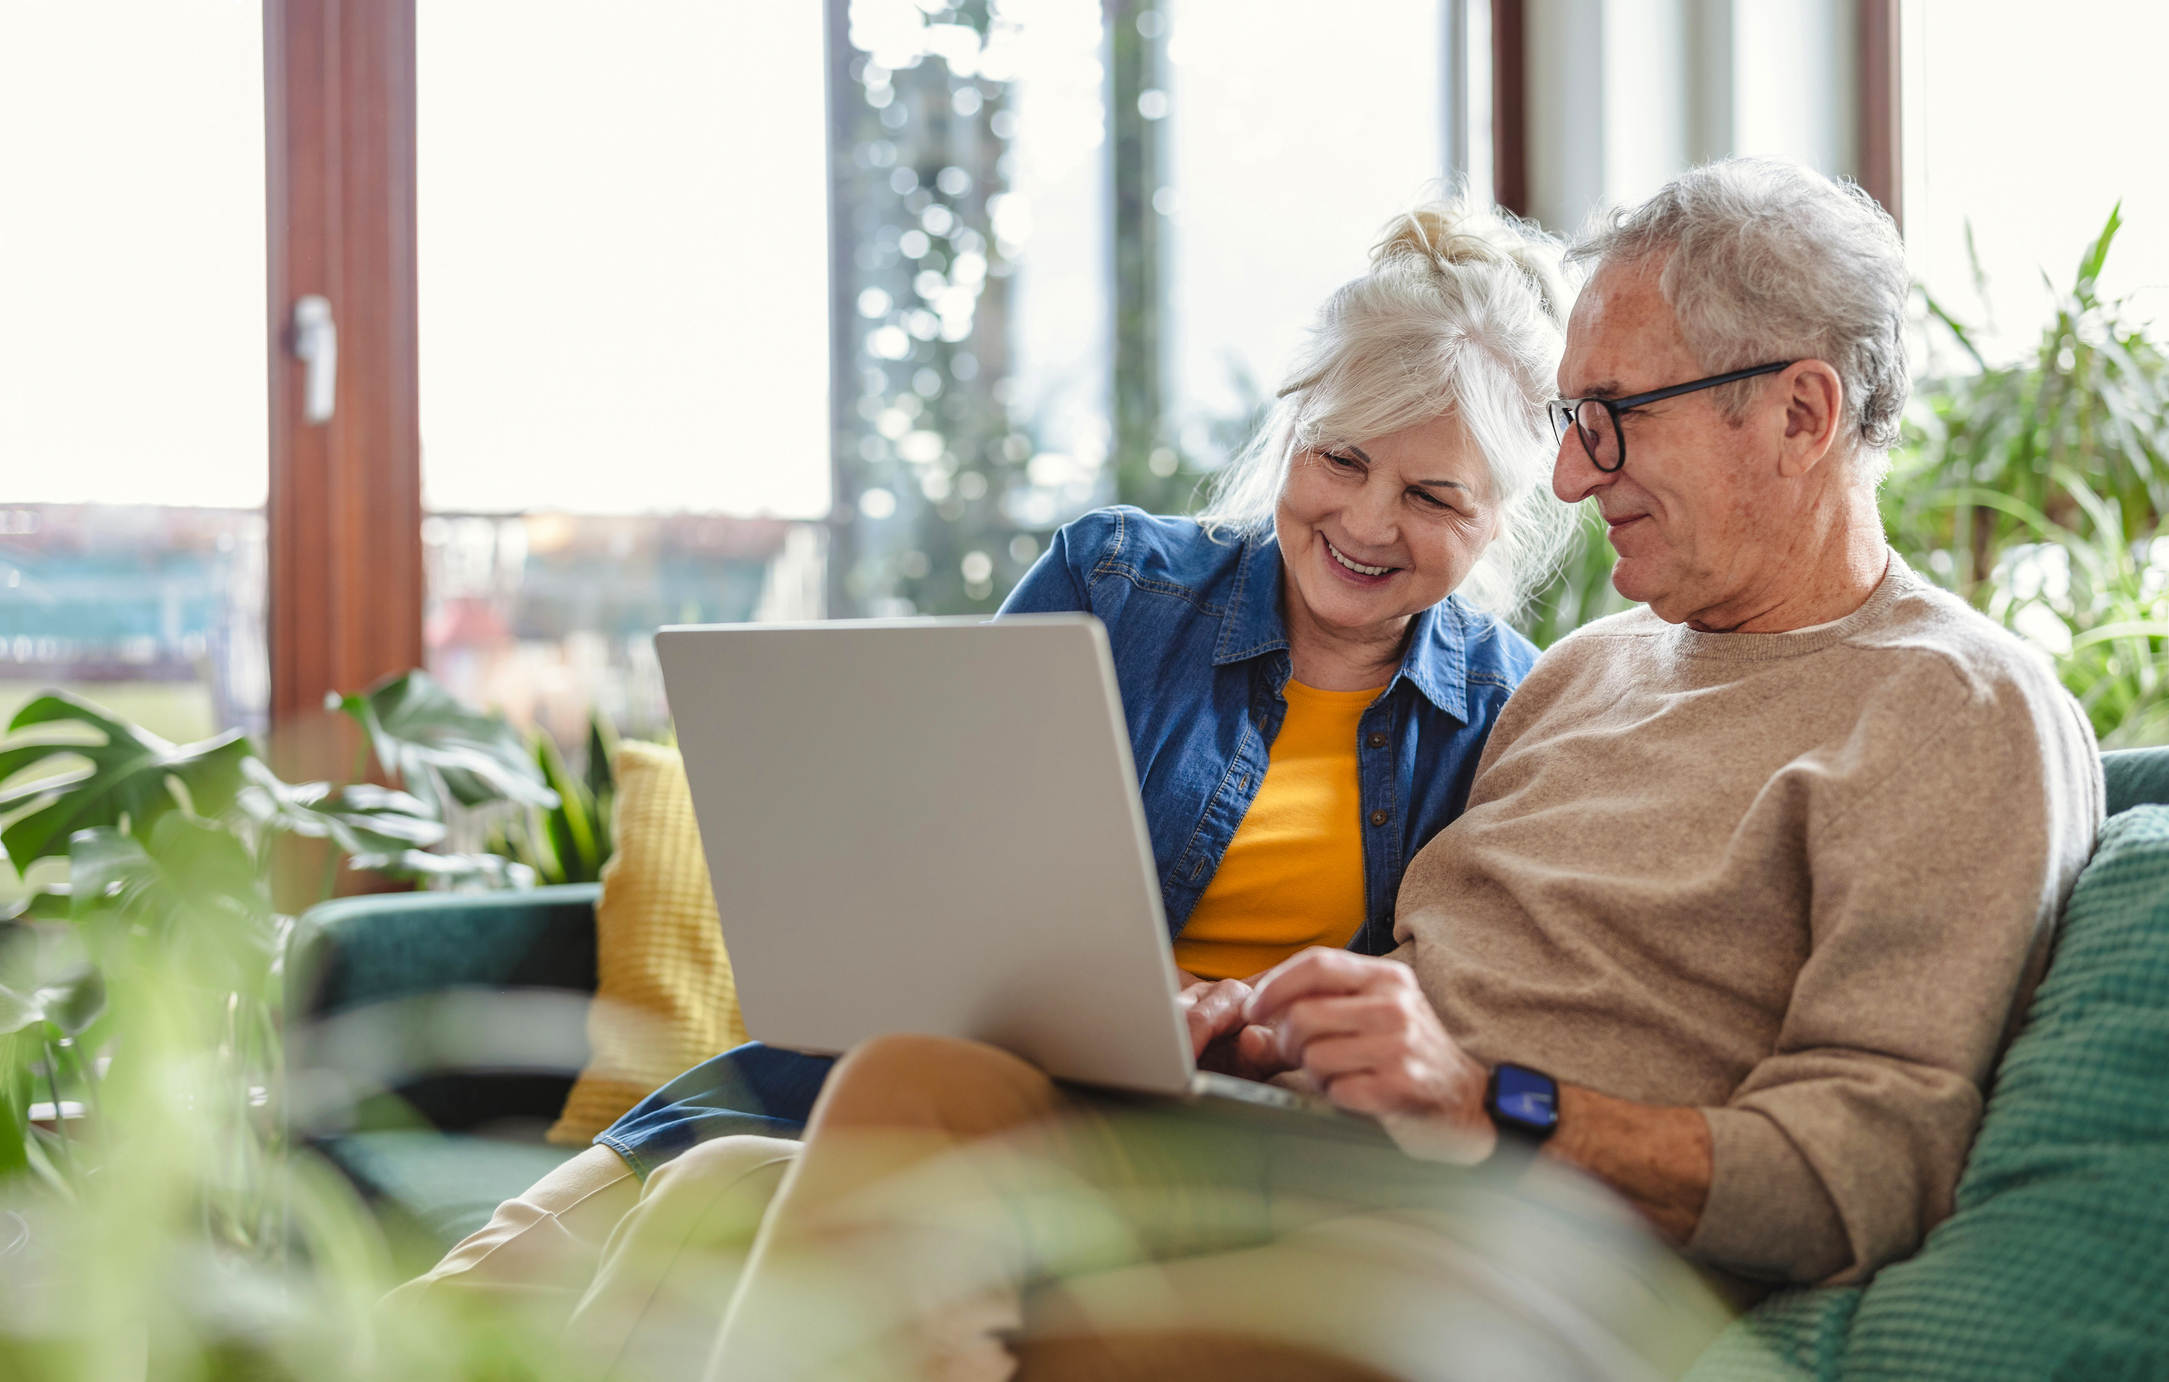
If you’re over 65 and still working, and you are currently covered by an employer health insurance plan (through you or your spouse), it may make sense to sign up for Medicare now. But, as long as you are actively employed, you can also delay enrollment in Medicare without paying a late enrollment penalty, and your spouse can also remain on your employer plan past age 65.
Although enrollment could reduce your out-of-pocket costs and gaps in coverage, it’s best to look at all the potential mistakes you could make before deciding.