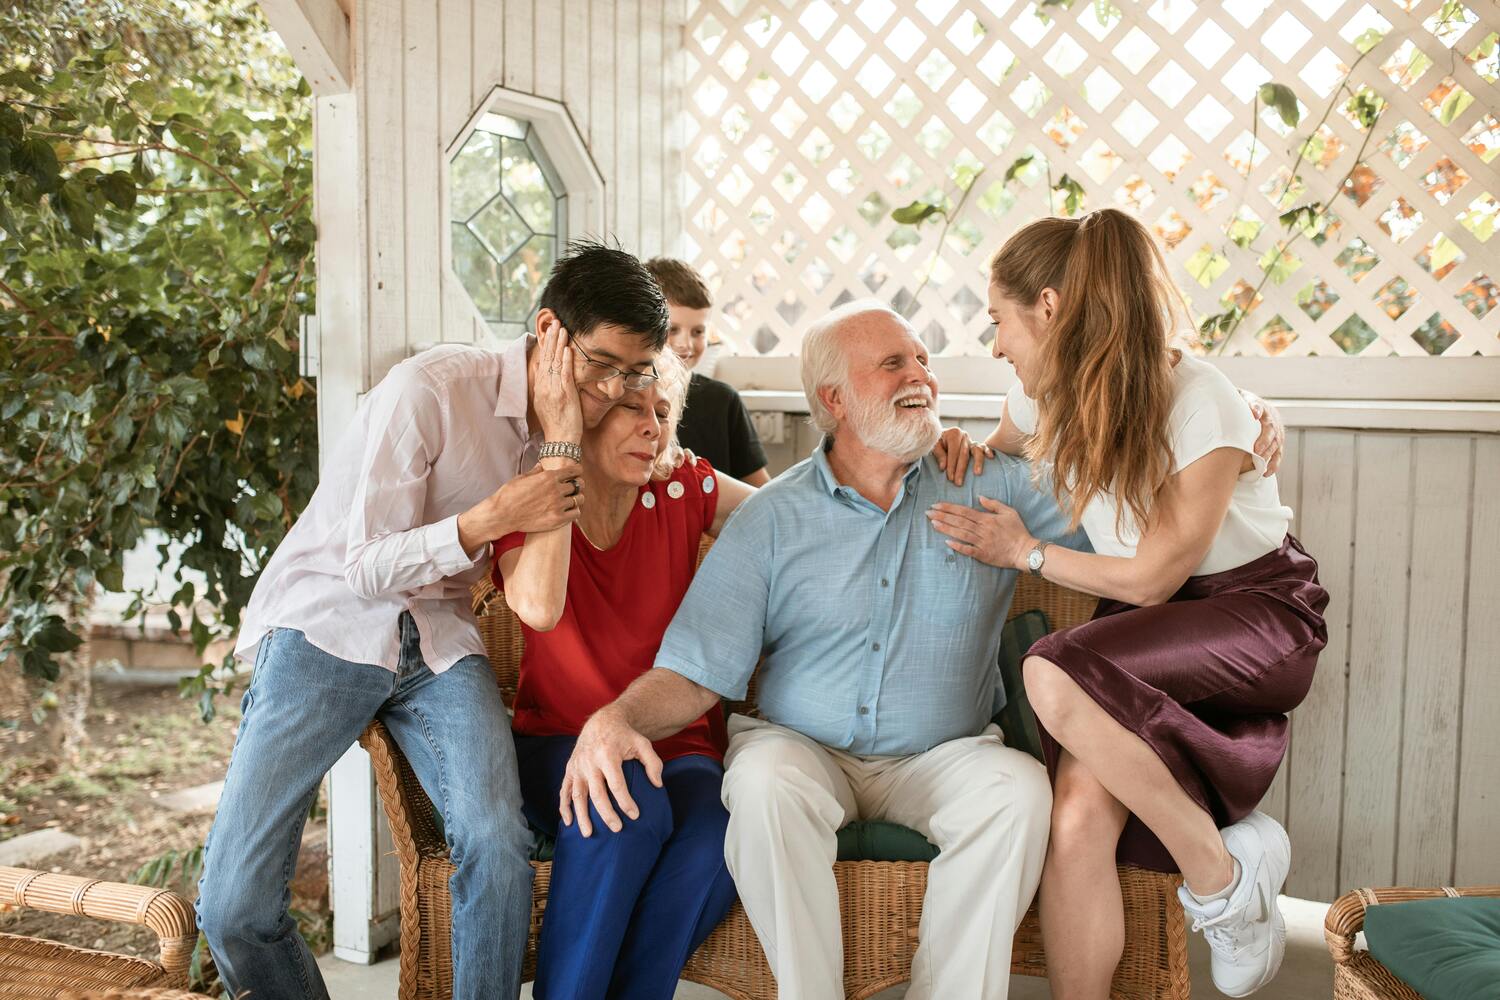
When money changes hands between family members, it often comes with good intentions and bad paperwork. What starts as a simple gesture–helping your adult child buy a home, loaning your sister money to start a business, or giving your nephew a hand with college–can turn into a legal and financial mess if things aren’t handled the right way. Family loans blur the line between personal generosity and legal obligation, and when repayment expectations aren’t crystal clear, relationships can fracture and lawyers can get involved.
The truth is, lending to loved ones comes with risks you won’t face with traditional lenders. From tax complications to inheritance disputes, even the most innocent arrangement can backfire. Here are seven common ways a family loan can spiral into a legal nightmare and how to avoid them.