The United States and other governments around the world are prioritizing military modernization, building up their capacity for nuclear deterrence, enhancing missile defense capabilities, and generally investing heavily in defense. A move toward a more militarized world may mean investors can capitalize on both larger defense giants and smaller companies with the potential for major growth.
When seeking significant return potential in defense, investors may want to look for firms with a unique technological niche and a distinct position within the defense supply chain, as well as significant operational updates or other signs of business momentum. BWX Technologies Inc. (NYSE: BWXT), Mercury Systems Inc. (NASDAQ: MRCY), and Howmet Aerospace Inc. (NYSE: HWM) may all be appealing candidates for these reasons.
BWX Finds a Lucrative Niche in Nuclear Propulsion
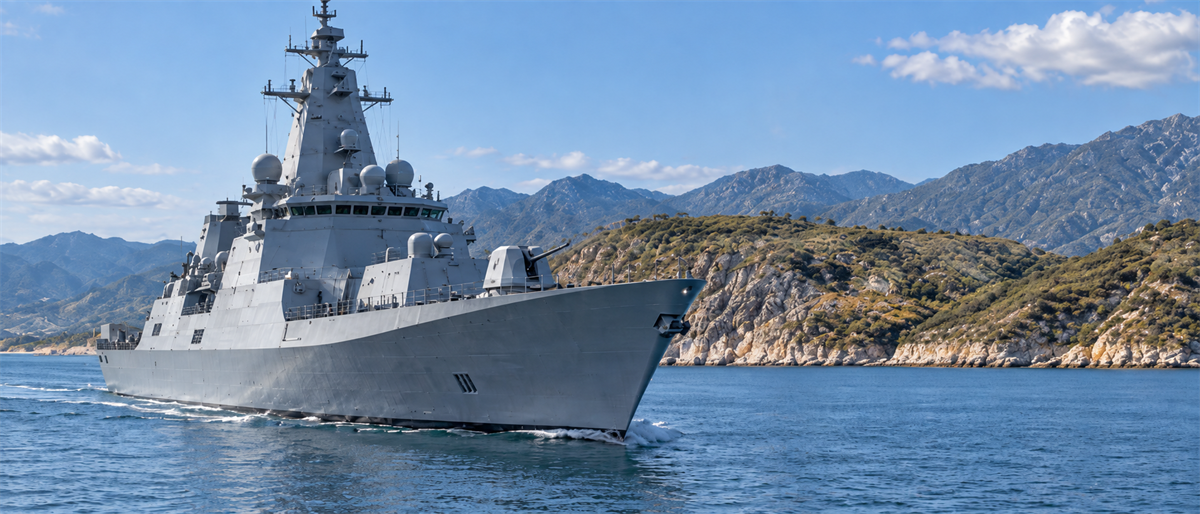
BWX is a nuclear component maker that caters to the nuclear energy market as well as customers in the medical field and the U.S. government. In particular, its efforts in designing nuclear reactors and components for naval vessels have made it a major player in the U.S. Navy's nuclear propulsion program.
This has led to noteworthy demand and backlog—the latter of these climbed 40% year over year (YOY) to $8.4 billion for the latest quarter.
BWX's niche relationship with the U.S. Navy has also meant a boost to its top and bottom lines: Q2 2026 revenue climbed 18% to about $902 million, just shy of analyst predictions, and adjusted EBITDA and adjusted earnings per share (EPS) were also up YOY. The company's leadership raised its full-year guidance in response.
There's reason to believe that this momentum could continue, and that it may reverse BWXT stock's downward performance trend (shares have fallen about 20% so far in 2026). Over the summer, the company secured a contract with the National Nuclear Security Administration to develop a new lithium processing facility.
Additionally, BWX is narrowing its focus by selling its medical business for up to $800 million, both a hefty boost to its capital reserves and a chance to prioritize its highest-potential operations.
Mercury's Financials Are Continuing to Improve as Defense Moves Toward Software
Mercury's role in the defense industry is different—this firm provides a variety of secure processing hardware, computer equipment, sensors, and other subsystems for aircraft, missiles, and radar tools. The large-scale shift of the defense industry toward software and electronics means that Mercury has an increasingly important role to play.
Like BWX, Mercury reported impressive bookings and backlog in its latest quarter, with bookings rising 93% YOY to $660 million and the backlog approaching $2 billion. Similarly, the company boosted its forward guidance, anticipating fiscal 2027 revenue to be nearly $1.1 billion.
Mercury is improving its margins, with adjusted EBITDA margin climbing by 217 basis points last quarter to 15.3%.
Shares of MRCY have behaved differently from BWXT stock, rising by about 14% year to date (YTD) overall despite shedding about 7% in the last month. As the company demonstrates that it can continue to chip away at efficiency issues with its manufacturing while maintaining high-quality revenue growth, it may better justify analysts' optimistic views of the stock, including calls for about 33% in possible upside.
Howmet Holds Its Own Against GE
Perhaps best known for its engineered components for commercial aerospace applications, Howmet is continuing to expand its offerings for the defense sector as well.
The company may present a buy-the-dip opportunity for investors following news that GE Aerospace (NYSE: GE) would spend $12 billion to acquire Consolidated Precision Products, a rival aerospace component maker. While this move would appear to threaten Howmet's grasp of its customer base, the reality of significant capacity shortages across the industry may mean that both firms see continued strong demand for years to come.
Even after the recent 13% dip in the past month, HWM stock is still up 12% YTD, a sign that investors see strengths in the company's operations and financials. In the last quarter, this was reflected in strong top- and bottom-line beats over analyst predictions, including 24% YOY revenue growth on broad demand strength.
Howmet even benefits from data center demand that has driven interest in its gas turbines. And for its part, Howmet is also attempting to consolidate. Like GE, the company made a major purchase earlier this year in Consolidated Aerospace Manufacturing, which expands both its manufacturing capacity and its product offerings. Howmet could continue to benefit from the essential nature of the products it provides to both commercial and military planes.
The article "3 Defense Stocks Riding Nuclear, Missile, and Aerospace Demand" first appeared on MarketBeat.