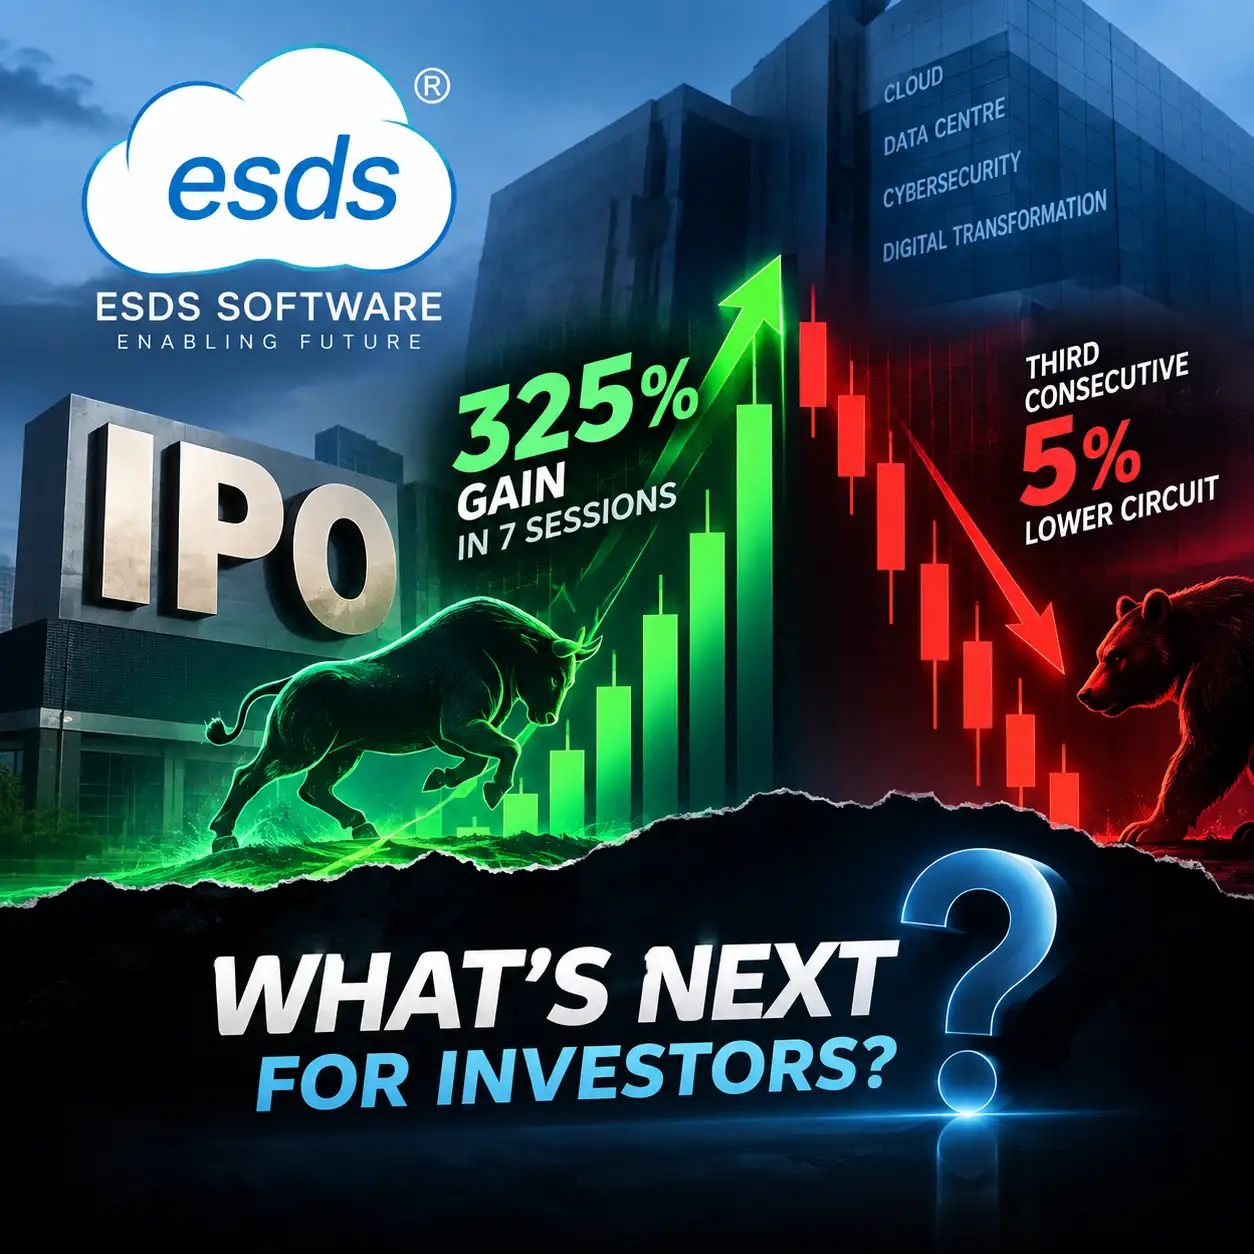
The dream run in ESDS Software Solutions shares appears to be weakening, with the stock now locked in a 5% lower circuit for a third consecutive session after delivering multifold returns within 7 days of market debut. The sharp reversal comes after a blistering post-listing rally that had quickly made ESDS 2026’s standout IPO performer.
ESDS, an AI-enabled end-to-end IT services provider offering data centre, cloud, colocation, managed services and AI infrastructure solutions, listed at a 76% premium to its issue price of Rs 429 per share.
The stock ended its listing day more than 110% above the issue price, before hitting a 20% upper circuit for the next two sessions, followed by three sessions of 10% gains and another 5% rise. The streak took the stock’s gains to 325% in just seven sessions before investors began booking profits and the post-IPO frenzy started to cool.
Decoding ESDS’ mammoth rally
The stock's explosive post-listing performance follows equally strong demand during its public issue. The ESDS Software Solution IPO was subscribed 136 times overall, highlighting aggressive investor interest across categories. The qualified institutional buyer (QIB) portion was subscribed more than 261 times, while the non-institutional investor and retail portions were subscribed around 193 times and 40 times, respectively.
The investment comes at a time when demand for cloud computing, data storage, cybersecurity and digital infrastructure is accelerating, potentially creating a favourable operating environment for companies such as ESDS.
A substantial portion of the funds raised through the IPO is earmarked for strengthening the company's digital infrastructure capabilities. Around Rs 576 crore is proposed to be invested in the purchase and installation of cloud-computing equipment and other data-centre infrastructure.
Also read: Tata Group stocks fall 8% as Tata Trusts calls Chandrasekaran’s extension illegal
The company's financial performance also showed a significant improvement in FY26. Total income rose 28% year-on-year to Rs 480.65 crore in FY26, compared with Rs 376.64 crore in FY25. More notably, profitability surged. Profit after tax (PAT) more than doubled to Rs 120.82 crore, marking a 117% increase from Rs 55.61 crore in the previous financial year.
Time to be cautious, investors?
“Fresh investors should avoid chasing at current levels and wait for a meaningful correction, as valuations have become stretched (from a reasonable ~42x FY26 earnings at IPO to 140–170x now).” Santosh Meena, Head of Research at swastika investmart, told ETMarkets. Allotted investors, sitting on life-changing gains in days, should book partial profits aggressively (40–60% or more) to lock in returns while retaining a core holding for the longer-term story, given the high risk of sharp reversals once momentum fades.
The rally mixes genuine thematic excitement with FOMO and scarcity premium; upside remains possible if AI capacity ramps smoothly and India’s cloud/GPU markets deliver the projected 20–50% CAGRs, but much of the multi-year optimism is already priced in, leaving limited margin of safety and elevated execution risk.
Fundamentally, the industry looks robust: India’s data-centre capacity is set to expand several-fold by 2030 on the back of cloud adoption, data localisation, digitalisation and AI workloads, with significant capital commitments from hyperscalers and domestic players.
ESDS is well-positioned as a full-stack sovereign-cloud and AI-infra provider with improving margins, sticky customers and expansion plans funded by the IPO, but near-term success hinges on timely capacity addition and contract delivery. Overall, treat it as a high-beta thematic bet—rewarding for early allottees who de-risk, risky for late entrants at peak valuations.
India’s data centre push
Even as India continues to lag markets such as South Korea and Taiwan in direct exposure to the AI and semiconductor cycle, a different AI-linked investment theme is gathering momentum at home.
India's data centre industry is entering a multi-year growth phase, driven by accelerating digitalisation, rising cloud adoption and growing artificial intelligence demand.
Also read: NSE IPO Tracker: Catch all the highlights here
According to international brokerage Nomura, India's data centre IT load has expanded from around 350 MW in 2019 to nearly 1.5-1.6 GW in 2025, translating into a CAGR of about 29%, compared with roughly 20% globally. As a result, India's share of global data centre capacity has increased from around 1.5% in 2019 to approximately 2-3% in 2025.
A KPMG report projects the country's data centre industry revenue to reach nearly $45.69 billion by 2033, driven by rising AI workloads, rapid cloud adoption and data localisation requirements. "With one billion internet users and businesses rapidly adopting cloud services, building domestic data centres is now a necessity," the report noted.
Disclaimer: This article has been written by Veer Sharma, who is not a SEBI-registered Research Analyst or an Investment Adviser. Veer Sharma and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.