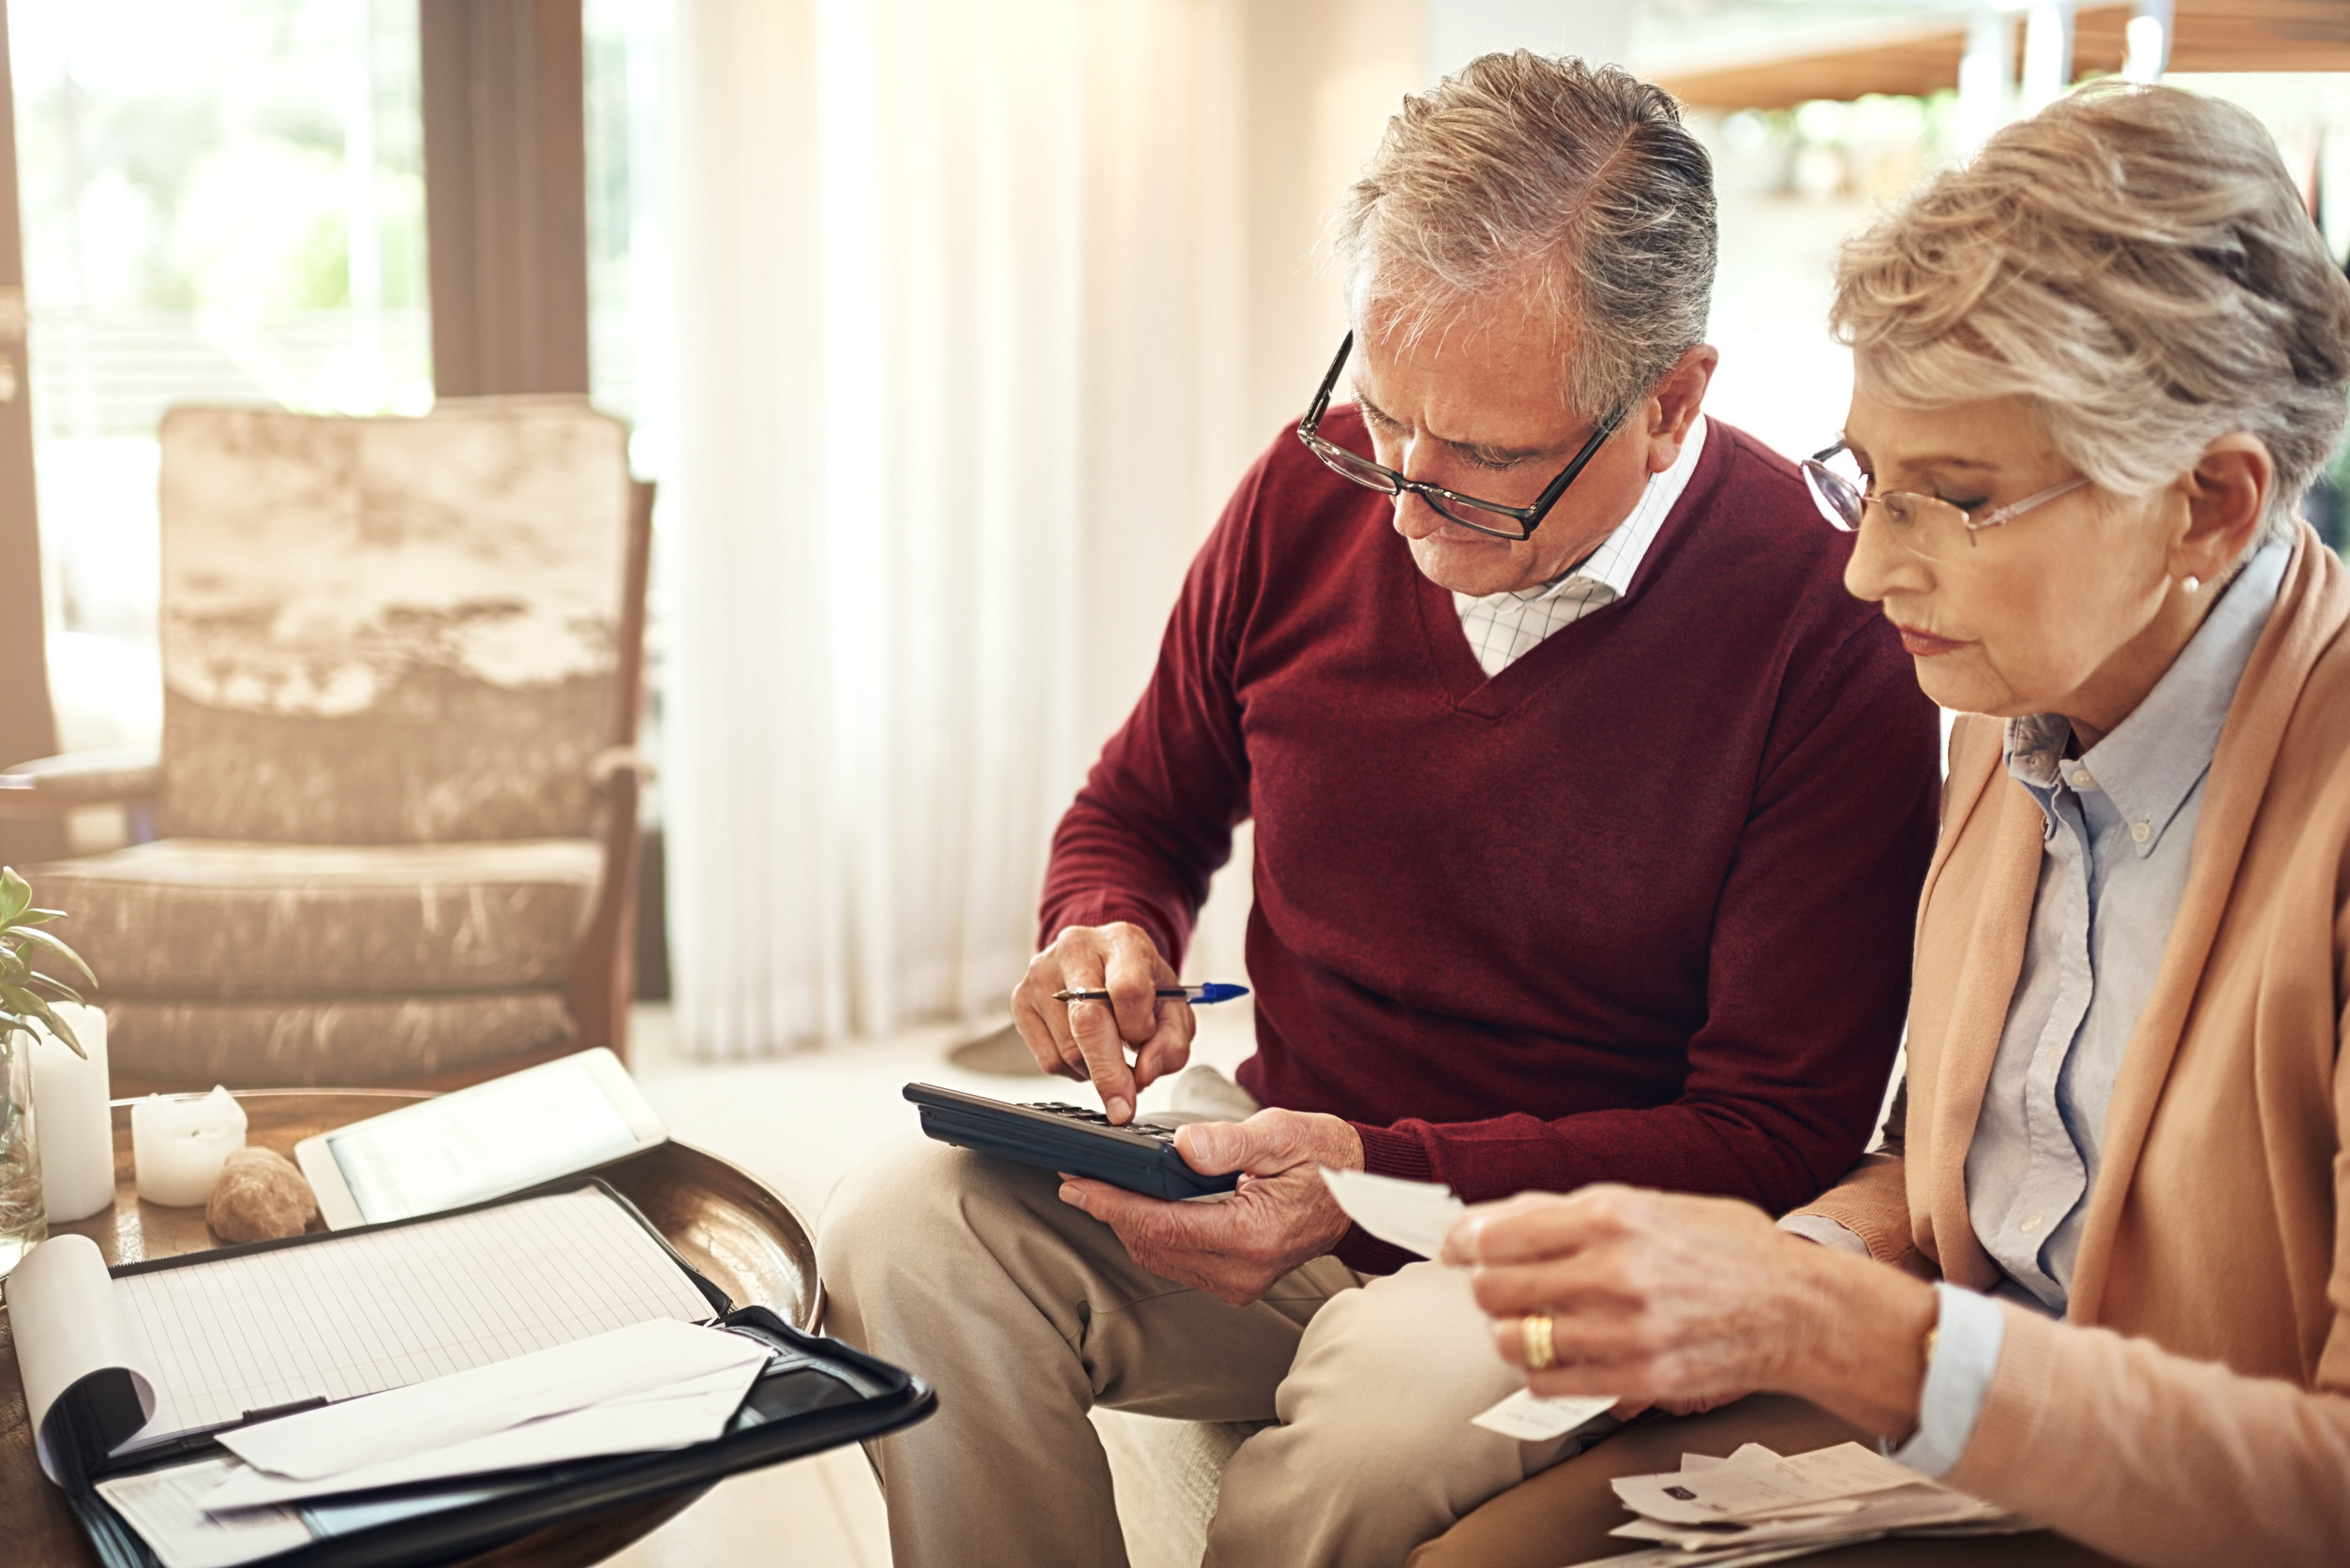
Many retirees think glidepaths—the shift in asset allocation over time—are one-size-fits-all. Yet the traditional “stocks early, bonds later” formula often ignores the reality of how people actually spend in retirement. Medical costs, travel dreams, and housing needs don’t follow tidy graphs. When portfolios are built without accounting for these patterns, retirees risk mismatches between income and expenses. Smart glidepath designs align investments with real-life spending, not just abstract theories.